
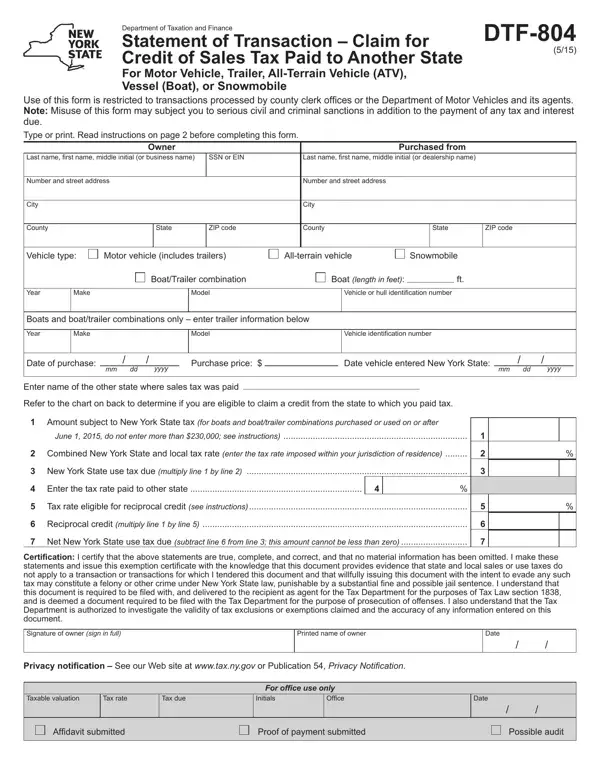

Form DTF-804 at a glance
What it is: Form DTF-804 is the Statement of Transaction, Claim for Credit of Sales Tax Paid to Another State, for a Motor Vehicle, Trailer, All-Terrain Vehicle (ATV), Vessel (Boat), or Snowmobile.
Who signs: Signature of owner (sign in full), Printed name of owner, Date.
This form is to be used by a purchaser of a motor vehicle, all-terrain vehicle, trailer, vessel, or snowmobile (qualifying vehicle or vessel) to report the sales and use tax due on a purchase for which the purchaser wants to claim a credit for sales tax paid to another state.
A New York State resident who purchases a qualifying vehicle or vessel outside the state becomes liable for New York State and local sales and use tax if the qualifying vehicle or vessel is brought into the state.
A filled-in Form DTF-804 example: a car bought in Florida
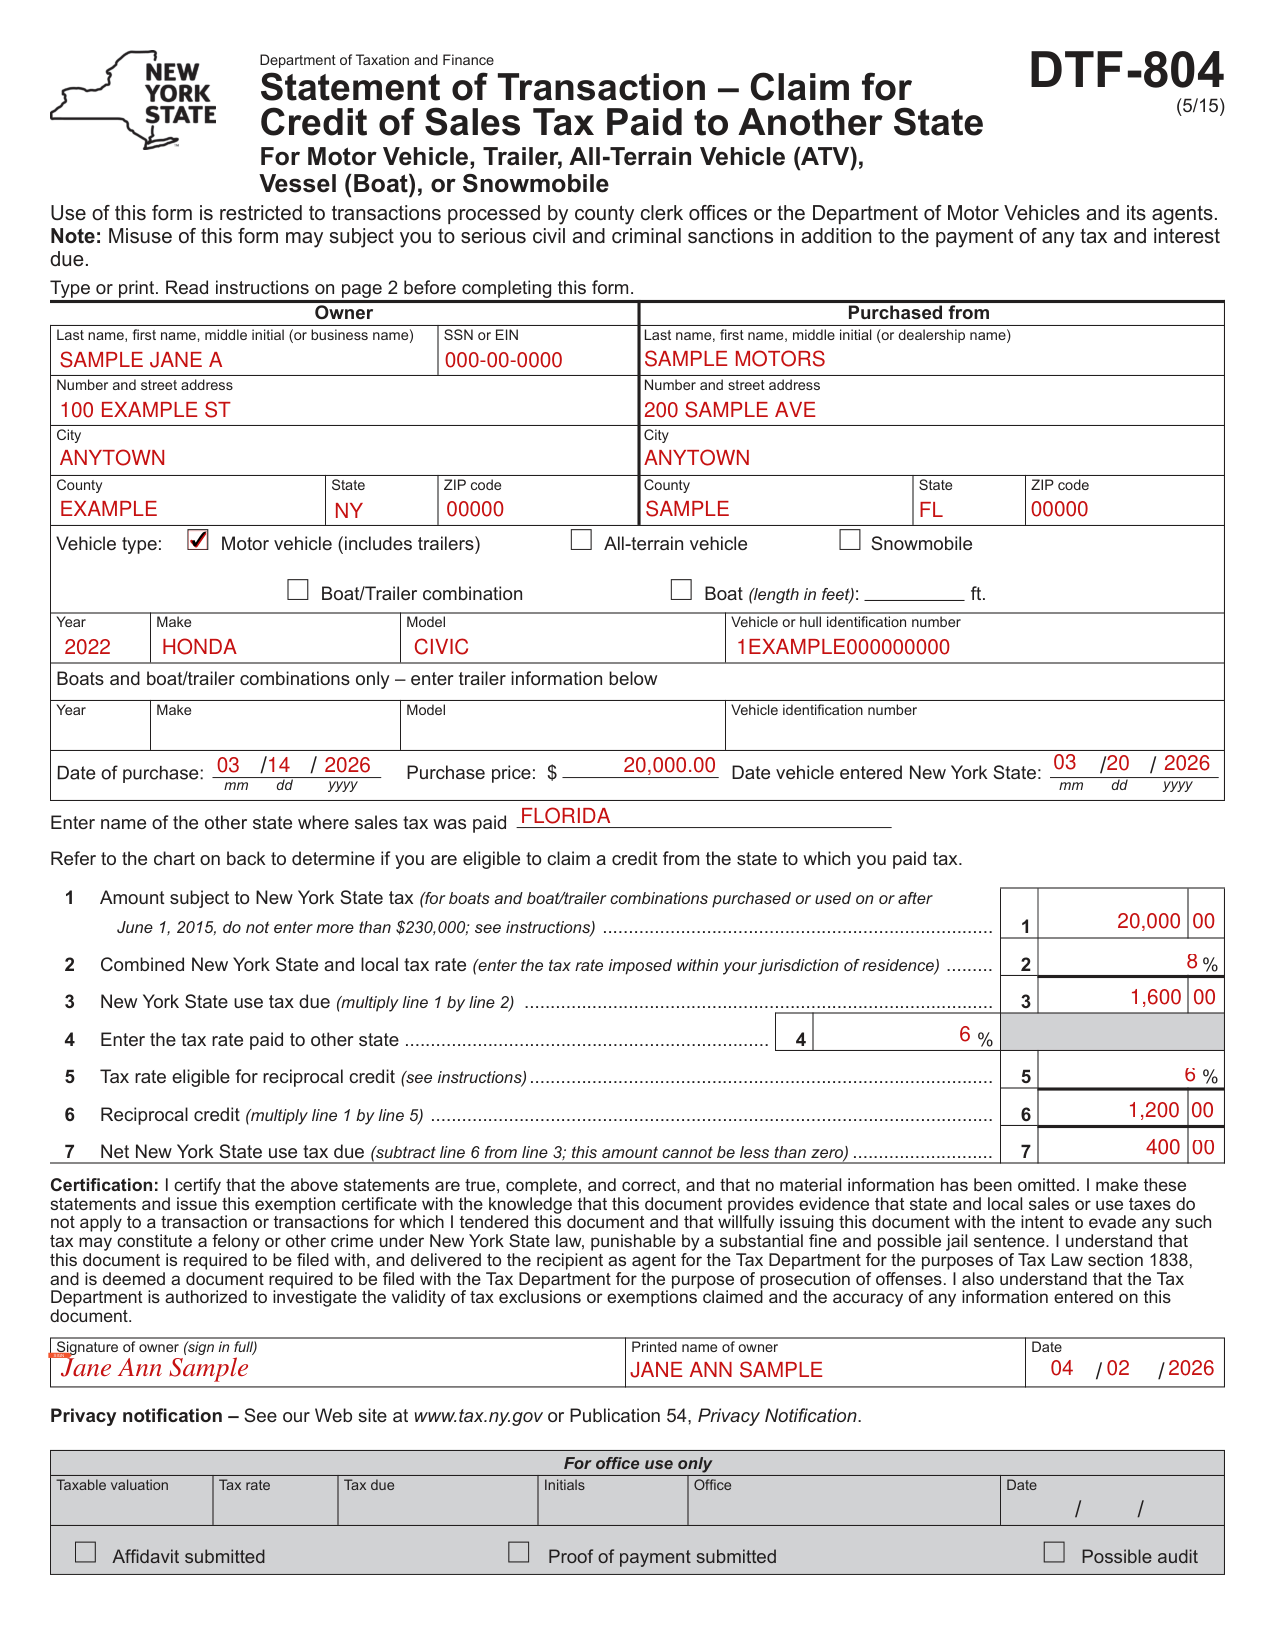
How to fill out Form DTF-804, box by box
The owner and who you purchased from
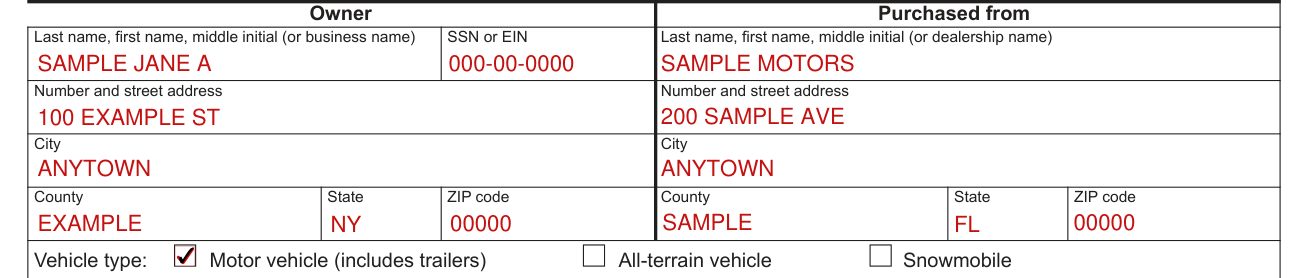
Enter the owner information. Complete all entries, including the owner's social security number (SSN) or employer identification number (EIN).
Enter the name and address of the person or dealership from whom the qualifying vehicle or vessel was purchased.
The vehicle and its identification
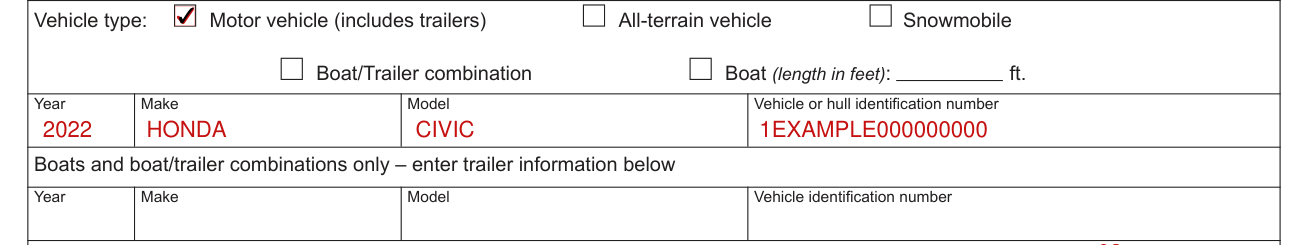
Vehicle type: Motor vehicle (includes trailers), All-terrain vehicle, Snowmobile.
Enter the qualifying vehicle or vessel identification information.
Boats and boat/trailer combinations only: enter trailer information.
Dates, price and the state you paid

Enter the date of purchase and the purchase price. Purchase price includes any monetary consideration, the value of any property exchanged or traded (other than a trade-in allowance granted by a dealer), and any assumption of a debt or liability of the seller.
Also enter the date the vehicle entered New York State.
Enter the name of the state to which the sales tax was paid.
Lines 1 to 7, the credit
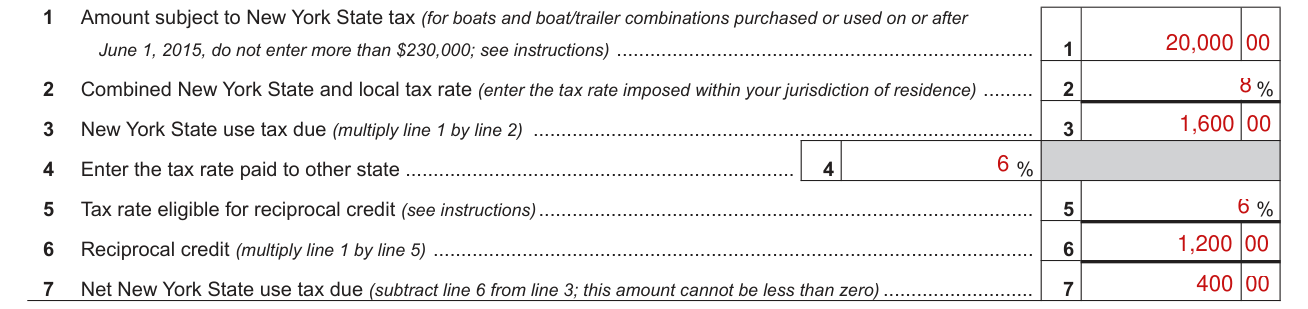
Line 1: Enter the amount subject to New York State sales tax. This amount is either the purchase price entered or, if the vehicle was used outside New York State for more than six months before it was brought into the state, the fair market value, whichever is lower.
Line 1: Amount subject to New York State tax (for boats and boat/trailer combinations purchased or used on or after June 1, 2015, do not enter more than $230,000; see instructions) (checked November 11, 2026).
See TSB-M-15(2)S, Change to the Application of Sales and Use Tax on Vessels.
Line 2: Combined New York State and local tax rate (enter the tax rate imposed within your jurisdiction of residence).
Line 2: The applicable local rate of tax on the purchase or use of a qualifying vehicle or vessel is the rate of tax for the locality in which the purchaser is a resident.
If the purchaser is a resident of more than one locality within the state, the applicable local tax rate is the rate of tax for that locality where the purchaser is a resident and the qualifying vehicle or vessel is principally used or garaged.
Refer to Publication 718, New York State Sales and Use Tax Rates by Jurisdiction, for a listing of current combined state and local tax rates.
Line 3: New York State use tax due (multiply line 1 by line 2).
Line 4: Enter the tax rate paid to other state.
Line 5: Tax rate eligible for reciprocal credit (see instructions).
Line 5: Enter the tax rate eligible for credit.
Use the charts to determine the correct rate of tax eligible for credit for the state where you made the purchase, based on the type of vehicle you purchased.
The maximum rate eligible for credit cannot be higher than the rate of tax imposed within your jurisdiction of residence (see line 2 on the front).
If you made your purchase in a state listed under Special rules in the charts, be sure to calculate the allowable credit exactly as explained.
Indiana: Credit is allowed only against the 4% state portion of the New York State tax for tax paid to Indiana. Enter on line 5 the lesser of the 4% New York State rate or the Indiana rate.
Any excess reciprocal credit cannot be refunded or used to offset any other sales or use tax liabilities.
For more information regarding reciprocal credits, see Tax Bulletin ST-765 (TB-ST-765), Reciprocal Credit for Sales or Use Taxes Paid to Other Taxing Jurisdictions. You may be eligible for a refund of the taxes paid to the other state (see Note: above).
Line 6: Reciprocal credit (multiply line 1 by line 5).
Line 7: Net New York State use tax due (subtract line 6 from line 3; this amount cannot be less than zero).
Signing

Signature of owner (sign in full), Printed name of owner, Date.
If your situation is different
No reciprocal credit is available
For motor vehicles, New York State provides a reciprocal credit for tax paid to a very limited number of states.
If no reciprocal credit is available, use Form DTF-802, Statement of Transaction, Sale or Gift of Motor Vehicle, Trailer, All-Terrain Vehicle (ATV), Vessel (Boat), or Snowmobile, instead of this form.
If you paid tax to a state for which no New York State reciprocal credit is allowed you should apply to that state for a refund.
If the state denies the refund you may be eligible for a credit for some or all of the New York tax you must pay now.
A credit may be available
However, a credit against the New York tax due may be available if all of the following apply: the buyer was required to pay tax to another state on the purchase; that state provides a reciprocal tax credit that is similar to the tax credit for New York State; and the buyer is not entitled to a refund of that tax from the other state.
If all these conditions are met, then the buyer may be granted a credit against the use tax due to New York State for the tax paid (or a portion of the tax paid) to the other state.
Before you go
Type or print. Read instructions on page 2 before completing this form.
Note: Before completing this form, refer to the charts to determine if New York State provides a reciprocal credit for sales tax paid to the state where you made your purchase.
Refer to the chart on back to determine if you are eligible to claim a credit from the state to which you paid tax.
Sources
[1] Form DTF-804 (5/15), Statement of Transaction, Claim for Credit of Sales Tax Paid to Another State, New York State Department of Taxation and Finance (the Official source link on this page).