
Updated:
A family loan agreement is a loan contract between relatives or friends. This free template records in writing the amount, interest rate, repayment schedule and last day of the loan. Families use it to keep repayment clear, especially when payments stretch over a long term.
Build Your Document
Answer a few simple questions to make your document in minutes
Save and Print
Save progress and finish on any device, download and print anytime
Sign and Use
Your valid, lawyer-approved document is ready

A family loan agreement is a signed document that names the Borrower and the Lender and sets out how much was lent, what interest applies and how the money comes back. It works the same way for a parent lending to a child, for siblings and for two friends. The FormsPal form is titled Family (Friends) Personal Loan Agreement, so a loan between friends fits it too.
The agreement gives both sides one version of the terms to go back to, so nobody has to rely on memory years later. For a loan outside family and friends, start from our loan agreement template page.
A family loan agreement fits any loan where the lender expects the money back and the two of you want the terms settled before the money moves. It is most useful in these situations:
A family loan agreement covers the parties, the amount, the interest, the repayment plan, the last day, default, the governing state and the signatures. The template has a blank or a choice for each item below, apart from the extras noted under additional terms.
Download the form from this page and fill it in with the FormsPal PDF editor, or print it and write by hand. These steps follow the FormsPal template this page hands out, in the order the form asks for each entry. Have the names, the loan amount and the repayment plan ready before you start.
The screenshots under each step show the FormsPal Family (Friends) Personal Loan Agreement template filled with sample entries in blue, so you can see where each answer goes. The names, addresses, dates and amounts are examples only.
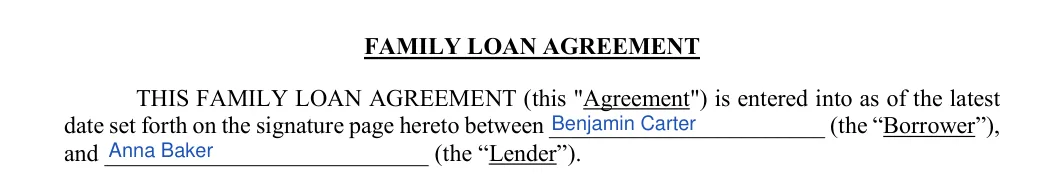
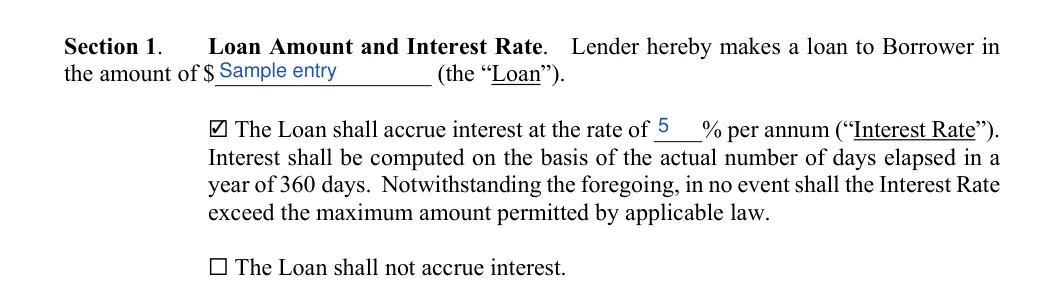
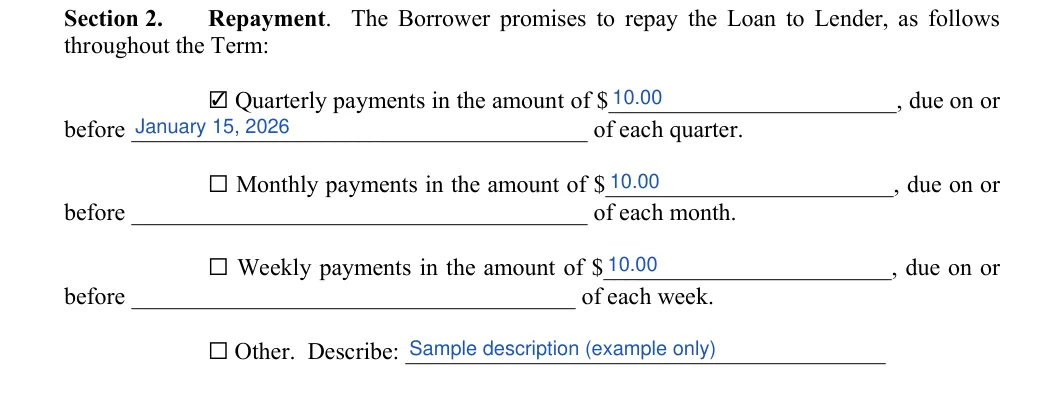
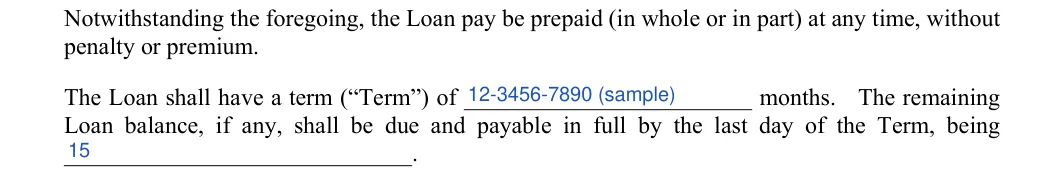
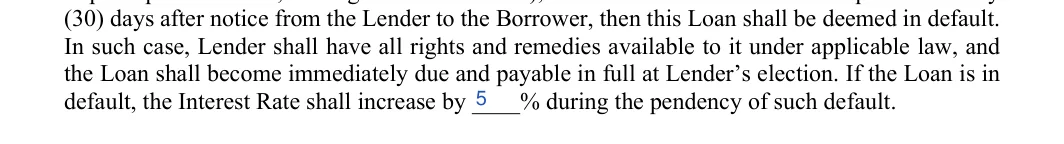
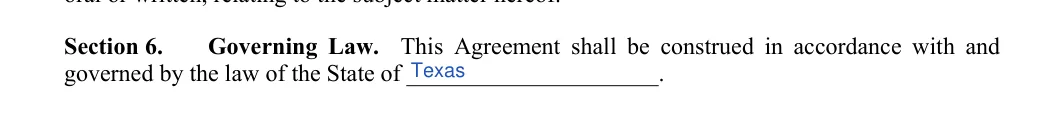
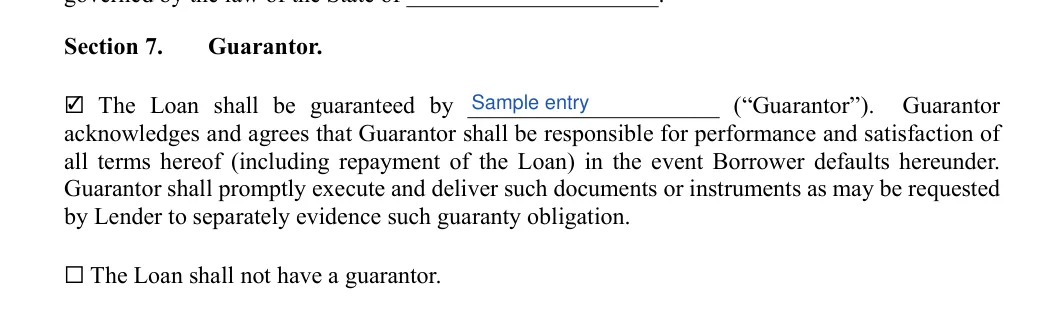
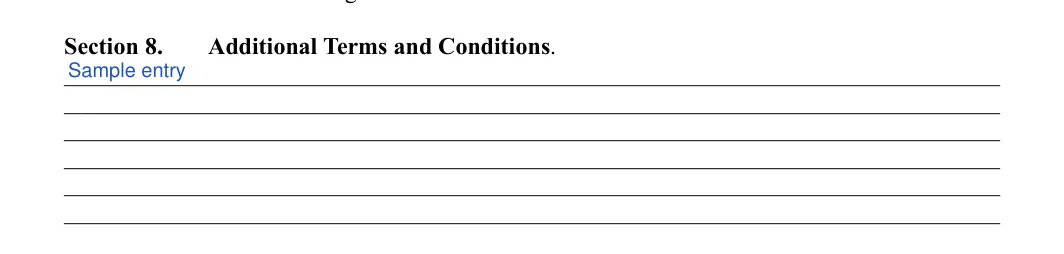
This family loan agreement sample shows how the main terms read once the template is filled in, using invented people and figures. It is a guide to the level of detail, never a set of terms to copy.
Example only: invented people and figures.
Replace every entry with your own terms, and compare your rate with the interest rules below before anyone signs.
A family loan agreement is ready to sign once both sides have read the completed entries and agree they match the deal. Go through the steps below in order, with the other side present if you can, so any question is settled before anyone signs.
A family loan can carry a yearly interest rate or no interest at all, and the template asks you to pick one before you agree the repayments. The rate is also the term to check against the rule in your state.
Interest limits differ from state to state, and in several of the rows below a rate put in writing falls under a different rule from one that is not. These five states show how far apart the rules sit.
| State | Rule for the interest rate | Citation |
|---|---|---|
| Arizona | Any rate may be agreed when it is contracted for in writing. With no different written rate, interest is ten percent a year. Medical debt is excepted. | Ariz. Rev. Stat. § 44-1201 |
| California | By written contract, up to 10 percent per annum when the money is for use primarily for personal, family or household purposes. With no written rate, 7 percent per annum. Banks, credit unions and other lenders the section exempts fall outside the limit. | Cal. Const. art. XV, § 1 |
| Missouri | By written agreement, up to ten percent per annum. When the market rate exceeds ten percent per annum, the written rate may go up to the market rate. | Mo. Rev. Stat. § 408.030 |
| New York | The maximum rate provided for in General Obligations Law section 5-501 is sixteen percent per annum. | N.Y. Banking Law § 14-a |
| West Virginia | By written contract, up to $8 upon $100 for a year, including points. On a contract not in writing, no more than $6 upon $100 for a year, except where the law specially provides otherwise. | W. Va. Code § 47-6-5 |
These rows are examples, not a full list. Other states are not covered here, so read your own state's statute before you enter a rate.
Writing the rate down can change which rate applies, because several of these rules turn on a written contract. In Arizona, any rate of interest may be agreed to once it is contracted for in writing, under Ariz. Rev. Stat. § 44-1201, so a state cap on a written family loan is not a given. In Missouri, under Mo. Rev. Stat. § 408.030, parties may agree in writing to a rate up to ten percent per annum, and when the market rate exceeds ten percent, they may agree in writing to a rate up to the market rate.
The result of charging too much interest depends on the state, and West Virginia shows how serious it can be. A contract there at a greater rate than the law permits is void as to all interest, under W. Va. Code § 47-6-6. The borrower may also recover from the original lender or creditor or other holder not in due course an amount equal to four times all interest agreed to be paid, with a minimum of $100, under W. Va. Code § 47-6-6.
This template does not settle tax questions, so ask a tax professional how gift tax and the applicable federal rate apply to your loan before you choose a low rate or no interest.
When a family loan falls into default, both sides work from what the agreement says about default and any guarantor, and from their own notes of each payment. That is why it pays to fill in those parts with care, even when nobody expects trouble.
Talk first when a payment is missed. If you agree on a new schedule, write it down and have both sides sign and date the change. If talking does not settle it, a local lawyer can tell you which collection steps are open to you.
A family loan can be easier to arrange than a bank loan, but it also carries risks of its own. The pros and cons below can help you decide whether lending or borrowing within the family makes sense for you.
A family loan agreement fits money that will be repaid on agreed terms, while a gift, a co-signed bank loan or a promissory note suits other situations. Decide which one you actually mean before you fill in any form.
A gift is money handed over with no promise to repay, so no loan agreement is needed. Ask a tax professional whether a gift of your size brings gift tax.
Co-signing helps a relative get a bank loan without lending your own money, because the bank provides the funds. The co-signer may be liable to pay if the borrower defaults, so read the bank's terms first.
A promissory note is a shorter document in which the borrower promises to repay, and it suits a simple loan with few terms. Our promissory note template is the place to start for a family member's note. A family loan agreement gives you more room for a schedule, a guarantor and additional terms.
Yes, relatives can lend each other money, and a family loan agreement puts the amount, the interest and the repayment terms in one signed document. Check the interest rule in your state before you set a rate.
Yes, the family loan agreement template lets you record a loan with no interest by ticking the no-interest box. The template gives you two choices in Section 1. Tick the first box and enter a yearly interest rate, or tick the second box if the loan should not accrue interest. Read the tax question above before you choose.
Yes, the form asks only for a Borrower and a Lender, so a parent lending to a child or one friend lending to another fills it in the same way. A short note on how the Borrower and Lender are related can go in the additional terms.
Yes. Press the Create My Document button to answer a few questions and fill in the family loan agreement template online, or download the PDF and complete it on your computer. You can also print it and write by hand.
The download on this page is a PDF file, and this page offers no Word version. To build your document by answering questions instead, press the Create My Document button.
Section 7 has a box for a guarantor and a line for their name. If you tick it, the guarantor has a signature line on page 3.
Section 8 has several lines for additional terms and conditions. Write one point per line, or leave the lines empty if there is nothing to add.
General information, not legal or tax advice.
