
A real estate purchase agreement is a document that is meant to outline the purchase price, date, and other important details of the real estate deal. It is a crucial agreement in every real estate transaction as it fixes the terms of sale and gives legal protection for both parties.
Last Updated: October 2026. This guide is reviewed and updated regularly to reflect current law. If you notice an error or outdated information, please contact us.
Build Your Document
Answer a few simple questions to make your document in minutes
Save and Print
Save progress and finish on any device, download and print anytime
Sign and Use
Your valid, lawyer-approved document is ready
Purchase agreement addendums are documents you attach to the agreement to add details the original left out. An addendum can also override a clause in the original without crossing anything out of it.
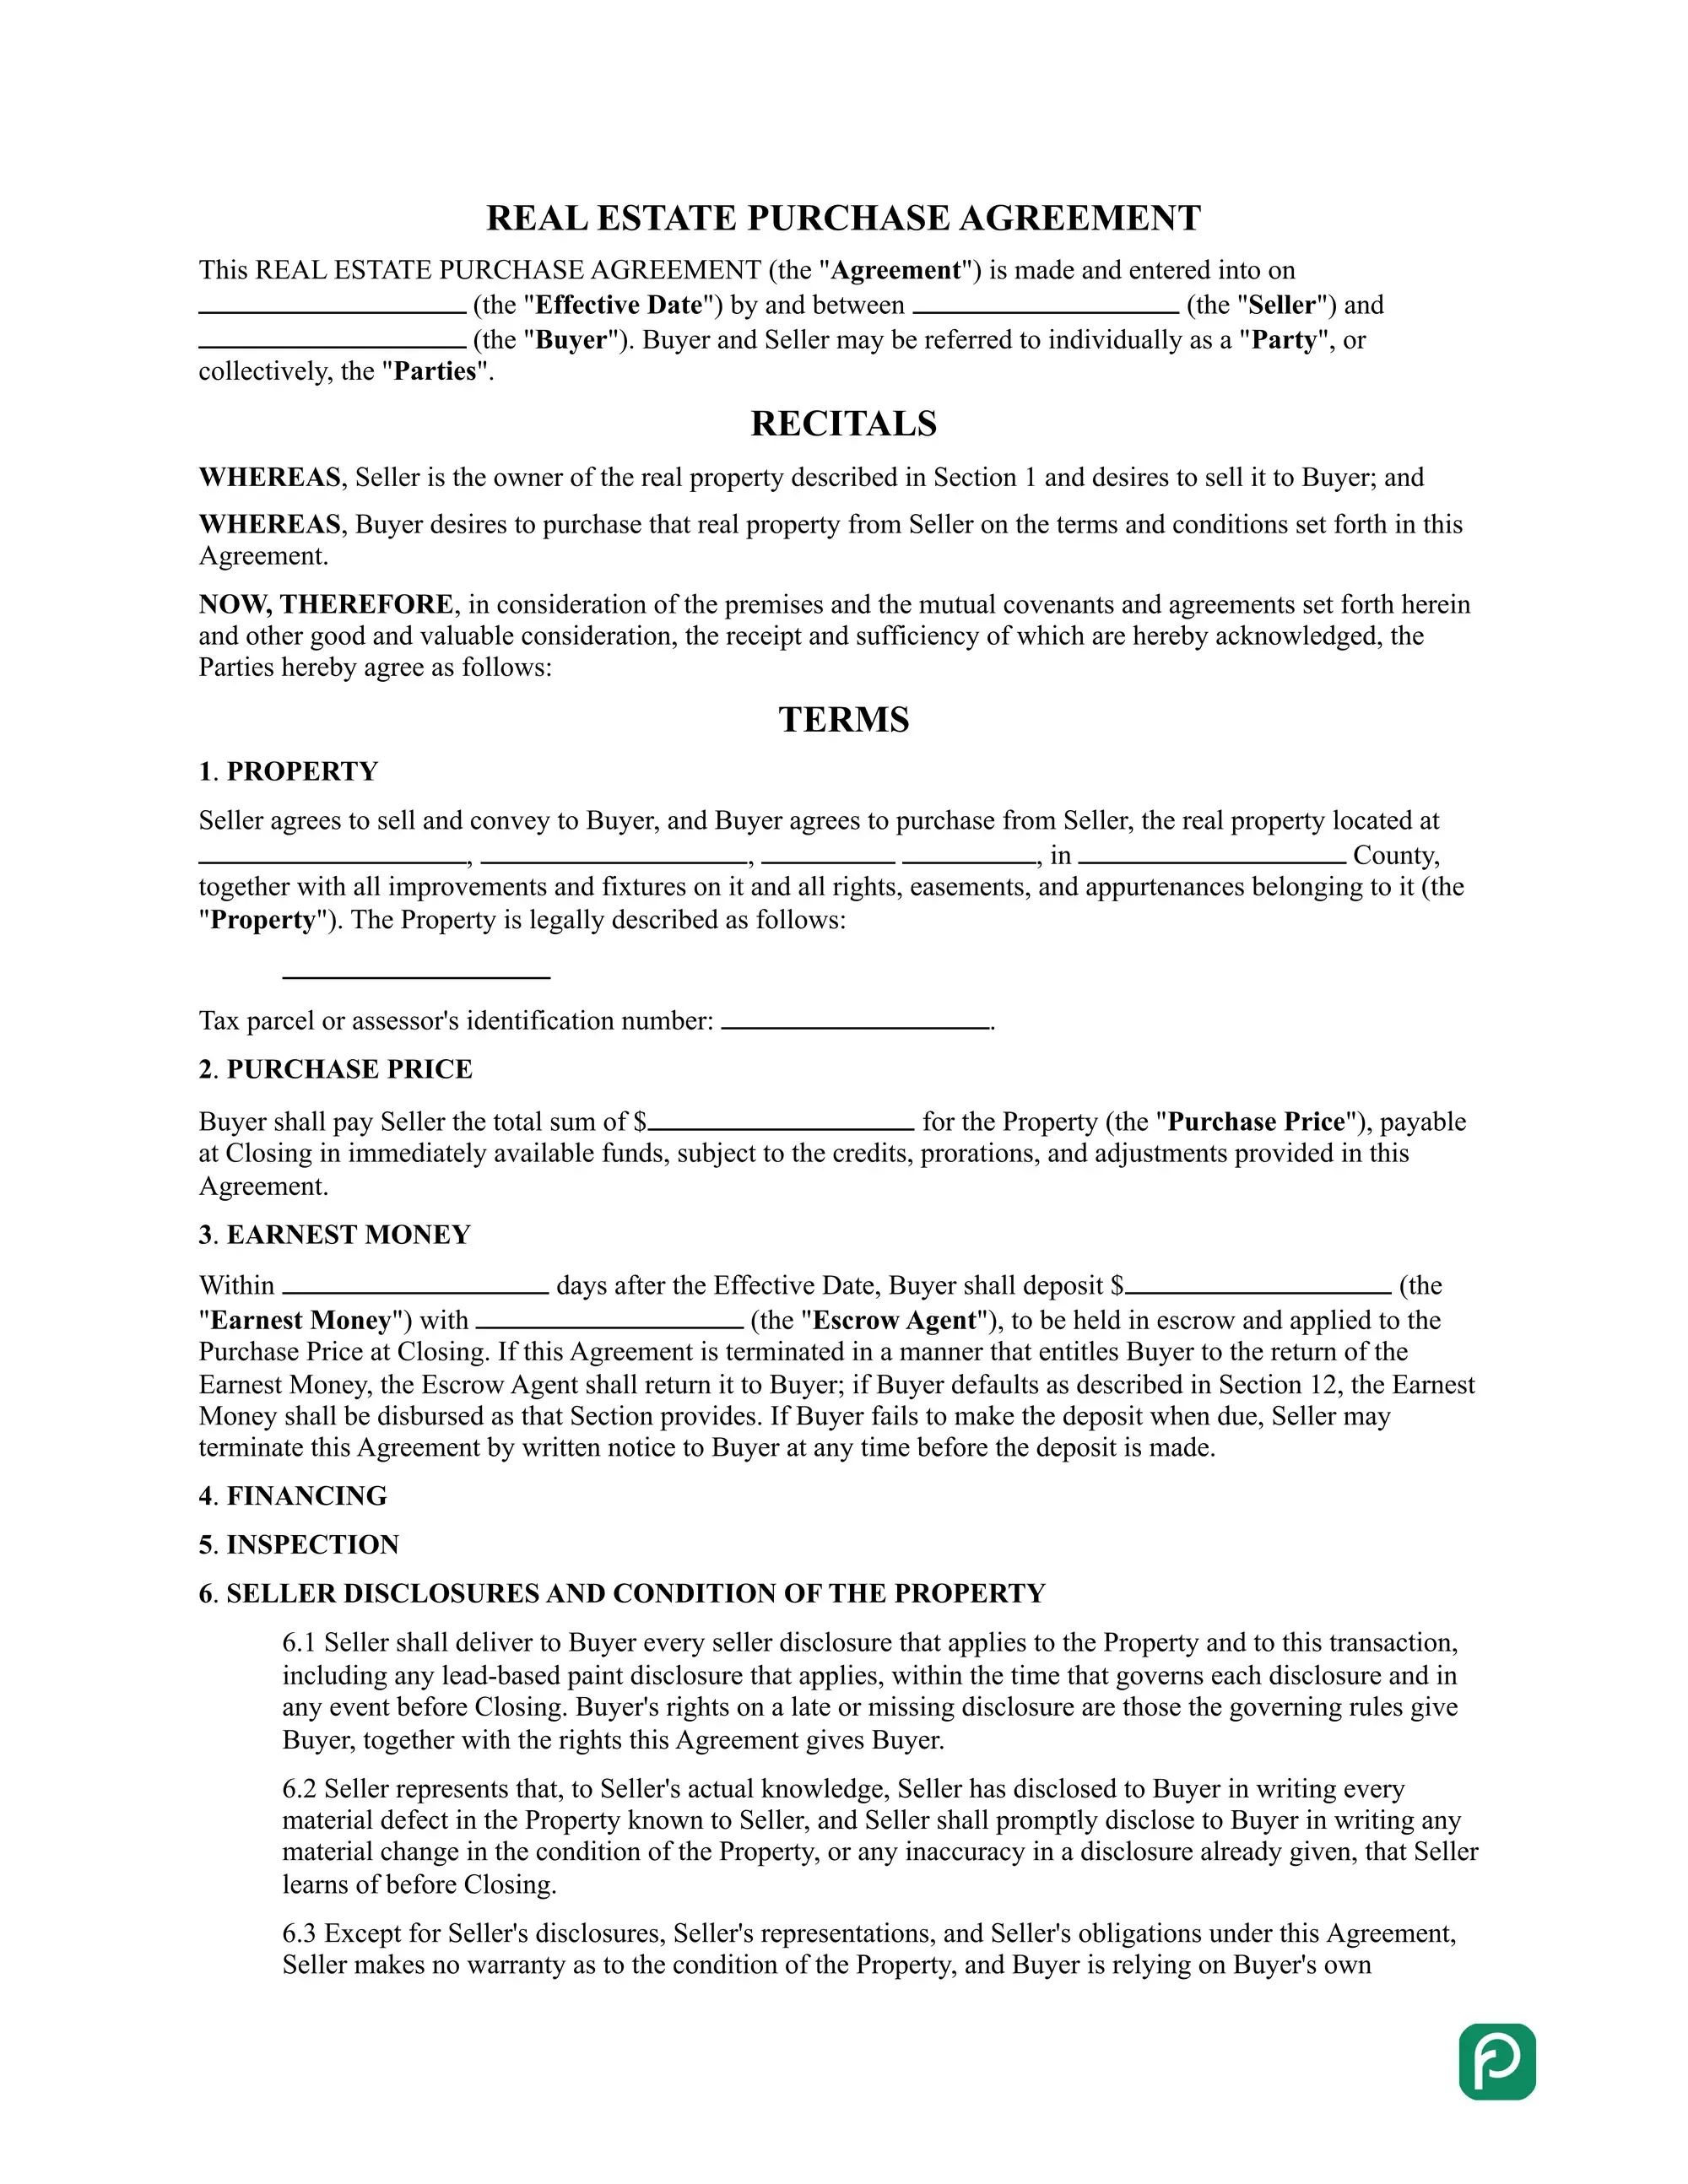
A real estate purchase agreement is a written contract between a buyer and a seller of property. It records the price and the closing date, and it lists the conditions both sides must meet before the sale goes through. Once both parties sign, it becomes the main contract for the deal.
A purchase agreement usually covers these points.
The exact sections vary by state and by form. Read the whole contract, and ask a local attorney or agent if a term is unclear.
Buying a home takes time, patience and a few formal steps. Here are the seven steps most home buyers follow when they purchase a residential property. Each step builds on the one before it, so it helps to read them in order.
1. Look for a home or apartment for sale
You can find homes for sale in a few common ways.
2. Get a pre-qualification letter
If you need a mortgage, a pre-qualification letter can strengthen your offer. A bank issues it to show that you may be able to get financing from that lender. Sellers often take such offers more seriously.
3. Find the right real estate agent
A good agent knows the local area and the buying process, and can share information that is hard to find on your own. Agents also negotiate for you. Many buyers use one to be sure they see the best options nearby.
In many deals the seller pays the agent's commission, but the fee is often built into the price of the home. Ask every agent how they are paid before you sign anything.
4. Get private showings
Once you know your price range, arrange to visit homes in person. You or your agent can schedule the visits. Buyers usually get some time to look at a home before they decide to make an offer.
5. Craft a real estate purchase agreement and sign it with the seller
This is where you put your offer in writing. You draft the purchase agreement and send it to the seller, who can accept or reject it. Once both sides sign, its terms apply to both of you.
One of the buyer's first duties is usually to pay the deposit the parties agreed on.
6. Check the disclosures
Around the time you sign the purchase agreement, the seller should give you the disclosures that federal and state rules require. They tell you about known hazards or needed repairs. The timing varies by state.
Federal law requires sellers of homes built before 1978 to give the buyer a lead-based paint pamphlet and to disclose any known lead paint hazards. Old paint can crack over time and leave toxic dust that children can easily pick up.
If you paid an earnest money deposit, it is good practice to get a written receipt for it. The receipt documents the payment if a dispute comes up later.
Sellers in many states also fill out a property disclosure statement. It lists the physical problems and defects the seller knows about. It does not cover defects the seller does not know about.
7. Invite an inspector
Have a professional inspector check the home before closing. Inspectors know which defects are common in homes. If you work with an agent, they can help you book the inspection soon after the seller accepts your offer.
Both sides usually receive the inspection report. If it shows serious damage or items that need repair, you may be able to renegotiate the price or ask the seller to fix them. An inspection contingency in the contract can also let you withdraw and get your earnest money back. Many buyers do a final walk-through before closing to confirm that the repairs were done.
Caveat emptor is a Latin phrase that means "let the buyer beware." Under this principle, a buyer is expected to check goods thoroughly before buying them. If the buyer finds a defect afterward, the seller is generally not liable for it.
In real estate, caveat emptor means the buyer takes the property "as is" and is responsible for inspecting it. The buyer usually has little recourse for problems found after closing. Most states now require the seller to give the buyer a written disclosure of known defects.
The right column shows whether a state is "caveat emptor," where the buyer carries most of the risk of hidden defects. Most states covered here now require the seller to give a written disclosure of known defects. The rules change, and many cells have exceptions. Check the page for your state before you rely on any cell.
| STATE | Is the state “caveat emptor” (buyer beware)? |
| Alabama | Yes |
| Alaska | No |
| Arizona | No |
| Arkansas | Yes |
| California | No |
| Colorado | No |
| Connecticut | No |
| Delaware | No |
| Florida | No |
| Georgia | No |
| Hawaii | No |
| Idaho | No |
| Illinois | No |
| Indiana | No |
| Iowa | No |
| Kansas | No |
| Kentucky | No |
| Louisiana | No |
| Maine | No |
| Maryland | No |
| Massachusetts | Yes |
| Michigan | No |
| Minnesota | No |
| Mississippi | No |
| Missouri | Yes (a seller who knows methamphetamine was produced on the property must tell the buyer in writing) |
| Montana | Yes (but the seller must give the buyer a disclosure statement of known adverse material facts, and the statement is not a warranty) |
| Nebraska | No |
| Nevada | No |
| New Hampshire | Yes (but sellers are also required to disclose certain details) |
| New Jersey | Yes (but a seller must give the buyer a property condition disclosure statement on the form the state prescribes) |
| New Mexico | No |
| New York | No |
| North Carolina | No |
| North Dakota | No |
| Ohio | No |
| Oklahoma | No |
| Oregon | No |
| Pennsylvania | No |
| Rhode Island | No |
| South Carolina | No |
| South Dakota | No |
| Tennessee | No |
| Texas | No (but law covers only single-dwelling properties) |
| Utah | No laws that require to inform buyers about defects unless the property has been contaminated due to storage, manufacturing, or use of methamphetamine |
| Vermont | Yes |
| Virginia | Yes |
| Washington | No |
| Washington D.C. | No |
| West Virginia | Yes |
| Wisconsin | No |
| Wyoming | Yes |
A residential purchase agreement holds a lot of detail about the property, the parties and the terms of the sale. The steps below follow the order most agreements use. Proofread every entry before you sign, since the layout of your form may differ.
To build an agreement with these sections, use the document builder at the top of this page.
Most disputes over a purchase agreement start with missing or unclear details, not bad intent. A few habits can help you avoid trouble before closing. Review this list before you sign, and compare it with the terms in your own agreement.
Closing is the step where the title passes to the buyer and the buyer pays the remaining funds. The contract sets the closing date and place, and it says when the buyer takes possession. Most buyers also do a final walk-through shortly before closing.
At or before closing, expect these items.
If the seller needs more time to move out, both sides can agree on a later possession date in writing. A spoken promise is hard to prove, so add the new date to the contract.
Earnest money is a deposit the buyer pays to show good faith after the seller accepts an offer. An escrow agent or a title company usually holds it, and it is typically credited toward the price at closing. The amount and the refund terms are set in your agreement.
A buyer can often withdraw when a contingency is not met, such as a failed inspection or a denied loan. Backing out without such a reason may cost the buyer the deposit. Read the cancellation terms in your agreement before you sign.
The purchase agreement sets the main terms of the sale. An addendum is a separate document that adds or changes terms, such as an appraisal contingency. Both sides sign it so that it becomes part of the contract.
Closing costs depend on the agreement and on local custom. Buyers and sellers often split some costs, and the agreement should say who pays which. Your lender or closing agent can give you an estimate before the closing date.
In some deals the seller lends part of the price instead of a bank. The terms go into a document such as an owner financing addendum. Both sides should review the payment schedule and what happens if a payment is missed.
General information, not legal or tax advice.
