
Updated:
A loan agreement is a signed contract that sets a loan's terms. It lists the amount borrowed, the interest rate, the repayment schedule and the terms for a missed payment. Private lenders and borrowers use the agreement, especially for loans between relatives, friends or businesses.
Key facts
Build Your Document
Answer a few simple questions to make your document in minutes
Save and Print
Save progress and finish on any device, download and print anytime
Sign and Use
Your valid, lawyer-approved document is ready

A loan agreement is a signed contract for borrowing money that fixes the amount lent, the interest, the repayment dates and what happens if the borrower stops paying. The same document goes by borrowing agreement, contract for a loan or contract for loaning money.
The agreement binds both sides to the same terms. The lender promises to hand over the money. The borrower promises to pay it back, with interest if the parties agree to any.
The document differs from a bank's loan paperwork because the parties write the terms themselves. A private loan agreement suits a cash loan between people, a loan to a small business or a car financed by its seller.
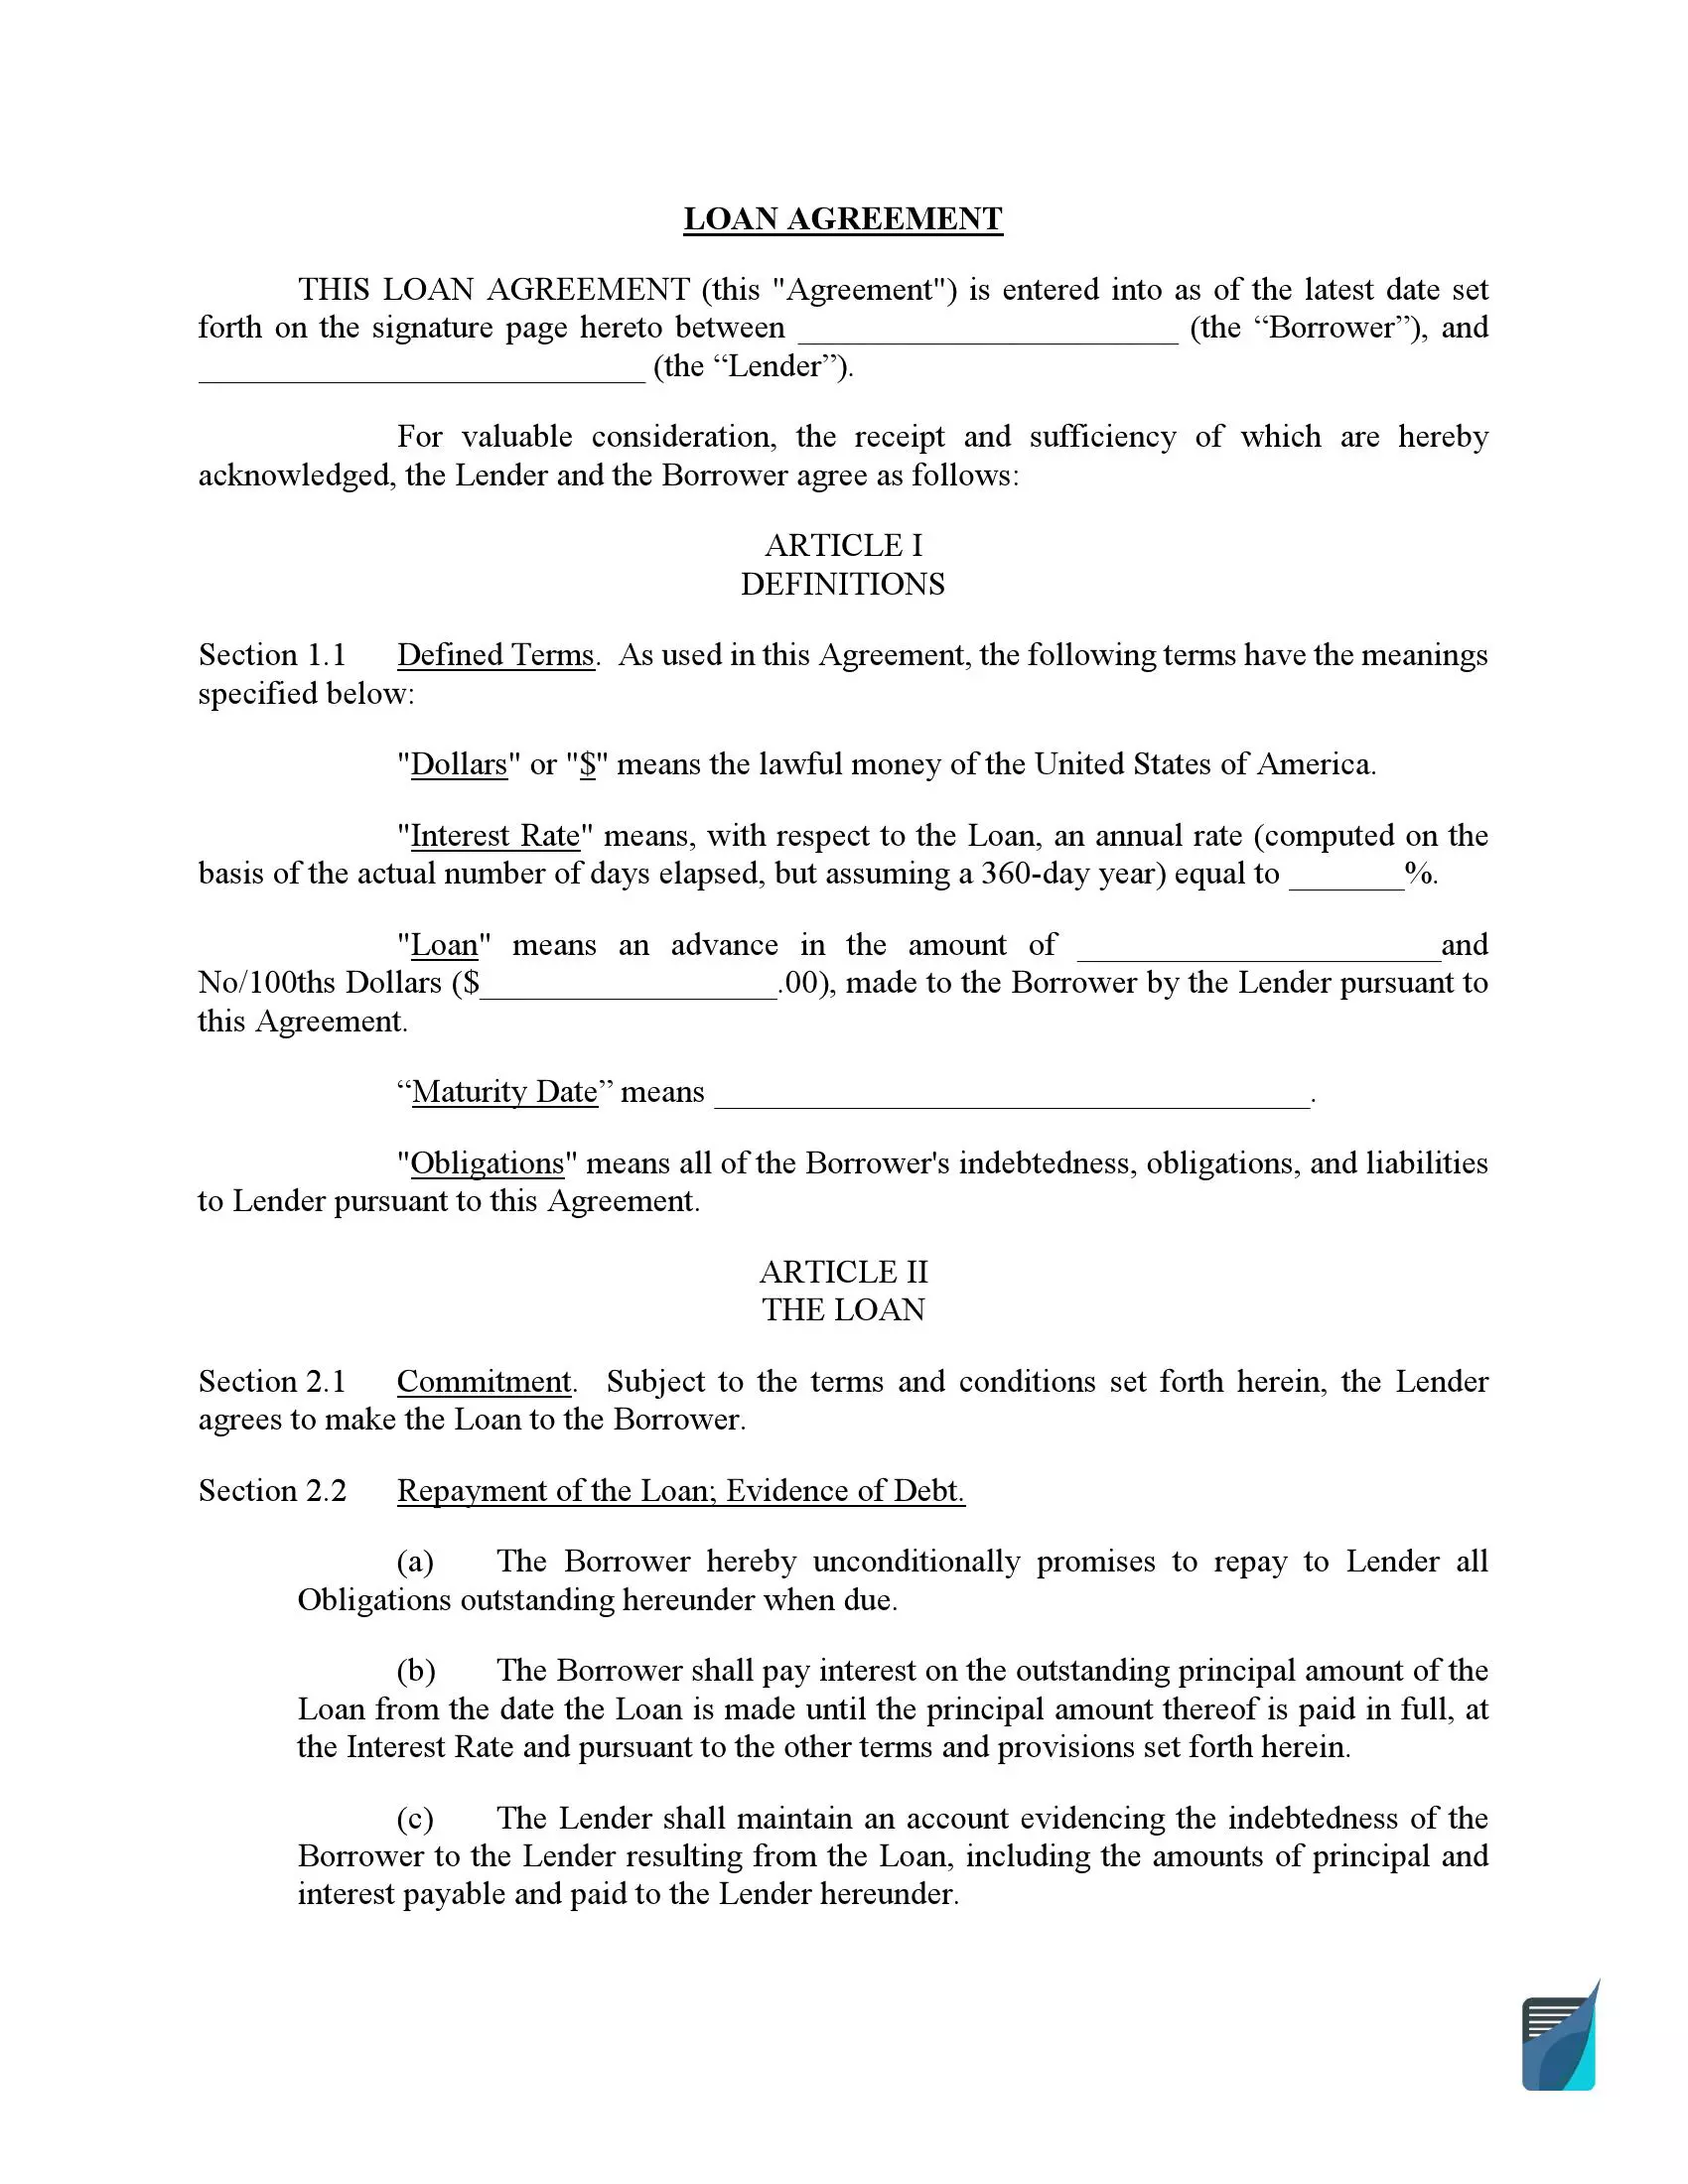
A loan agreement sample shows the blank form filled in with a sample loan's names, amounts and dates, from the parties at the top to the signatures at the end. The table below walks through one filled-in personal loan.
Example only. The names, amounts and dates below are made up to show the format.
| Section | Example entry |
|---|---|
| Date | January 15, 2027 |
| Lender | Maria Lopez, 12 Oak Street, Springfield |
| Borrower | Daniel Kim, 48 Pine Avenue, Springfield |
| Loan amount | $5,000, paid by bank transfer on January 15, 2027 |
| Interest | 4% per year on the unpaid balance, about $211 in total |
| Repayment | 24 monthly payments of $217.12, due on the 1st of each month |
| First payment and maturity date | March 1, 2027; full balance due February 1, 2029 |
| Collateral | None (unsecured loan) |
| Prepayment | The borrower may pay the balance early with no penalty |
| Signatures | Lender and borrower, each with the date of signing |
Sample clause: "Promise to Pay. The Borrower promises to pay the Lender the sum of $5,000 plus interest at 4% per year on the unpaid balance, in 24 monthly payments of $217.12, beginning March 1, 2027."
The sample puts every term on its own line, so either party can check the deal at a glance. The promise to pay clause carries the core of the contract: who pays, how much, at what rate and from what date.
A loan agreement includes the parties, the loan amount, the interest rate and the repayment terms, plus the maturity date, any collateral or co-signer, the default terms and the signatures. No single standard format exists, so lenders arrange these parts in their own order. A complete agreement covers:
The interest clause gives the yearly rate as an exact figure and says whether interest is simple or compound. Simple interest runs on the principal still owed, never on interest already added. Compound interest runs on the principal still owed plus the interest already added. A loan between relatives can carry no interest at all, and the clause then says so.
The repayment clause sets how and when the borrower pays the money back, and the maturity date marks when the whole balance falls due. The agreement names its repayment option:
Periodic payments pay the balance down a little at a time. A lump sum fits a short loan with a clear end date. Payment on demand leaves the timing open until the lender asks.
The default clause says what follows a missed payment: a late fee, collection costs such as attorney's fees, and the lender's right to demand the full balance. Acceleration lets the lender move up the date when the whole balance is due, usually after a missed payment. The governing jurisdiction names whose rules apply if a disagreement between the parties comes up.
The prepayment clause says whether the borrower can pay the balance early and whether early repayment carries a charge. When it carries none, the clause says the borrower can pay back at any time without penalty.
The guarantor clause names a third person who promises to pay if the borrower does not. The co-signer signs the agreement next to the borrower. A separate personal guarantee does the same job in its own document.
A secured loan agreement names collateral, an item the borrower puts up for the loan, and says what happens to it on default; an unsecured loan agreement rests on the borrower's promise to pay alone.
| Section of the agreement | Secured loan agreement | Unsecured loan agreement |
|---|---|---|
| Collateral | Named and described | Left out |
| What happens to the collateral on default | Written out | Left out |
Pick the secured form when the borrower puts up an item for the loan, and the unsecured form when the borrower puts up nothing. The collateral clause describes the item closely enough to tell it apart from any other, such as a car by its make, model and vehicle identification number.
A loan agreement's interest rate stays under the usury cap, the highest rate a lender may charge under the rules that govern the loan, and several statutes below let a rate set in writing go higher than the rate with no written terms. The table lists each rule with its condition and the statute behind it.
| Where | Rate rule | Statute |
|---|---|---|
| Alabama | Unless another provision of law sets otherwise, $6 upon $100 for one year with no written contract, and by written contract not to exceed $8 upon $100 for one year. | Ala. Code 8-8-1 |
| Arizona | For any loan other than medical debt, ten percent a year, unless a different rate is contracted for in writing, in which event any rate of interest may be agreed to. | Ariz. Rev. Stat. § 44-1201 |
| California | 7 percent per annum unless the parties contract in writing for another rate; by written contract, a rate not exceeding 10 percent per annum if the money is for use primarily for personal, family or household purposes. The cap binds lenders other than those the section exempts, among them banks, credit unions, licensed pawnbrokers and loans arranged by a licensed real estate broker and secured by real property. | Cal. Const. art. XV, § 1 |
| Hawaii | By written contract, simple interest not exceeding one per cent per month or twelve per cent a year, for a consumer credit transaction (except a credit card agreement) or a home business loan. | Haw. Rev. Stat. 478-4(a) |
| Kansas | A written note or other instrument may set interest at a rate not to exceed 15% per annum, unless otherwise specifically authorized by law. | K.S.A. 16-207(a) |
| Michigan | $5.00 upon $100.00 for a year, except that the parties may stipulate in writing for any rate not exceeding 7% per annum. | Mich. Comp. Laws § 438.31 |
| Minnesota | No greater sum for the loan of money than $8 on $100 for one year. | Minn. Stat. § 334.01 |
| West Virginia | Except where otherwise specially provided by law, $6 upon $100 for a year on any contract other than a contract in writing; parties may contract in writing for a rate not to exceed $8 upon $100 for a year, including points (money or other consideration the lender receives for making the loan) expressed as a percentage of the loan divided by the number of years of the loan contract. | W. Va. Code § 47-6-5 |
The table covers only these statutes. For a loan governed anywhere else, read that place's own usury statute before writing a rate into the agreement.
A simple loan agreement comes together by gathering both parties' details and the loan terms, entering them section by section, then having the borrower and the lender sign and each keep a copy. Gather these details first:
Then fill in the agreement in this order:
A loan agreement fits any loan where the lender expects the money back on set terms, from a cash loan between friends to a business loan or a car sale paid off over time. Common situations:
The loan agreement is the fullest of the debt documents, and a shorter document sometimes does the job. An IOU suits a small, informal debt between people who trust each other. A payment agreement suits a debt that already exists and needs a plan to pay it back.
A written loan agreement fixes the amount, the cost of borrowing and the repayment dates before any money moves, so neither side can later remember the deal differently. Its main benefits:
Some statutes tie the interest itself to the writing. Under La. Rev. Stat. § 9:3500, the conventional interest in Louisiana "must be fixed in writing; testimonial proof of it is not admitted in any case." Under Ariz. Rev. Stat. § 44-1201, any rate of interest may be agreed to only when a different rate is contracted for in writing.
A loan agreement sets out the duties of both parties, while a promissory note holds the borrower's promise to pay with fewer terms and an IOU names only the debt.
| Document | What the document sets out |
|---|---|
| Loan agreement | Amount, interest, schedule, collateral, default terms, duties of both parties |
| Promissory note | The borrower's promise to pay, with fewer terms |
| IOU | The debt itself |
A promissory note can be secured or unsecured. When it is secured, the collateral is often set out in a separate document, such as a security agreement, a mortgage or a deed of trust.
An IOU names the debt but leaves out how and when it is paid back. For a large sum, or between people who do not know each other well, the loan agreement sets out the most detail.
A signed loan agreement works best when each party keeps a signed copy, the borrower keeps proof of every payment, and both parties put any change to the terms in writing. Good proof of payments settles any question about the balance later.
When the last payment arrives, the lender can give the borrower a signed note confirming the loan is paid in full. A payoff request letter asks the lender for the exact balance before the final payment.
Yes, a lender and a borrower can write their own loan agreement, and a template gives them a ready structure for the amount, interest, repayment schedule, default terms and signatures. The steps in How to Write a Simple Loan Agreement cover each section.
A simple loan agreement follows a plain top to bottom format: a title, the date, the parties, the promise to pay, then the terms and the signatures. Each term sits under its own heading, so the format reads in the same order as the deal: the money, the cost, the payments, the default terms and the governing jurisdiction. The sample above shows this layout filled in.
A cash loan agreement is a loan agreement for money handed over in cash instead of by transfer or check. The agreement names the date and place of the handover, and the borrower's signature on it confirms the money was received. Cash leaves no bank trail, so a receipt for every repayment matters even more.
Write it the same way as any other: name both relatives, the amount, any interest, the repayment schedule and what happens if a payment is missed. Putting a family loan in writing keeps the terms clear for both relatives. If the loan carries little or no interest, ask a tax adviser how it is treated. Our family loan agreement is set up for this case.
An agreement letter for a loan is a short letter in which both parties confirm the amount lent, the repayment terms and their signatures. Write it in plain sentences, addressed from the borrower to the lender, and have both parties sign it. A full agreement covers the same points in separate sections and adds terms for interest, late payment and default.
A demand loan agreement lets the lender ask for full repayment at any moment instead of on a fixed schedule. For the lender, it means the money can come back whenever they need it for another purpose. For the borrower, it usually means no charge for repaying early. Demand loans often suit new businesses and loans between relatives.
Interest is the price the borrower pays for using the lender's money, worked out as a share of the loan amount over a set period, usually a year. Simple interest is charged on the principal still owed, never on interest already added. Compound interest is charged on the principal still owed plus the interest already added.
Example: a loan of $100 at 3% per year.
General information, not legal or tax advice.
