
Updated:
Get Form Now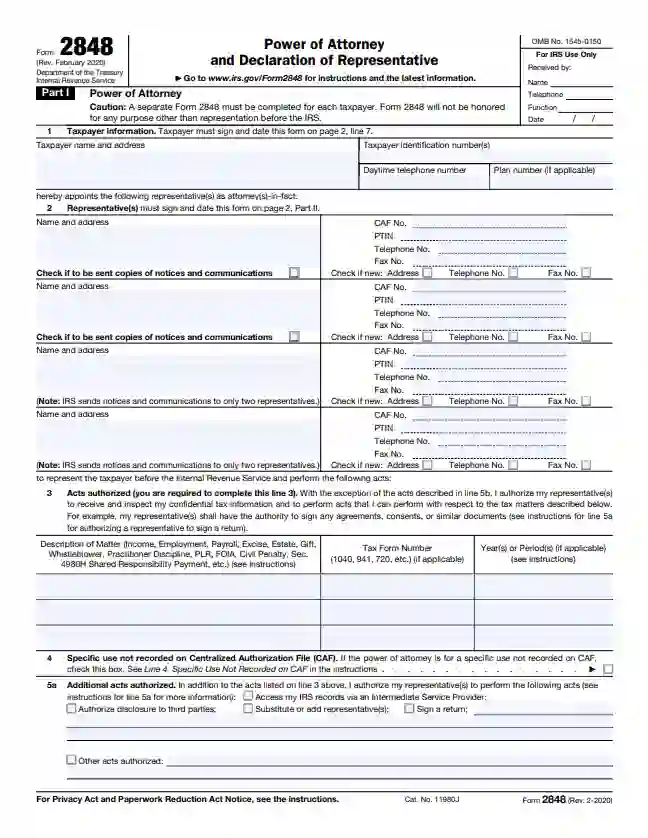
IRS Form 2848 is the federal power of attorney for tax matters. Under the Instructions for Form 2848, it lets an eligible representative act for you before the IRS. This guide covers each line, the signatures and the filing options.
Key facts
IRS Form 2848, Power of Attorney and Declaration of Representative, authorizes a named individual to represent a taxpayer before the Internal Revenue Service and to inspect and receive the taxpayer's confidential tax information. The form has two parts: Part I is the power of attorney the taxpayer grants, and Part II is the declaration each representative signs to accept it.
The form fits any IRS matter where you want a professional to speak for you. Common examples are an audit of your federal tax return, a collection notice, a penalty, or setting up an installment agreement on old taxes.
Form 2848 lets the IRS deal with your representative as it would deal with you, within the matters and years you list. It does not move your tax liability: you remain responsible for your return, for any payment due and for any incorrect information filed on your behalf.
The authority has limits. According to the Instructions for Form 2848, a representative cannot endorse or cash a government check issued for a federal tax liability, and the power to sign your tax return is granted only in limited situations.
| Document Name | IRS Power of Attorney Form |
| Official Title | Form 2848, Power of Attorney and Declaration of Representative |
| Other Names | Tax Power of Attorney, IRS POA, Federal POA |
| Issued By | Internal Revenue Service (IRS) |
| # of Fillable Fields | 93 |
| Available Formats | Adobe PDF |
Form 2848 accepts only individuals eligible to practice before the IRS, so it is not a blanket authorization like a general power of attorney. Part II of the form lists the eligible designations in items (a) to (r), as the IRS instructions explain. A friend or business colleague without one of those designations cannot be named.
The designations most taxpayers use are these:
Each representative proves the designation in Part II by entering a license, bar, certification or enrollment number. The professional supplies that information, so you do not have to look it up yourself.
An unenrolled return preparer has limited representation rights under the Instructions for Form 2848: the preparer may represent you only during an examination of the tax period covered by a return the preparer prepared and signed, and only before revenue agents, customer service representatives and similar IRS employees, including the Taxpayer Advocate Service. Under the Instructions for Form 2848, the preparer cannot represent you before appeals officers, revenue officers or IRS Chief Counsel attorneys, and cannot sign closing agreements, waivers, refund claims or any other document for you.
The Instructions for Form 2848 require the preparer to hold a valid and active PTIN. For returns prepared and signed after December 31, 2015, the Instructions for Form 2848 also require an Annual Filing Season Program Record of Completion for the year the return was prepared and for the year or years of the representation. A preparer who does not meet those requirements can still see your tax information through Form 8821, but that form does not authorize representation.
Line 3 of Form 2848 defines exactly what your representative may handle: the description of the matter, the tax form number and the years or periods. The IRS instructions make the power of attorney valid only when line 3 carries those three entries, where they apply.
Representation covers only the years or periods listed on line 3, so a vague entry leaves your representative without authority for the matter at hand. Ask your professional which forms and years they will work on before you fill in this line.
Example line 3 entries: Description of Matter "Income", Tax Form Number "1040", Year(s) or Period(s) "2022 thru 2024". A second row could read "Employment", "941", "2024".
A range of consecutive years can be written with "through", "thru" or a hyphen. Under the Instructions for Form 2848, the IRS does not record on its Centralized Authorization File (CAF) future years that exceed 3 years from December 31 of the year it receives the form.
Some matters have no form number or year, such as a penalty not tied to a return or a ruling request. For those, line 3 describes the matter specifically and says "Not Applicable" in the unused column, as the IRS instructions direct.
Form 2848 follows the layout of other IRS forms: seven numbered lines in Part I and a declaration in Part II, each described line by line in the IRS instructions. Work through the lines in order and check every entry against your records before you sign.


Form 2848 needs two sets of signatures: the taxpayer's on line 7 and each representative's in Part II. The IRS instructions set the order, the form of signature and the time between them.
For a taxpayer under 18 who cannot sign, the Instructions for Form 2848 let a parent or court-appointed guardian sign on the taxpayer's behalf.
Form 2848 goes to the IRS online, by fax or by mail, as the IRS instructions explain. A form with line 4 checked goes instead to the IRS office handling that specific matter.
A representative can also file through the IRS Tax Pro Account, where most requests are recorded to the CAF immediately.
The fax numbers and addresses below come from the Where To File Chart in the Instructions for Form 2848. The IRS notes that these numbers may change without notice, so confirm them on IRS.gov/Form2848 before you send.
| If you live in | Fax number | Mailing address |
|---|---|---|
| Alabama, Arkansas, Connecticut, Delaware, District of Columbia, Florida, Georgia, Illinois, Indiana, Kentucky, Louisiana, Maine, Maryland, Massachusetts, Michigan, Mississippi, New Hampshire, New Jersey, New York, North Carolina, Ohio, Pennsylvania, Rhode Island, South Carolina, Tennessee, Vermont, Virginia, West Virginia | 855-214-7519 | Internal Revenue Service, 5333 Getwell Road, Stop 8423, Memphis, TN 38118 |
| Alaska, Arizona, California, Colorado, Hawaii, Idaho, Iowa, Kansas, Minnesota, Missouri, Montana, Nebraska, Nevada, New Mexico, North Dakota, Oklahoma, Oregon, South Dakota, Texas, Utah, Washington, Wisconsin, Wyoming | 855-214-7522 | Internal Revenue Service, 1973 Rulon White Blvd., MS 6737, Ogden, UT 84201 |
| APO and FPO addresses, American Samoa, Northern Mariana Islands, Guam, U.S. Virgin Islands, Puerto Rico, a foreign country or elsewhere outside the United States | 855-772-3156, or 304-707-9785 from outside the United States | Internal Revenue Service, International CAF Team, 2970 Market Street, MS: 4-H14.123, Philadelphia, PA 19104 |
Form 2848 is rejected when a required entry is missing or vague, and one mistake can send it back. Each item below breaks a requirement in the IRS instructions:
Read each line again before you sign. Check that every name and number matches your records, and keep a signed copy.
A Form 2848 authorization ends when you revoke it or when the representative withdraws, and a new Form 2848 for the same matter generally replaces the old one on the CAF. To revoke without naming anyone new, follow the steps the IRS instructions give:
Without a copy, the IRS instructions call for a signed statement of revocation that lists the matters, the years or periods, and the name and address of each representative.
Of the IRS forms listed here, Form 2848 is the only one that authorizes representation before the IRS; a general power of attorney can also do so when it meets the IRS requirements and a completed Form 2848 is attached, as the Instructions for Form 2848 explain. The other forms below share information or report a role, and some taxpayers use them instead of, or alongside, the IRS POA.
Form 8821, Tax Information Authorization, lets a person or organization inspect and receive your confidential tax information without representing you before the IRS. Tax professionals ask for it when they need to see your notices and records but will not argue your case. Filing a new Form 2848 does not revoke a Form 8821 already in effect.
Form 56, Notice Concerning Fiduciary Relationship, tells the IRS that a fiduciary relationship exists or has ended. A trustee, executor, administrator, receiver or guardian uses it, and the fiduciary acts as the taxpayer rather than as a representative. The fiduciary files it at the start of the relationship and again at the end.
A general power of attorney covers financial matters broadly, and the IRS accepts it for tax representation when it meets the IRS requirements for a power of attorney. Under the Instructions for Form 2848, such a substitute power of attorney cannot be recorded on the CAF unless a completed Form 2848 is attached. The IRS POA is the simpler choice when your representative needs access to federal tax matters.
More document types are listed on the power of attorney main page.
The IRS publishes Form 2848 as a fillable PDF, so you can type every entry on a computer before you print it. The signature on line 7 still has to be handwritten if you mail or fax the form.
A CAF number is the nine-digit identification number the IRS assigns to a representative in its Centralized Authorization File. It is not an SSN, EIN or PTIN. A representative without one enters "None" on line 2, and the IRS issues the number directly to that representative.
The Instructions for Form 2848 describe no notary or witness step. The form is complete with the taxpayer's signature on line 7 and each representative's signed declaration in Part II.
A representative can sign your income tax return only in the limited cases the Instructions for Form 2848 name: disease or injury, continuous absence from the United States for at least 60 days before the filing due date, or specific permission from the IRS for other good cause. The authority is added by checking "Sign a return" on line 5a and writing the required statement.
A new Form 2848 recorded on the CAF generally revokes an earlier power of attorney for the same matter, according to the IRS instructions. To keep the earlier one, check the box on line 6 and attach a copy of it.
Each spouse files a separate Form 2848, even for a joint return. The IRS instructions require each spouse to execute an individual power of attorney to name a representative.
General information, not legal or tax advice.
