Updated:
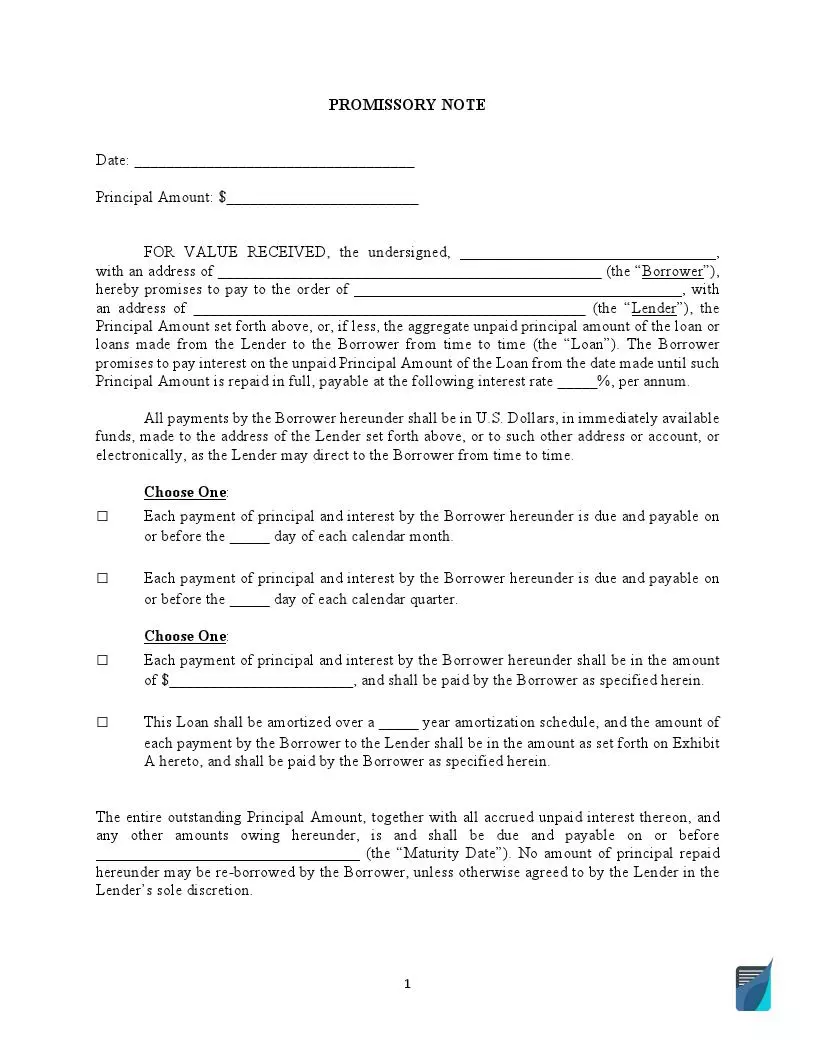
A promissory note is a borrower's signed promise to repay a loan. The note records the amount borrowed, the interest, the payment schedule and the outcome of a default. The borrower signs it for the lender, especially on personal loans between family members or friends.
Key facts
A promissory note sets out the terms of the debt. This page covers each part of the note, a worked payment example, the default and maximum interest rates the states set, and how to fill out and sign the form.
A promissory note template holds seven parts: the parties, any co-signer, the principal and interest rate, the payment plan, any collateral, the default clause and the signatures. Agree on each item with the other party before the note is written.
A personal loan promissory note puts a loan between people in writing, such as money lent to a family member, a friend or a colleague. The note is the lender's proof of the debt and the borrower's record of what was agreed. Writing the terms down before the money moves keeps both sides from remembering them differently later.
The same form serves several kinds of loans:
A note for a loan to a friend uses the same parts as any other note: names, amount, interest, schedule and signatures. An interest-free loan says so in the note, because some states read a loan with no rate as a loan at the legal rate. Under N.D.C.C. § 47-14-03, a loan of money is presumed to carry interest unless it is expressly stipulated otherwise in writing when it is made. Under Tex. Fin. Code § 302.002, if a creditor has not agreed to charge any interest, the creditor may charge legal interest of six percent a year beginning on the 30th day after the amount is due.
A promissory note sample shows three payment figures worked out before the note is signed: the total interest, the final total payment and each installment. The calculation needs the principal, the repayment period and the interest rate. The example below uses made-up numbers and simple interest.
Example: A borrower takes a $6,000 loan at a 10% annual interest rate for six months, repaid in quarterly installments. These are sample figures only.
The final total payment is the principal plus the total interest: 6,000 + 300 = 6,300.
Each installment is the final total payment divided by the number of installments. Six months paid quarterly gives two installments (6/3 = 2), so each one is 6,300 / 2 = 3,150, paid every three months. Paid monthly instead, the loan takes six installments of 1,050 each.
An amortized loan spreads each payment between interest and principal on a schedule, and an online amortization calculator prepares that schedule for attachment to the note.
A promissory note with a payment schedule names one of five repayment structures, chosen by the size of the loan and the time the borrower needs. The note states the chosen structure plainly.
Payments usually go to interest first and then to principal, unless the note says otherwise.
A prepayment clause says whether the borrower may pay early and whether a fee applies. Some states set the rule for certain loans. Under Wis. Stat. § 138.05, a loan whose rate exceeds $10 per $100 for one year on the declining principal balance may be prepaid at any time in whole or in part. Under Kan. Stat. Ann. § 16-207, no prepayment penalty applies to a home loan note secured by a real estate mortgage if it is prepaid more than six months after the note is signed.
A late payment clause sets the late fee and the point of default. A late fee is usually a flat amount or a share of the payment, and the clause also says how late a payment can be before the loan is in default. In the District of Columbia, a late charge applies only if the delinquency has continued for at least 10 calendar days, and it may not exceed 5% of the late installment of principal and interest (D.C. Code § 28-3309). The lender can send a demand letter about a missed payment.
The default clause decides what the lender can do next. With a secured note, the lender may claim the collateral as the note allows, which often means going to court first. With an unsecured note, the lender can sue for repayment, and small claims court may fit smaller amounts.
A promissory note is secured when it names collateral, such as a house or a car, that the lender may claim if the borrower stops paying. An unsecured note names no collateral, so the lender relies on the borrower's promise alone.
A secured promissory note describes the collateral pledged against non-payment, and its terms usually let the lender claim that property on default.
An unsecured promissory note names no collateral. If the borrower stops paying, the lender usually sues to collect. In a bankruptcy, the lender typically has no priority over other unsecured creditors.
A promissory note is a short promise to repay, while a loan agreement is a longer contract with more terms. Both record the amount, the interest and the repayment plan, but the loan agreement goes further into each party's duties.
A promissory note is a negotiable instrument only if it meets set conditions, and negotiability decides how easily the lender can sell or transfer it. Under W. Va. Code § 46-3-104(a), a negotiable instrument is an unconditional promise to pay a fixed amount of money, with or without interest, if it meets three conditions, except as subsections (c) and (d) provide:
Mississippi (Miss. Code Ann. § 75-3-104(a)), Oklahoma (12A O.S. § 3-104(a)), Rhode Island (R.I. Gen. Laws § 6A-3-104(a)) and Wyoming (Wyo. Stat. § 34.1-3-104(a)) use the same definition: a note is negotiable there only if it meets the same three conditions, except as subsections (c) and (d) provide. This is why a note meant to be transferable usually says "payable to order" or "payable to bearer."
A promissory note's interest rate meets two kinds of state rate: a default rate that applies when the note names none, and in some states a cap on the rate the parties may agree in writing. The table labels each rate as a default rate or a cap and gives the condition and the section of law behind it. A row marked default rate only sets no cap on an agreed rate in the cited section. Rates tied to a Federal Reserve or market figure change over time.
North Carolina and Tennessee are not in the table because the engine's sources hold no general rate for them. A lender who charges more than the limit can lose the interest or more, so check the state page and the cited section before writing a rate into the note.
| State | Default rate (no rate in the note) or cap on an agreed rate | Law |
| Alabama | $6 upon $100 for one year (6%) is the maximum, except by written contract | Ala. Code § 8-8-1 |
| Alaska | Default rate: 10.5% a year on money after it is due, except as subsection (b) of the section provides | Alaska Stat. § 45.45.010 |
| Arizona | Default rate: 10% a year unless a different rate is contracted for in writing; with a written contract, any rate may be agreed | Ariz. Rev. Stat. § 44-1201 |
| Arkansas | 6% a year when the contract specifies no rate; a written agreement may set interest up to the rate, if any, in Arkansas Constitution Amendment 89 | Ark. Code Ann. § 4-57-101(d); Ark. Code Ann. § 4-57-104 |
| California | 7% a year, unless the parties contract in writing for another rate within the limits the section sets | Cal. Const. art. XV, § 1 |
| Colorado | 8% a year, compounded annually, if there is no agreement or provision of law for a different rate; a written note may set a higher rate, up to 45% a year | Colo. Rev. Stat. § 5-12-101; Colo. Rev. Stat. § 5-12-103(1) |
| Connecticut | Default rate only: 8% a year in the absence of any agreement to the contrary | Conn. Gen. Stat. § 37-1 |
| Delaware | Where there is no expressed contract rate, 5% over the Federal Reserve discount rate including any surcharge; a written agreement may not exceed that same rate | 6 Del. C. § 2301 |
| District of Columbia | 6% a year in the absence of an expressed contract; a written instrument may set up to 24% a year | D.C. Code § 28-3302; D.C. Code § 28-3301 |
| Florida | More than the equivalent of 18% a year simple interest is usury, except where other law allows | Fla. Stat. § 687.03 |
| Georgia | 7% a year simple interest where no written contract sets the rate; where the principal is $3,000 or less, no more than 16% a year simple interest | O.C.G.A. § 7-4-2; O.C.G.A. § 7-4-2(a)(2) |
| Hawaii | 10% a year when no express written contract fixes a different rate; outside consumer credit, home business loans and credit card agreements, a written contract may set any rate not otherwise prohibited by law | Haw. Rev. Stat. § 478-2; Haw. Rev. Stat. § 478-4 |
| Idaho | Default rate only: 12% a year when no written contract fixes a different rate | Idaho Code § 28-22-104 |
| Illinois | In written contracts, up to 9% a year, except as Section 4.05 provides | 815 ILCS 205/4 |
| Indiana | Default rate only: 8% a year when the parties do not agree on the rate | IC 24-4.6-1-102 |
| Iowa | 5% a year (five cents on the hundred) as the legal rate; where the subsection applies, the superintendent of banking sets the maximum lawful rate each month | Iowa Code 535.2(1); Iowa Code § 535.2(3)(a)(2) |
| Kansas | 10% a year on money after it is due when no other rate is agreed, except as subsection (b) provides; a written note may set up to 15% a year unless other law authorizes more | K.S.A. § 16-201(a); Kan. Stat. Ann. § 16-207 |
| Kentucky | 8% a year, unless the parties agree in writing to more; where the original principal is $15,000 or less, at most 4% over the Federal Reserve discount rate on 90-day commercial paper or 19%, whichever is less | Ky. Rev. Stat. § 360.010 |
| Louisiana | Conventional interest of up to 12% a year, only if fixed in writing | La. Rev. Stat. § 9:3500 |
| Maine | 6% a year on a loan by a financial institution, in the absence of a written agreement setting a different rate; 18% a year on a consumer loan when the amount financed exceeds $8,000 | Me. Rev. Stat. tit. 9-B, § 432; Me. Rev. Stat. tit. 9-A, § 2-401 |
| Maryland | 6% a year simple interest, except as otherwise provided by law; 8% a year if a written agreement signed by the borrower sets out the rate | Md. Code, Com. Law § 12-102; Md. Code, Com. Law § 12-103 |
| Massachusetts | 6% a year if there is no agreement or provision of law for a different rate; knowingly charging interest and expenses above 20% a year is an offense, except as the law allows | Mass. Gen. Laws ch. 107, § 3; Mass. Gen. Laws ch. 271, § 49 |
| Michigan | 5% a year, unless the parties agree in writing to a rate of up to 7% a year | Mich. Comp. Laws § 438.31 |
| Minnesota | No more than $8 on $100 for one year (8%) for the loan or forbearance of money, where the section applies | Minn. Stat. § 334.01 |
| Mississippi | 8% a year legal rate on notes, accounts and contracts; written contracts may provide for a finance charge as the section or other law allows | Miss. Code Ann. § 75-17-1 |
| Missouri | Up to 10% a year, only if the parties agree in writing | Mo. Rev. Stat. § 408.030 |
| Montana | Default rate: 10% a year unless a written contract fixes a different rate; cap: a written agreement may set up to the greater of 15% or 6 percentage points above the published prime rate | Mont. Code Ann. § 31-1-106(1); Mont. Code Ann. § 31-1-107 |
| Nebraska | Up to 16% a year on the unpaid principal, except as section 45-101.04 provides | Neb. Rev. Stat. § 45-101.03 |
| Nevada | Any rate the parties specify in writing, except as subsection 2 provides; when no written contract fixes a rate, the prime rate at the largest Nevada bank plus 2% | Nev. Rev. Stat. § 99.050; Nev. Rev. Stat. § 99.040 |
| New Hampshire | Default rate: 10% a year in business transactions, unless otherwise agreed in writing | N.H. Rev. Stat. Ann. § 336:1 |
| New Jersey | $6 per $100 for a year (6%), or $16 per $100 (16%) when a written contract specifies the rate, except as otherwise provided by law | N.J.S.A. § 31:1-1(a) |
| New Mexico | Not more than 15% a year in the cases the section lists, in the absence of a written contract fixing a different rate | N.M. Stat. Ann. § 56-8-3 |
| New York | 16% a year maximum; charging above 25% a year when not authorized by law is criminal usury in the second degree | N.Y. Banking Law § 14-a; N.Y. Penal Law § 190.40 |
| North Dakota | 6% a year unless a different rate, not above the § 47-14-09 limit, is contracted for in writing; that limit is 5.5% a year above the current cost of money | N.D.C.C. § 47-14-05; N.D.C.C. § 47-14-09 |
| Ohio | Up to 8% a year in a written note, except as division (B) of the section authorizes | Ohio Rev. Code Ann. § 1343.01 |
| Oklahoma | Up to 10% a year on a consumer loan other than a supervised loan | Okla. Stat. tit. 14A, § 3-201 |
| Oregon | 9% a year if the parties have not agreed to a rate; a loan of $50,000 or less, with the exceptions the section lists, may not exceed the greater of 12% or 5% over the discount rate on 90-day commercial paper | Or. Rev. Stat. § 82.010; Or. Rev. Stat. § 82.010(3)(b) |
| Pennsylvania | 6% a year on loans of $50,000 or less where no express contract sets a lower rate, except as Article III of the act provides; a note "with interest" that names no rate means 6% a year | 41 P.S. § 201; 41 P.S. § 202 |
| Rhode Island | 12% a year in business transactions unless a different rate is expressly stipulated; no lender other than a licensed pawnbroker may exceed the greater of 21% or the alternate rate in subsection (b) | R.I. Gen. Laws 6-26-1; R.I. Gen. Laws § 6-26-2 |
| South Carolina | 6% a year, except on written contracts that set a rate by express agreement; 8.75% legal interest on accounts stated and sums that draw interest by law | S.C. Code Ann. § 37-10-106; S.C. Code Ann. § 34-31-20(A) |
| South Dakota | No maximum rate if the parties set the rate by written agreement, unless the code sets a maximum elsewhere | S.D. Codified Laws § 54-3-1.1 |
| Texas | 10% a year maximum, except as otherwise provided by law; if no interest was agreed, 6% a year legal interest from the 30th day after the amount is due | Tex. Fin. Code § 302.001; Tex. Fin. Code § 302.002 |
| Utah | Default rate only: 10% a year unless the parties expressly specify a different rate in their contract | Utah Code § 15-1-1 |
| Vermont | 12% a year computed by the actuarial method, except as specifically provided by law | 9 V.S.A. § 41a |
| Virginia | 6% a year legal rate; a loan contract may not exceed 12% a year, except as otherwise permitted by law | Va. Code Ann. § 6.2-301(A); Va. Code Ann. § 6.2-303 |
| Washington | The higher of 12% a year or four points above the average 26-week Treasury bill yield, except as subsection (4) provides | Wash. Rev. Code § 19.52.020 |
| West Virginia | Up to $8 upon $100 for a year (8%), only if the parties contract in writing | W. Va. Code § 47-6-5 |
| Wisconsin | $12 upon $100 for one year on the declining principal balance, for the loans the section covers; a contracted rate is clearly expressed in writing | Wis. Stat. § 138.05; Wis. Stat. § 138.04 |
| Wyoming | Default rate only: 7% a year if there is no agreement or provision of law for a different rate | Wyo. Stat. Ann. § 40-14-106 |
A legal promissory note comes from five steps: agreeing on the terms, checking the other party, settling any collateral and co-signer, writing and signing the note, and releasing the borrower once the loan is repaid.

The terms come first, before any writing, so each party accepts the same deal. The parties agree on:

A background check lowers the risk on both sides of the loan.

The collateral and the co-signer are fixed before the note is written.

The note is written and signed at one meeting, and the lender hands over the money after signing. The next section walks through each field of the template.

A loan release form closes the note once it is paid. The lender signs it after the borrower has paid on time and as agreed, and it records that the borrower owes nothing further under the note.
The promissory note template fills out in six steps, from the basic details to the signatures. The sample figures below match the payment example above; use the figures you and the other party agreed on.
Example entries: November 11, 2020; $6,000 (six thousand U.S. dollars); lender James Fuller, 22 Boulevard Street, Anytown, ST 00000; interest rate 10%.

The payment date field sets when each installment falls due, monthly or quarterly.
A monthly due date in the last week of the month, such as the 25th, is common. A quarterly due date can be written as a day count, such as the 85th day of each quarter, or as "last day" or "second to last day" of each quarter. The quarters run January to March, April to June, July to September and October to December.

The payment plan field chooses equal installments or amortized payments.
In the sample loan, the installment is $1,050 for monthly payments or $3,150 for quarterly payments.

The security field marks whether the note names collateral.

The governing law field names the state whose law applies to the note, usually the state where the lender lives.

The signature block binds every party who signs it.

These answers cover the questions people ask most about promissory notes. The rules differ by state, so treat the answers as general information and check the state page for details.
A promissory note can be invalid or hard to enforce when it is written carelessly or breaks a state rule. Common problems include:
A promissory note is also a contract. The parties need to be adults of sound mind, and the purpose of the loan must be lawful.
Often, yes: many lenders can sell or transfer a note. A lender who wants cash sooner can sell it at a discount to a note-buying company, and notes also pass between family members to offset another loan. A note meant to be transferable usually says "payable to order" or "payable to bearer," which is one of the negotiability conditions described above.
Yes, a note can have more than one lender or borrower. The note then lists the names and identifying details of all of them, and each one signs.
A demand promissory note is one where payment is due when the lender asks for it. It has no maturity date. Many lenders give the borrower reasonable notice before asking for payment, and the note may set a notice period.
A simple personal loan agreement can be a promissory note that names both parties, the amount, the interest rate, the payment schedule and the default terms, signed by the borrower. A longer loan agreement fits when the parties want more terms, such as each side's duties in detail.
A master promissory note (MPN) is the agreement a student signs with the U.S. Department of Education before taking a federal student loan. By signing it, the student accepts the terms of the loans it covers.
A debt settlement agreement resolves an outstanding debt between a debtor and a creditor. When the debtor is unable to pay the full amount, the parties agree on a smaller sum, which lets the debtor clear the debt and the creditor limit the loss without a court order.
General information, not legal or tax advice.