
A Colorado promissory note is a written promise to repay a loan. The borrower signs it, and the lender keeps it as proof of the debt. It records the sum lent, the cost of borrowing, and when payments are due. Colorado sets the rate at 8% a year, compounded annually, when the parties have not agreed on one.[1.1] A note can set a higher rate, up to 45% a year.[1.3] This Colorado promissory note template lets you fill out the form online or download it as a PDF.
Last Updated: October 2026. This guide is reviewed and updated regularly to reflect current Colorado law. If you notice an error or outdated information, please contact us.
Build Your Document
Answer a few simple questions to make your document in minutes
Save and Print
Save progress and finish on any device, download and print anytime
Sign and Use
Your valid, lawyer-approved document is ready
A Colorado promissory note carries 8% interest a year when the parties have not agreed on a rate and no other law sets one.[1.1] The note itself can set a higher rate, but not above 45% a year.[1.3] Knowingly charging above an annual percentage rate of 45% is criminal usury, a class 6 felony.[2] The parts below explain each rule.
Some notes name no rate at all. If the parties have no agreement on the rate and no other provision of law sets one, interest on money is 8% a year, compounded annually.[1.1] Compounded annually means each year's interest is added to the balance. The next year's interest is then figured on the new total.
Example. Anna Baker lends Ben Carter $5,000, and the note names no rate. With no payments made, year one adds $400, so the balance is $5,400. Year two adds $432, so the balance is $5,832.
Colorado lets the parties to a promissory note agree on a rate higher than 8% a year. The ceiling is 45% a year.[1.3] Colo. Rev. Stat. § 5-12-103 puts it this way:
The parties to any bond, bill, promissory note, or other instrument of writing may stipulate therein for the payment of a greater or higher rate of interest than eight percent per annum, but not exceeding forty-five percent per annum
In plain words, the note can name a rate above 8%, as long as it does not go over 45% a year.[1.2] A rate such as 30% a year is below that ceiling.
The same statute also defines the word interest, and the definition is broad. It reads:
The sum of all charges payable directly or indirectly by a debtor and imposed directly or indirectly by a lender as an incident to or as a condition of the extension of credit to the debtor, whether paid or payable by the debtor, the lender, or any other person on behalf of the debtor to the lender or to a third party
In plain words, the statute counts every charge the lender imposes as part of the loan, whether it goes to the lender or to a third party.[1.2] The stated rate is only part of the picture.
Colorado treats a very high finance charge as a crime. A person who knowingly charges, takes, or receives a loan finance charge above an annual percentage rate of 45% commits criminal usury. It is a class 6 felony.[2]
Check the full cost of the loan before you sign. Every charge the lender imposes as a condition of the loan counts as interest,[1.2] and a knowing charge above 45% a year is criminal usury.[2]
A separate statute covers commercial credit plans. Under § 5-12-107, a creditor may charge and collect periodic interest on the outstanding unpaid indebtedness at a periodic percentage rate or rates not exceeding 45% a year.[1.4]
| Document Name | Colorado Promissory Note Form |
| Other Name | CO Promissory Note |
| Max. Rate | 8% a year if the note names no rate, compounded annually[1.1] Up to 45% a year if the note sets a higher rate[1.3] |
| Relevant Laws | Colorado Revised Statutes, §§ 5-12-101, 5-12-103 and 5-12-107 Colorado Revised Statutes, § 18-15-104 |
| Avg. Time to Fill Out | 10 minutes |
| # of Fillable Fields | 28 |
| Available Formats | Adobe PDF |
Popular Local Promissory Note Forms
Businesses and individuals frequently require promissory notes to lend to or borrow money from other individuals and companies and avoid lending institutions. Below are some of the most popular regional promissory notes searched by the users of this site.
This fillable PDF has three form pages and 28 fillable fields. It covers the sum lent, the parties, the cost of borrowing, the repayment schedule, the day the loan ends, security for the loan, and two signature blocks. You can complete it on screen or print it and write by hand.
Each answer goes into its own field, so the finished note reads as one clear record of the loan. Most people complete the form in about ten minutes.
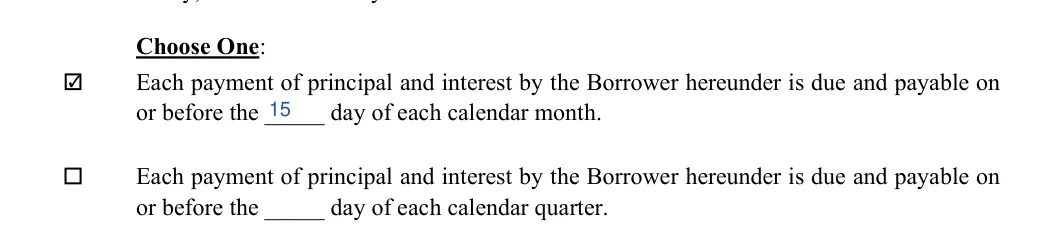
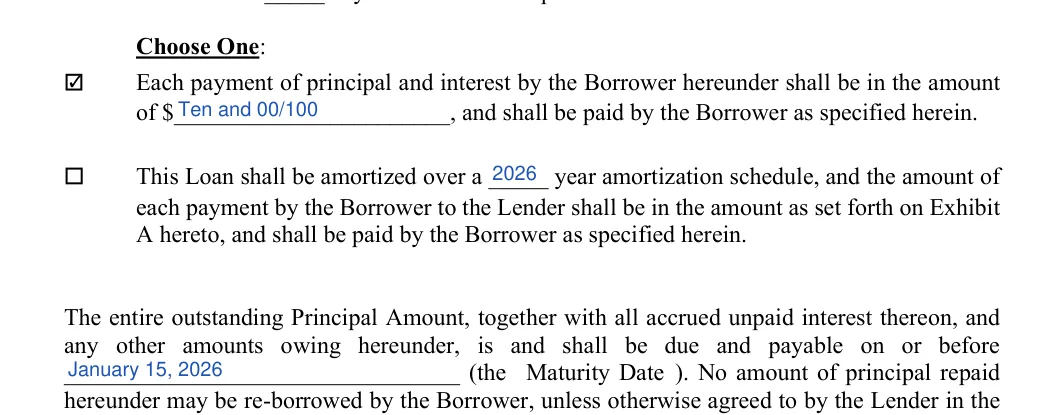
The form asks two questions about payments. The first is how often payments are made, either monthly or quarterly. The second is what each installment looks like. A fixed payment is the same amount every period, such as $250 a month. An amortization schedule spreads the loan over a set number of years, and each installment is listed on Exhibit A.
Whichever plan you choose, write the maturity date on the form. That is the day when anything still unpaid is due in full.
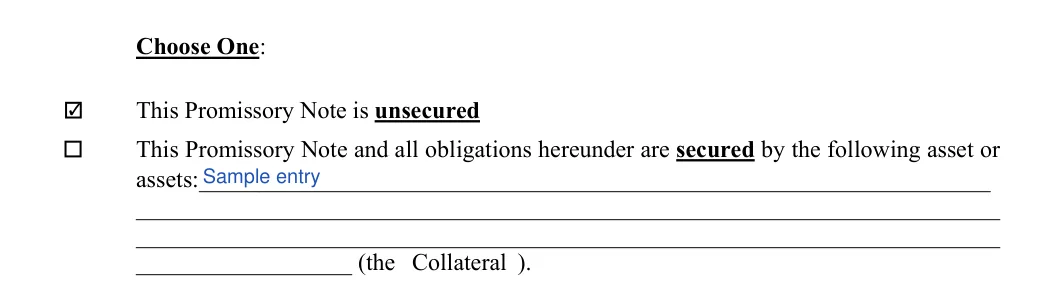
A secured note gives the lender security for the loan. The security is property that the borrower pledges, such as a car, equipment, savings, or real estate. An unsecured note pledges no property, so the lender relies on the promise to repay alone. People often choose an unsecured note for a loan to a friend or family member they trust.
A secured note takes a little more work. You describe the property on page 2 of the form, so name each item clearly. For a vehicle, give the make, model, and year. For real estate, give the street address. A clear description makes it easy to match the document to the property it covers.
Agree on the terms with the other party first. The form asks for personal information such as names and addresses, so have the details ready. Then gather what the form asks for:
Read the finished form once more from top to bottom. Check that the names, the amounts, and the dates match the terms you agreed on.
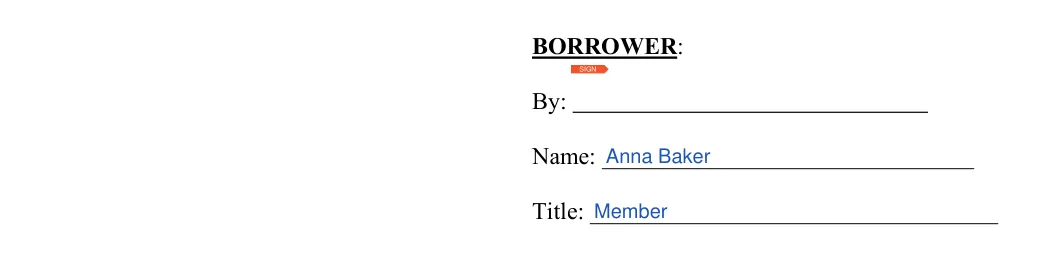
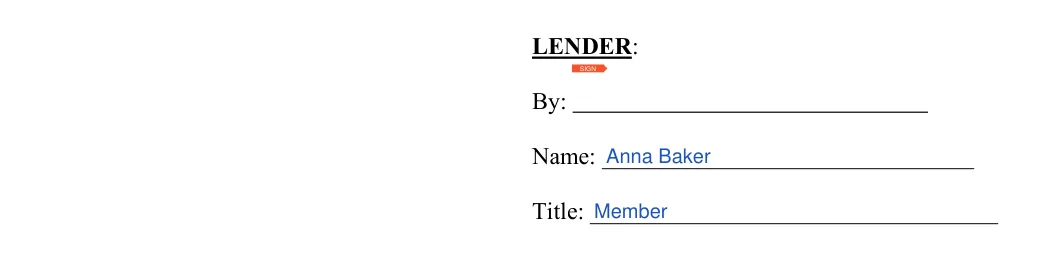
Both parties sign on page 3 of the form. Signing at the same time and in the same place makes it easy to confirm the terms. Each signature block has a By line, a printed name, and a title, so the signature matches the person named above it.
The lender is the note holder, which means the person who is paid under the note. Print two copies of the signed document, so each side keeps one. Keep a simple record of what has been paid next to the note, so it is easy to show what is still owed.
People use a promissory note whenever one person lends a sum to another and wants the terms in writing. The note shows the sum lent, the cost of borrowing, and the repayment plan, so both sides can check the terms later. It is a legal document that records the obligations of each side, whether the loan is personal or for a business. Common uses include the following:
The table below shows how one set of entries could look on the Colorado form. The names and figures are made up for the example.
| Form field | Sample entry |
|---|---|
| Date | October 1, 2026 |
| Principal Amount | $5,000 |
| Lender | Anna Baker |
| Borrower | Ben Carter |
| Rate per annum | 8% |
| Payment due day | The 1st day of each calendar month |
| Payment amount | Fixed payment of $225 |
| Maturity Date | October 1, 2028 |
| Security | Unsecured |
Most problems with a promissory note come from small gaps in the form. Check each of these before you sign:
A few minutes of checking at the signing stage saves a lot of confusion later, because the signed form is the main record of what both parties agreed.
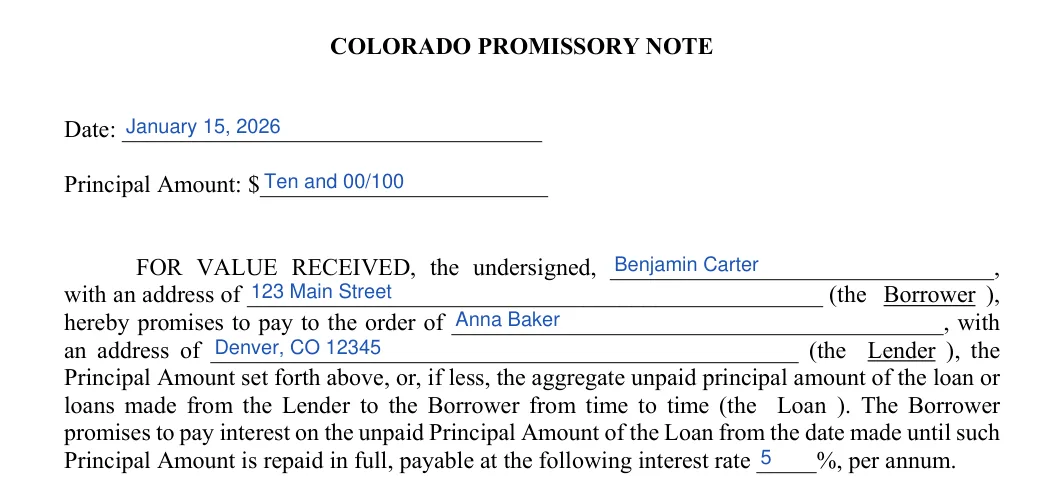
The Colorado promissory note PDF has 28 fillable fields across three pages. Work through it section by section, from the principal amount to the two signatures. The six steps below follow the form, and each one shows the form filled in with sample entries.
The screenshots under each step show the FormsPal Colorado promissory note template filled with sample entries in blue, so you can see where each answer goes. The names, addresses, dates and amounts are examples only.
To type into the downloaded PDF, use our online PDF editor. For a general overview of the document and a template for every state, see our sample promissory note template.
These questions cover the interest rules readers ask about most. Each answer comes from the Colorado statutes listed in the sources at the end. The short version comes down to three numbers, which are listed first.
Colorado lets a promissory note set a rate above 8% a year, but not above 45% a year.[1.3] A rate of 30% a year is below that ceiling. The definition in § 5-12-103 counts every charge the lender imposes as a condition of the loan as interest, so add those charges to the stated rate first.[1.2]
If the parties have not agreed on a rate and no other provision of law sets one, the rate is 8% a year, compounded annually.[1.1] The parties can agree on a higher rate in the note, up to 45% a year.[1.3]
Usury laws limit how much interest a lender may charge. In Colorado, a promissory note can set a rate up to 45% a year.[1.3] Knowingly charging above an annual percentage rate of 45% is criminal usury, a class 6 felony.[2]
For a promissory note, the most the parties can agree on is 45% a year.[1.3] The same 45% a year is the ceiling for periodic interest under a commercial credit plan.[1.4]

General information, not legal or tax advice.
Unless noted otherwise, the sources below are from the Colo. Rev. Stat.
