
Updated:
A payment agreement is a contract to repay a debt in installments. The free fillable PDF template below names both parties, the amount owed, any interest and the payment dates. Debtors and creditors use it when a balance cannot be paid in a single payment.

A payment agreement, also called an agreement of payment or a contract for payment, is a signed plan in which a debtor promises to repay an outstanding balance to a creditor in installments over an agreed period.
The creditor accepts smaller payments on a schedule both sides can live with, instead of one lump sum. In return, the debtor commits in writing to the amount, the dates and the method of each payment, such as a bank transfer or a card charge.
The Payment (Installment) Agreement template on this page is a short fillable PDF. It names the debtor and the creditor, records the amount owed and lets you pick a repayment schedule with check boxes. You can complete it on screen or print it and write the details by hand.
The template covers these points:
You need a payment agreement when one person or business owes money to another and both sides agree that the balance will be paid off in parts rather than at once.
Common examples:
A written payment plan gives both sides one clear reference for what was promised, so a missed payment or a disagreement can be checked against the signed terms rather than against memory.
Emails, text messages and phone calls about a debt are easy to forget or read differently later. A signed agreement collects the terms in one document. The creditor knows when each payment is due, and the debtor knows exactly how much is left and when the plan ends.
A written payment agreement puts the main points in one place:
Tip: Keep every email and message about the payment plan together with the signed agreement. A simple list of the dates and amounts you have paid or received makes it easy to check the balance.
A payment agreement sets a repayment plan for a balance that already exists, while a loan agreement covers new money that one party lends to another and the terms for paying it back.
If the money has not changed hands yet, a loan agreement template fits better. If the debt already exists, for example an unpaid invoice or a past purchase, the payment agreement on this page is the right document.
A clear payment agreement includes the parties, the amount owed, the payment schedule, any interest and late fees, what happens on default, how disputes are settled and how the terms can be changed.
The default clause of a payment agreement explains what happens when the debtor misses payments under the repayment plan, so neither side has to guess the next step.
For example, the clause can let the creditor call the whole unpaid balance and the interest so far due at once after a missed payment.
A severability clause records that the parties want the rest of the payment agreement to stand if one of its provisions turns out to be void, so they do not have to rewrite the whole plan over a single flawed term.
A dispute resolution clause tells the creditor and the debtor how they will settle a disagreement about the payments, for example through negotiation, mediation or arbitration.
The template on this page handles a related question, which jurisdiction's rules apply, in its own section, covered in the steps below.
An amendments clause asks the parties to make any change to the payment agreement in writing, signed by both of them.
A signed email can be a writing too: for a transaction in or affecting interstate or foreign commerce, 15 U.S.C. § 7001(a) says a contract may not be denied legal effect solely because an electronic signature or electronic record was used in its formation. To avoid a dispute over a later spoken change, put every change in a signed amended copy that both sides keep.
To write a payment agreement letter, put both names at the top, name the debt, set out each payment and its due date, say what happens if a payment is missed, and have both sides sign.
A letter suits a simple plan between two parties who know each other. The fillable template above asks the same questions in a fixed order, which makes it harder to leave a term out.
Example of a payment agreement letter (sample only):
March 3, 2027. Jordan Lee agrees to repay Sam Rivera the balance of $1,800 owed for kitchen repairs. Jordan will pay $300 on the 1st of each month, from April 1, 2027 to September 1, 2027, by bank transfer. No interest applies. If a payment is more than 10 days late, the rest of the balance becomes due at once. Signed: Jordan Lee, Sam Rivera.
The steps below follow the Payment (Installment) Agreement template on this page, in the same order as the blanks on the form. Gather a few details first and you can fill in every blank in one sitting.
The screenshots under each step show the FormsPal Payment (Installment) Agreement template filled with sample entries in blue, so you can see where each answer goes. The names, addresses, dates and amounts are examples only.
Before you start, have these details at hand:
Step 1: Parties
Write the debtor's name and the creditor's name in the opening paragraph. You do not fill in an effective date, because the template uses the latest date on the signature lines.
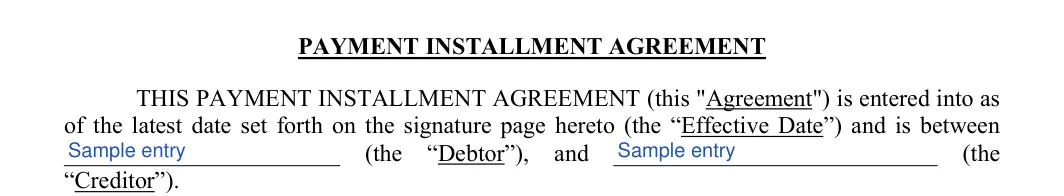
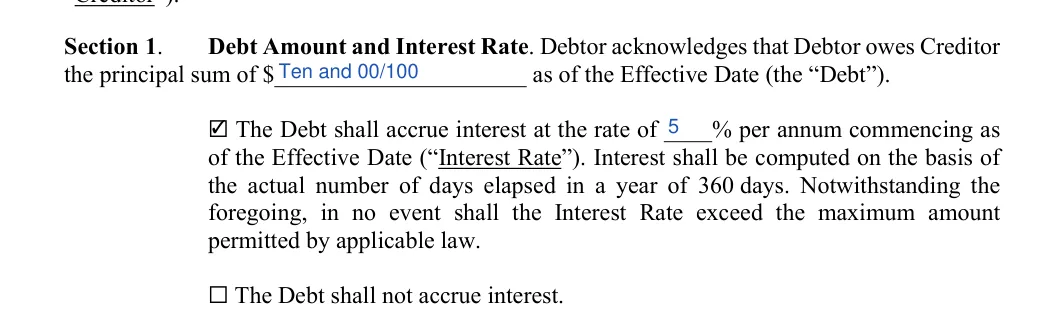
Step 2: Debt Amount and Interest Rate
Enter the principal sum, which is the amount the debtor owes. Check the first box and write the yearly interest rate if the debt carries interest. Check the second box if it does not.
Interest limits differ from place to place: in Florida, for example, section 687.02(1), Florida Statutes, declares usurious a contract for interest above the equivalent of 18 percent per annum simple interest, unless the debt exceeds $500,000, when the rate in s. 687.071 is the test instead (section 687.02(1), Florida Statutes). Check the limit for the place you name in Step 5 before you write a rate.
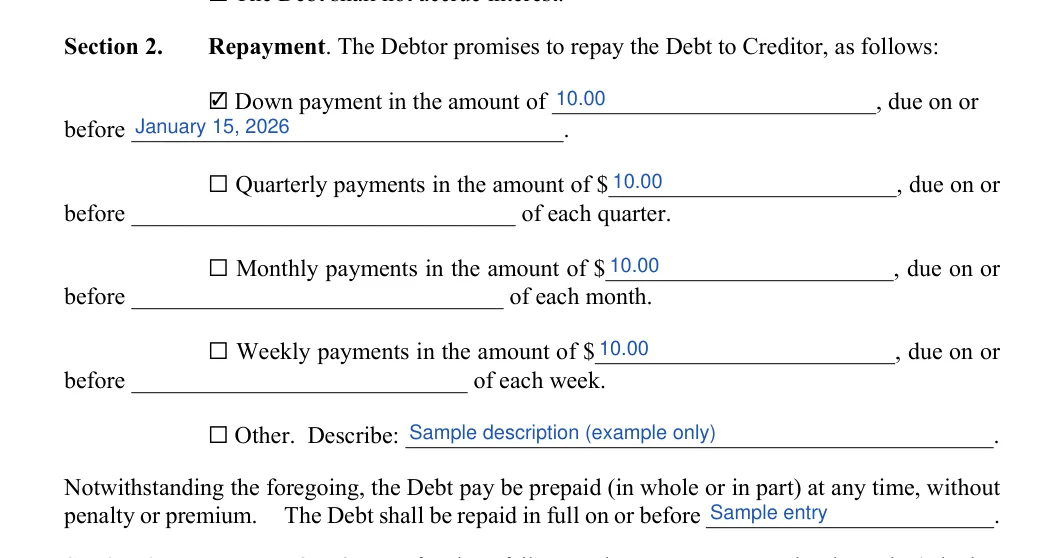
Step 3: Repayment
Check each payment option that applies, such as a down payment or weekly, monthly or quarterly payments, and fill in its amount and due date. Use the Other line to describe a different schedule, then enter the date by which the debt is paid in full.
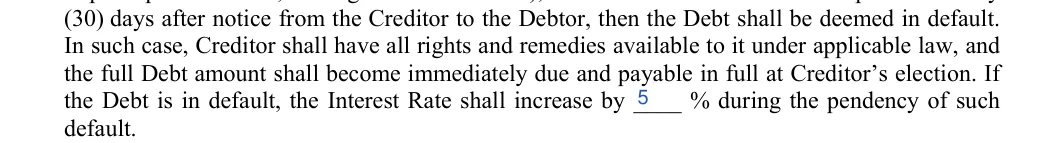
Step 4: Increase of interest rate
Write the percentage points the interest rate goes up if the debt falls into default. The rest of that paragraph is printed on the template. Check that the raised rate, added to the rate in Step 2, still stays within the interest limit described in Step 2.
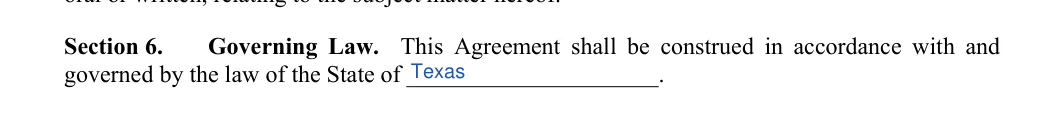
Step 5: Governing law
This section of the payment agreement is meant to tell which state laws will govern its construction and effectiveness. Write the state in the blank after "State of".
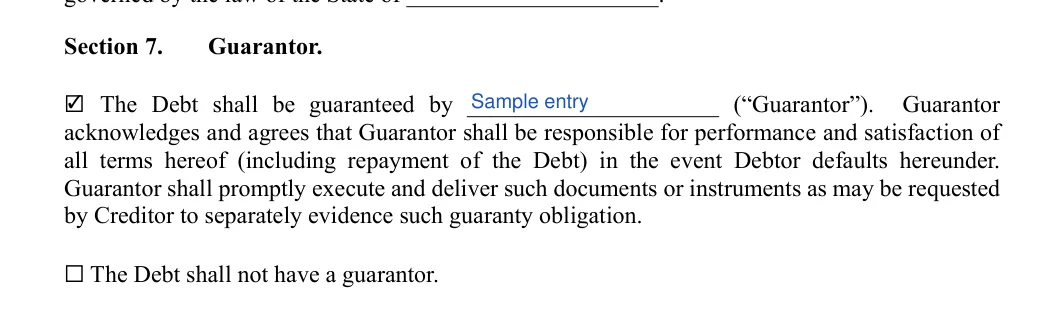
Step 6: Guarantor
A guarantor is someone other than the debtor who backs the debt. Check the first box and write that person's name, or check the second box if the debt has no guarantor.
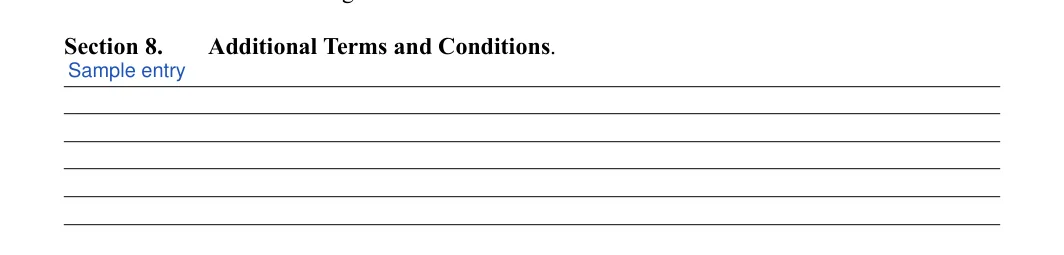
Step 7: Additional Terms and Conditions
Use the ruled lines for any extra terms the two sides have agreed on. Leave the lines blank if there are none.
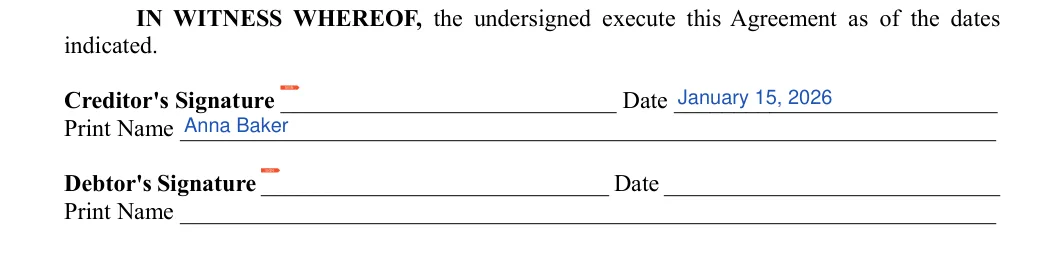
Step 8: Creditor and Debtor signatures
The creditor and the debtor each sign, date and print their name on their own line.
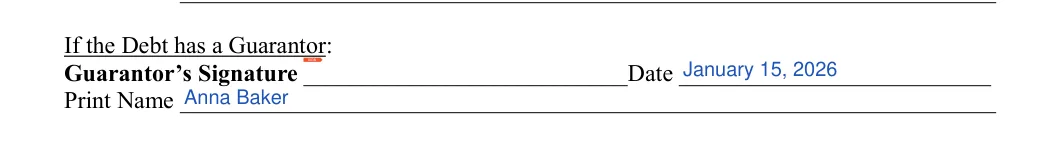
Step 9: If the Debt has a Guarantor
Only if you named a guarantor in Step 6, the guarantor signs, dates and prints their name here. Skip this block when the debt has no guarantor.
A payment plan agreement works when the debtor and the creditor agree on the terms first, write them into the template, sign it together and then follow the schedule until the last installment is paid.
Talk through the balance, the size of each installment, the schedule and any interest before anything is written down. A plan the debtor can afford is more likely to be paid on time. Two kinds of plan are common:
Fill in the template with the agreed terms and read it through together. Each party signs, dates and prints their name, and each keeps a signed copy. If someone backs the debt as a guarantor, that person signs too.
The creditor collects the debtor's payment details for the chosen method. A credit card or ACH authorization form gives the creditor written permission to charge a card or debit a bank account. For recurring transfers from a consumer's bank account, 12 CFR 1005.10(b) allows them to be authorized only by a writing signed or similarly authenticated by the consumer, and the person that obtains the authorization gives the consumer a copy (12 CFR 1005.10(b)). Many plans use automatic payments, so each installment is charged on its due date.
Keep receipts, bank statements or a simple payment log beside the signed agreement. When the last installment clears, the creditor can confirm in writing that the debt is paid in full.
For a large debt, or terms you are unsure about, talking to an attorney before signing is a sensible step.
Yes. Download the fillable PDF from this page, then type your answers into it with the PDF editor. You can also print the template and fill it in by hand.
The template on this page is a fillable PDF, not a Word document. You can type into it on screen with the PDF editor, so you do not need Word to complete it.
Have the names of the debtor and the creditor, the amount owed, the interest rate if there is one, and the payment dates ready. If someone backs the debt as a guarantor, you also need that person's name.
The template has check boxes in Section 2 for a down payment and for weekly, monthly or quarterly payments. It also has an Other line for any schedule that does not fit those options.
An agreement between two parties is usually called a contract. A payment agreement is a contract in which one party agrees to pay the other a set balance on a schedule.
No. An invoice asks for payment of a bill, while a payment agreement is signed by both sides and sets out how an unpaid balance will be paid off over time.
Yes. Keep a signed copy with your payment records, along with receipts or bank statements that show each installment. It helps both sides check what has been paid and what is still owed.
General information, not legal or tax advice.

