
A Massachusetts promissory note is a written promise to repay a loan, stating the amount, the interest rate and when payments are due. Individuals and businesses use it to document personal and small business loans, and the borrower signs it. Massachusetts limits the interest a lender can charge through its criminal usury law, Mass. Gen. Laws ch. 271, § 49.[1] A note does not secure the loan unless it lists collateral.
Last Updated: October 2026. This guide is reviewed and updated regularly to reflect current Massachusetts law. If you notice an error or outdated information, please contact us.
Build Your Document
Answer a few simple questions to make your document in minutes
Save and Print
Save progress and finish on any device, download and print anytime
Sign and Use
Your valid, lawyer-approved document is ready
Every promissory note, in any state, rests on the same few details. Our simple promissory note document shows the general layout. A clear note usually includes:
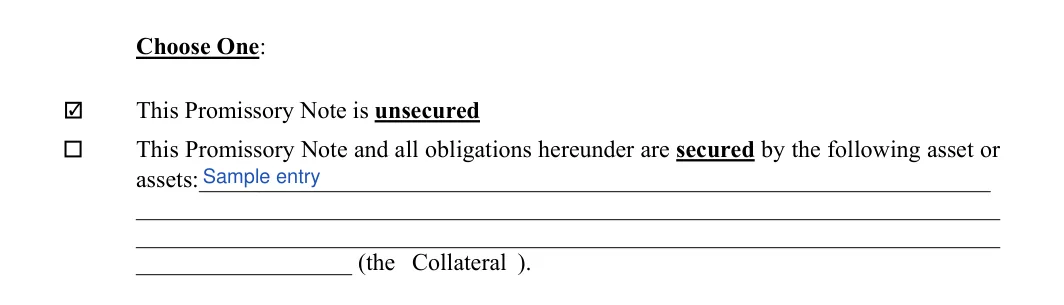
A secured note also lists an item the borrower pledges, called collateral, in case the money is not repaid. An unsecured note has no collateral. People often choose an unsecured note for a small loan to a friend or relative. The Massachusetts template lets you pick either type.
Massachusetts treats a loan rate above 20% per year as criminal usury. A lender who charges more can face up to ten years in state prison, a fine of up to $10,000, or both. The rule sits in Mass. Gen. Laws ch. 271, § 49, and it counts interest and expenses together.[1]
Whoever in exchange for either a loan of money or other property knowingly contracts for, charges, takes or receives, directly or indirectly, interest and expenses the aggregate of which exceeds an amount greater than twenty per centum per annum upon the sum loaned or the equivalent rate for a longer or shorter period, shall be guilty of criminal usury and shall be punished by imprisonment in the state prison for not more than ten years or by a fine of not more than ten thousand dollars, or by both such fine and imprisonment.
The 20% limit applies to the sum loaned. For a loan that runs longer or shorter than a year, the law uses the equivalent rate.[1]
The law counts more than the rate written on the note. For this rule, interest and expenses include all sums paid, or to be paid, by or on behalf of the borrower for:
The same applies to sums paid to or charged by anyone other than the lender. The lender must have known of the charge when making the loan, or could have found out by reasonable inquiry.[1]
The usury rule does not apply to every loan. It does not cover a loan whose interest rate is regulated under another law or regulation. It also does not cover a lender who is subject to control, regulation or examination by a state or federal regulatory agency.[1]
Knowingly possessing any writing, paper, instrument or article used to record a usurious loan is also a crime. The penalty is up to two and one half years in a jail or house of correction, a fine of up to $5,000, or both.[1]
A court can also declare a loan at a prohibited rate void. The borrower asks for this by petition to the supreme judicial court or the superior court in equity.[1]
The 20% figure is the criminal usury limit. The legal rate of interest is a separate rule: under Mass. Gen. Laws ch. 107, § 3, if there is no agreement or provision of law for a different rate, interest is six dollars on each hundred for a year, which is 6% per year.[2]
The usury rule does not apply to any person who notifies the Attorney General of an intent to engage in a transaction or transactions that it would otherwise proscribe, providing the person maintains records of any such transaction.[1] The notice itself has its own rules:
The records must show:
The Attorney General can inspect these records on request. The records and their contents are confidential. The Attorney General, or any district attorney with the Attorney General's approval, may use them in a criminal proceeding to which they are relevant.[1]
| Document Name | Massachusetts Promissory Note Form |
| Other Name | MA Promissory Note |
| Max. Rate | 20% per year on the sum loaned, or the equivalent rate for a longer or shorter period. A higher rate is criminal usury.[1] |
| Relevant Laws | Massachusetts General Laws, Chapter 271, Section 49 |
| Avg. Time to Fill Out | 10 minutes |
| # of Fillable Fields | 28 |
| Available Formats | Adobe PDF |
Popular Local Promissory Note Forms
A promissory note (often referred to as note payable) is considered a basic money template used regularly by both individuals and businesses throughout all states as a funding source and an alternative to banks. Find out more about the most popular US states requested by our website users concerning promissory note forms.
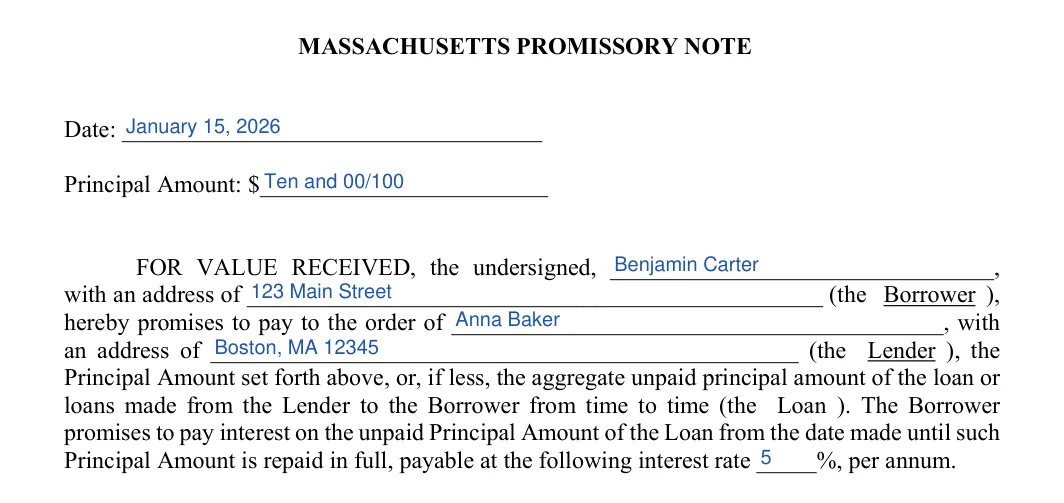
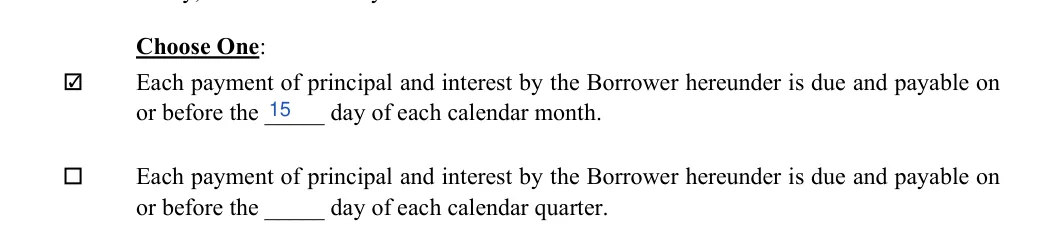
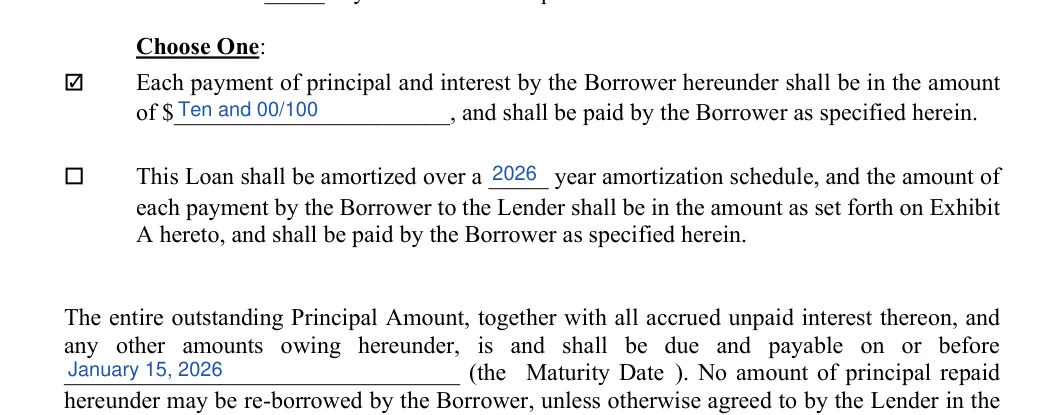
The FormsPal Massachusetts promissory note is a three-page PDF with 28 fillable fields. Each step below names one part of the form, in the order it appears, so you can move from the first fields to the signature lines without skipping anything. Fill it in with the online PDF editor or print it and write by hand, then both parties sign.
The screenshots under each step show the FormsPal Massachusetts promissory note template filled with sample entries in blue, so you can see where each answer goes. The names, addresses, dates and amounts are examples only.
These answers cover the Massachusetts interest limit, what the criminal usury statute counts as interest, and what a lender must do to use the notice to the Attorney General. Each answer is kept short so you can find the point you need quickly.
In Massachusetts, a rate above 20% per year on the sum loaned, or the equivalent rate for a longer or shorter period, is criminal usury. Interest and expenses are added together to test the rate.[1]
The limit is 20% per year, set by Mass. Gen. Laws ch. 271, § 49. Charging more is criminal usury, punishable by up to ten years in state prison, a fine of up to $10,000, or both.[1]
Up to 20% per year on the sum loaned for a loan under this rule. Fees and other charges the borrower pays to make or secure the loan count toward that figure.[1]
The statute states its cap as a yearly rate on the sum loaned, with interest and expenses counted together. Twenty per cent per year is the figure to stay under.[1]

Other Promissory Note Forms by State
General information, not legal or tax advice.
