
Updated:
A secured promissory note is a written loan promise backed by collateral. It names the loan amount, interest rate, repayment plan, and the asset pledged if payments stop. Lenders use it for large loans, especially to borrowers with thin credit.
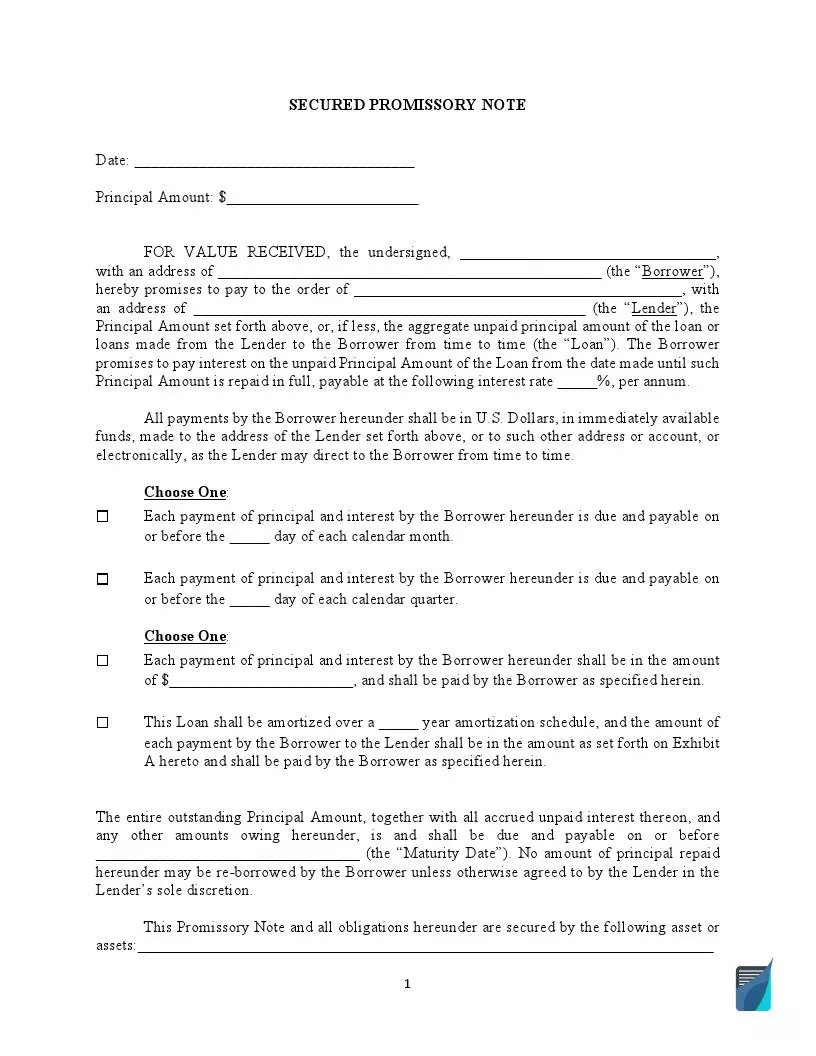
You can fill in the free secured promissory note template on this page with the document builder or download it as a PDF. It is one of two types of promissory note templates, the other being an unsecured note.
Build Your Document
Answer a few simple questions to make your document in minutes
Save and Print
Save progress and finish on any device, download and print anytime
Sign and Use
Your valid, lawyer-approved document is ready
A secured promissory note is a borrower's signed promise to repay a loan, with an asset such as a car, jewelry, or a house pledged as collateral. The note names that asset as the lender's backup if the borrower stops paying.
The word "secured" means the loan has property of value behind it. The note sets out the debt: who owes whom, how much, at what interest rate, and by when. The collateral terms say which asset backs that debt.
A secured note often goes with a loan agreement or forms part of one. The note is the promise to pay, and the collateral terms are the pledge that stands behind it.
A security agreement is the part of a secured note that pledges personal property, such as a car, a boat, jewelry, or business equipment, as collateral for the loan. In the FormsPal template, the collateral lines after "secured by the following asset or assets" do this job.
A mortgage or a deed of trust is the separate document that pledges a house or land when real estate backs the loan. The note sets out the debt, and the mortgage or deed of trust ties that debt to the property. FormsPal has a deed of trust form for this.
Collateral can be personal property, such as a vehicle or savings, or real property, such as a house or land. Common choices include:
Collateral protects the lender only when the asset is worth at least the loan amount at its current market value. For a used car, that is what the car would sell for today, not what it cost new.
Check the value again for a long loan. A car loses value each year, while the balance of an amortized loan falls with every payment.
A secured promissory note is backed by a named asset, while an unsecured promissory note rests only on the borrower's promise to repay. The table sets the two side by side.
| Point | Secured note | Unsecured note |
|---|---|---|
| What backs the loan | A named asset, such as a car, jewelry, or a house | The borrower's promise alone |
| Extra papers | A collateral description; a mortgage or deed of trust for real estate | None beyond the note |
| Risk for the lender | Lower, because an asset stands behind the debt | Higher, because nothing specific stands behind it |
| Typical use | Large loans, sales paid over time, borrowers with weak credit | Smaller loans between people who trust each other |
Example: Sam lends his sister $2,000, and she signs a note to repay it in ten monthly payments. Nothing backs the note but her promise, so it is unsecured. If she pledged her motorcycle as collateral in the same note, it would be a secured note.
A secured promissory note fits when the lender wants more than a promise: a large loan, a buyer paying over time, or a borrower with weak credit or little income but valuable assets. Between friends and family, collateral is worth asking for when losing the money would hurt.
A seller who lets a buyer pay the price later can use a secured note to turn the unpaid price into a loan, backed by an asset the buyer already owns.
For example, Olivia wants to buy jewelry worth $10,000 for her wedding day from John's shop, but she does not have the full amount at that moment. John loans her the purchase amount through a secured promissory note. Olivia pledges her car as collateral and agrees to pay John back after four months, with interest.
A borrower with past defaults or thin credit can still get a loan when the note pledges an asset the lender can fall back on. The collateral stands in for a strong credit score.
A borrower with little steady income but a valuable asset, such as an inherited house, can pledge that asset in a secured note to get a loan. The lender looks to the asset rather than the paycheck.
For example, A and B are friends. A wants to borrow $100,000 from B to start a new business. The business may or may not earn enough to repay B. A inherited her parents' home in Dallas, which has a good market value, so B agrees to lend on the condition that the note pledges that home.
A large principal amount is a strong reason to use a secured note, because the collateral limits the lender's loss if the borrower stops paying. The bigger the loan, the more a lender gains from having an asset behind it.
A secured promissory note names the parties, the loan amount, the interest rate, the repayment plan, the collateral, the choice of governing law, and the signatures with dates. Check each item below before anyone signs.
For the other terms a promissory note can carry, such as late fees or prepayment, see FormsPal's free promissory note template.
A secured note can be repaid in a single lump sum, in equal amortized installments, in installments that end with a balloon payment, or on the lender's demand. Pick the plan before you fill in the template, because it decides which boxes you check.
| Plan | How payments work | What to write in the note |
|---|---|---|
| Lump sum | Principal and interest are paid in one payment on the maturity date | The maturity date and the total amount due |
| Amortized installments | Equal payments; the interest share falls and the principal share rises over time | The length of the schedule, with the schedule attached |
| Installments with a balloon final payment | Regular smaller payments, then one larger last payment that clears the balance | Each payment amount, plus the final amount and its date |
| Interest only with a balloon | Payments cover interest only; the whole principal comes due at maturity | The interest payment and the maturity date |
| Payable on demand | No fixed due date; the borrower pays when the lender asks | Any notice period the parties agree on |
A secured demand promissory note is a note the borrower repays whenever the lender asks, with collateral standing behind it. Because it has no due date, the parties can agree on a notice period after a written demand and write it into the note.
An installment note with a balloon final payment has regular payments that do not cover the whole loan, followed by one large last payment of the remaining balance. Write the balloon amount and its due date in the note so the borrower can plan for it.
An interest-only note is the extreme case: every regular payment covers interest, and the full principal is the balloon.
An amortized note has equal payments in which the interest share falls and the principal share rises over time. The FormsPal template asks for the length of the amortization schedule and refers to an Exhibit A, which you prepare yourself. A free amortization calculator can produce the schedule.
Interest rate caps for a secured note differ from one jurisdiction to the next, and several carry exceptions. The table gives the rule as each statute words it, with its condition and citation.
| State | Interest limit in the statute | Condition or exception | Citation |
|---|---|---|---|
| Colorado | More than eight percent and up to forty-five percent per annum | When the parties stipulate it in a bond, bill, promissory note, or other instrument of writing | Colo. Rev. Stat. § 5-12-103(1) |
| Florida | More than the equivalent of 18 percent per annum simple interest is usury | Applies to a loan, advance of money, line of credit, or other obligation of $500,000 or less; above $500,000, interest is usury only if the rate exceeds the rate in Fla. Stat. § 687.071 | Fla. Stat. § 687.03 |
| Kansas | Up to 15% per annum | In a bond, bill, promissory note, or other instrument of writing, unless otherwise specifically authorized by law | Kan. Stat. Ann. § 16-207 |
| Missouri | Up to ten percent per annum, or up to the "market rate" when the market rate exceeds ten percent per annum | Only when the parties agree to the rate in writing; the market rate for a calendar quarter is the monthly index of long term United States government bond yields for the second preceding calendar month plus three percentage points | Mo. Rev. Stat. § 408.030 |
| New York | Sixteen per centum per annum | The maximum rate for section 5-501 of the general obligations law | N.Y. Banking Law § 14-a |
| Ohio | Up to eight per cent per annum, payable annually | In a promissory note or other instrument of writing, except as authorized in division (B) of the section | Ohio Rev. Code Ann. § 1343.01 |
| South Dakota | No maximum rate | Only if the parties set the rate by written agreement, and unless a maximum is specifically established elsewhere in the code | S.D. Codified Laws § 54-3-1.1 |
| Texas | 10 percent a year | Except as otherwise provided by law | Tex. Fin. Code § 302.001 |
| Virginia | 12 percent per year on a loan | Except as otherwise permitted by law | Va. Code Ann. § 6.2-303 |
Different states have different limits regarding the maximum rates that can be charged.
Many codes set separate caps for consumer loans, small loans, or licensed lenders, so read the governing code before you fill in the rate.
These steps follow the FormsPal secured promissory note template that you can download from this page. Fill in the blanks in the order shown, and keep your own copy of the finished note. To type directly into the downloaded file, open it in the FormsPal PDF editor.
The screenshots under each step show the FormsPal Secured Promissory Note template filled with sample entries in blue, so you can see where each answer goes. The names, addresses, dates and amounts are examples only.
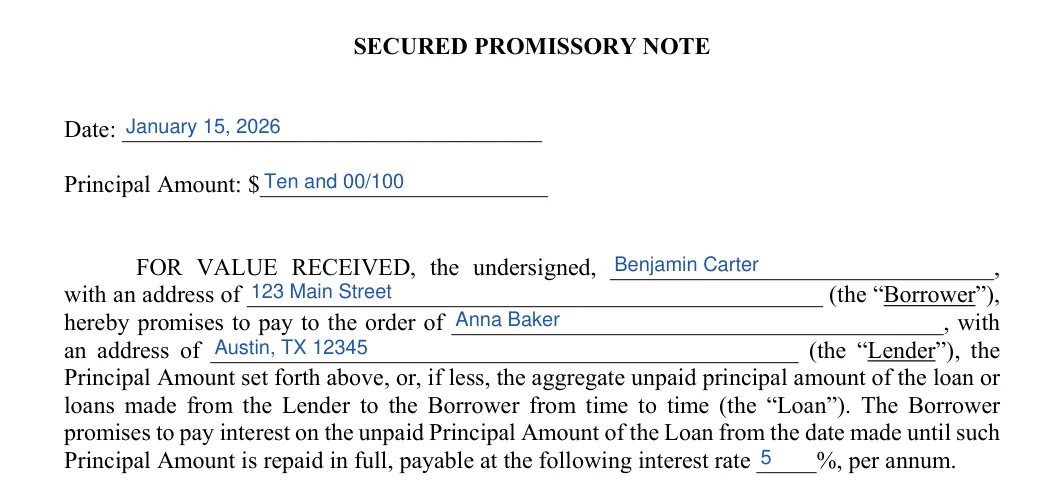
At the top of page 1, enter the date and the principal amount in dollars. In the opening paragraph, enter the borrower's name and address, then the lender's name and address. Include the city, state, and zip code. Then fill in the interest rate percentage.
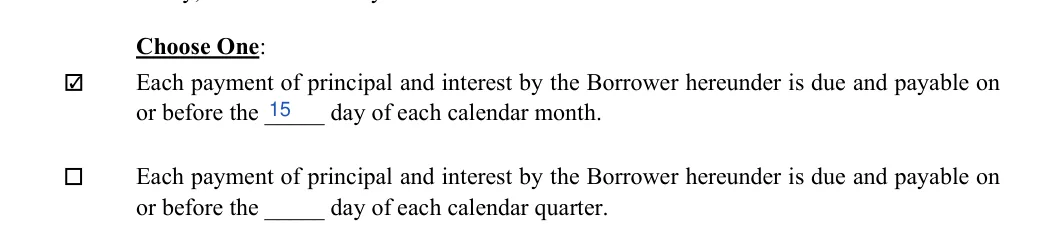
Check the first box and enter a day number if payments are due each calendar month. For example, enter 25 for the 25th day of each month. Check the second box and enter a day number if payments are due each calendar quarter. Fill in only the box you check.
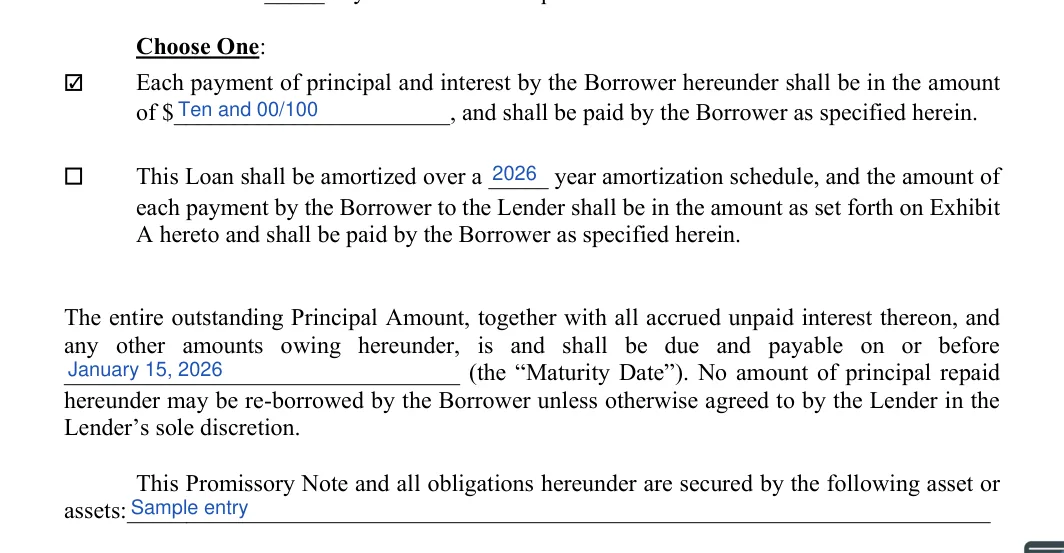
Check the first box and enter the dollar amount of each payment. Or check the second box and enter the number of years of the amortization schedule. That option points to an Exhibit A, which you prepare yourself because the download has no such page. Then enter the maturity date and start describing the collateral on the line after "secured by the following asset or assets."
At the top of page 2, finish the description of the collateral on the two lines that come before the words (the "Collateral"). Identify the assets so anyone could recognize them, for example by their location or identification number. For a house, you could write "two-story house at 123 Main Street, Austin, TX 12345." Naming a house in these lines does not by itself put a lien on it: real estate collateral needs a separate mortgage or deed of trust, signed and recorded in the county where the property sits.
Enter the state name whose law will govern the agreement in case of disputes. It goes on the line after "the laws of the State of" on page 2.
Under BORROWER on page 3, sign on the By line. Then print the borrower's name and title on the lines below it.
Under LENDER on page 3, sign on the By line. Then print the lender's name and title on the lines below it.
A secured promissory note is ready for signatures when every blank is filled in and both sides have read the collateral description and the payment terms. Follow the steps below to finish the document.
You can also use FormsPal's question-based document builder to customize the note for your needs.
Yes, a borrower and a lender can write their own secured note, and a template saves you from starting with a blank page. Use the FormsPal template or the builder, fill in every blank, and make sure the collateral description and the payment terms match what you agreed.
Where no rate is agreed, some states let the lender charge a legal rate on money once it is due, not on the loan from the day it is made, so write a rate in, even a rate of zero. In Kansas, creditors may receive interest at the rate of 10% per annum when no other rate of interest is agreed upon, for any money after it becomes due, except as provided in subsection (b) (K.S.A. § 16-201(a)). In Texas, a creditor who agreed to no interest may charge legal interest at six percent a year on the principal beginning on the 30th day after the date on which the amount is due (Tex. Fin. Code § 302.002). In Virginia, the legal rate of interest is an annual rate of six percent (Va. Code Ann. § 6.2-301(A)).
Yes, put the interest rate in the note itself, so neither side has to rely on memory. In Nevada, the parties shall specify in writing the rate upon which they agree, whether interest is to be compounded if so agreed, and any other charges or fees (Nev. Rev. Stat. § 99.050). In Louisiana, conventional interest must be fixed in writing, and testimonial proof of it is not admitted in any case (La. Rev. Stat. § 9:3500).
Pick the schedule that matches how the borrower receives income.
Talk it over with the other person before you check a box on the form.
A loan agreement fits better when the loan needs more terms than a note holds, such as promises the borrower makes about the money, several lenders, or detailed steps on default. A promissory note is shorter: the borrower's promise to pay, with the amount, rate, schedule, and here the collateral.
Yes. You can answer a few questions in the FormsPal document builder, or download the PDF and type into the blanks on your device. Print the finished note for signatures.
General information, not legal or tax advice.
