
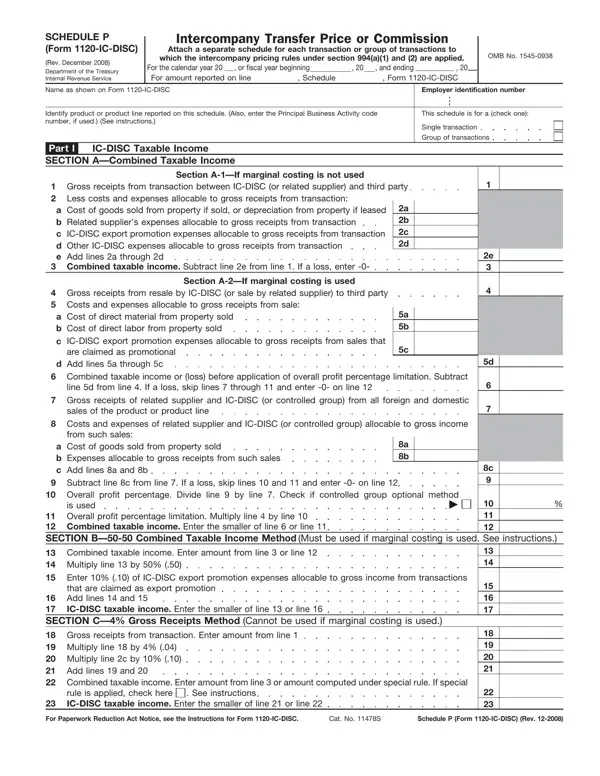

Schedule P (Form 1120-IC-DISC) at a glance
What it is: Schedule P (Form 1120-IC-DISC), Intercompany Transfer Price or Commission: attach a separate schedule for each transaction or group of transactions to which the intercompany pricing rules under section 994(a)(1) and (2) are applied.
Use Schedule P to show the computation of taxable income used in computing (1) the transfer price from a related supplier to an IC-DISC (Part II), or (2) the IC-DISC commission from a related supplier (Part III).
A filled-in Schedule P (Form 1120-IC-DISC) example: a related supplier computes a transfer price under the 50-50 method
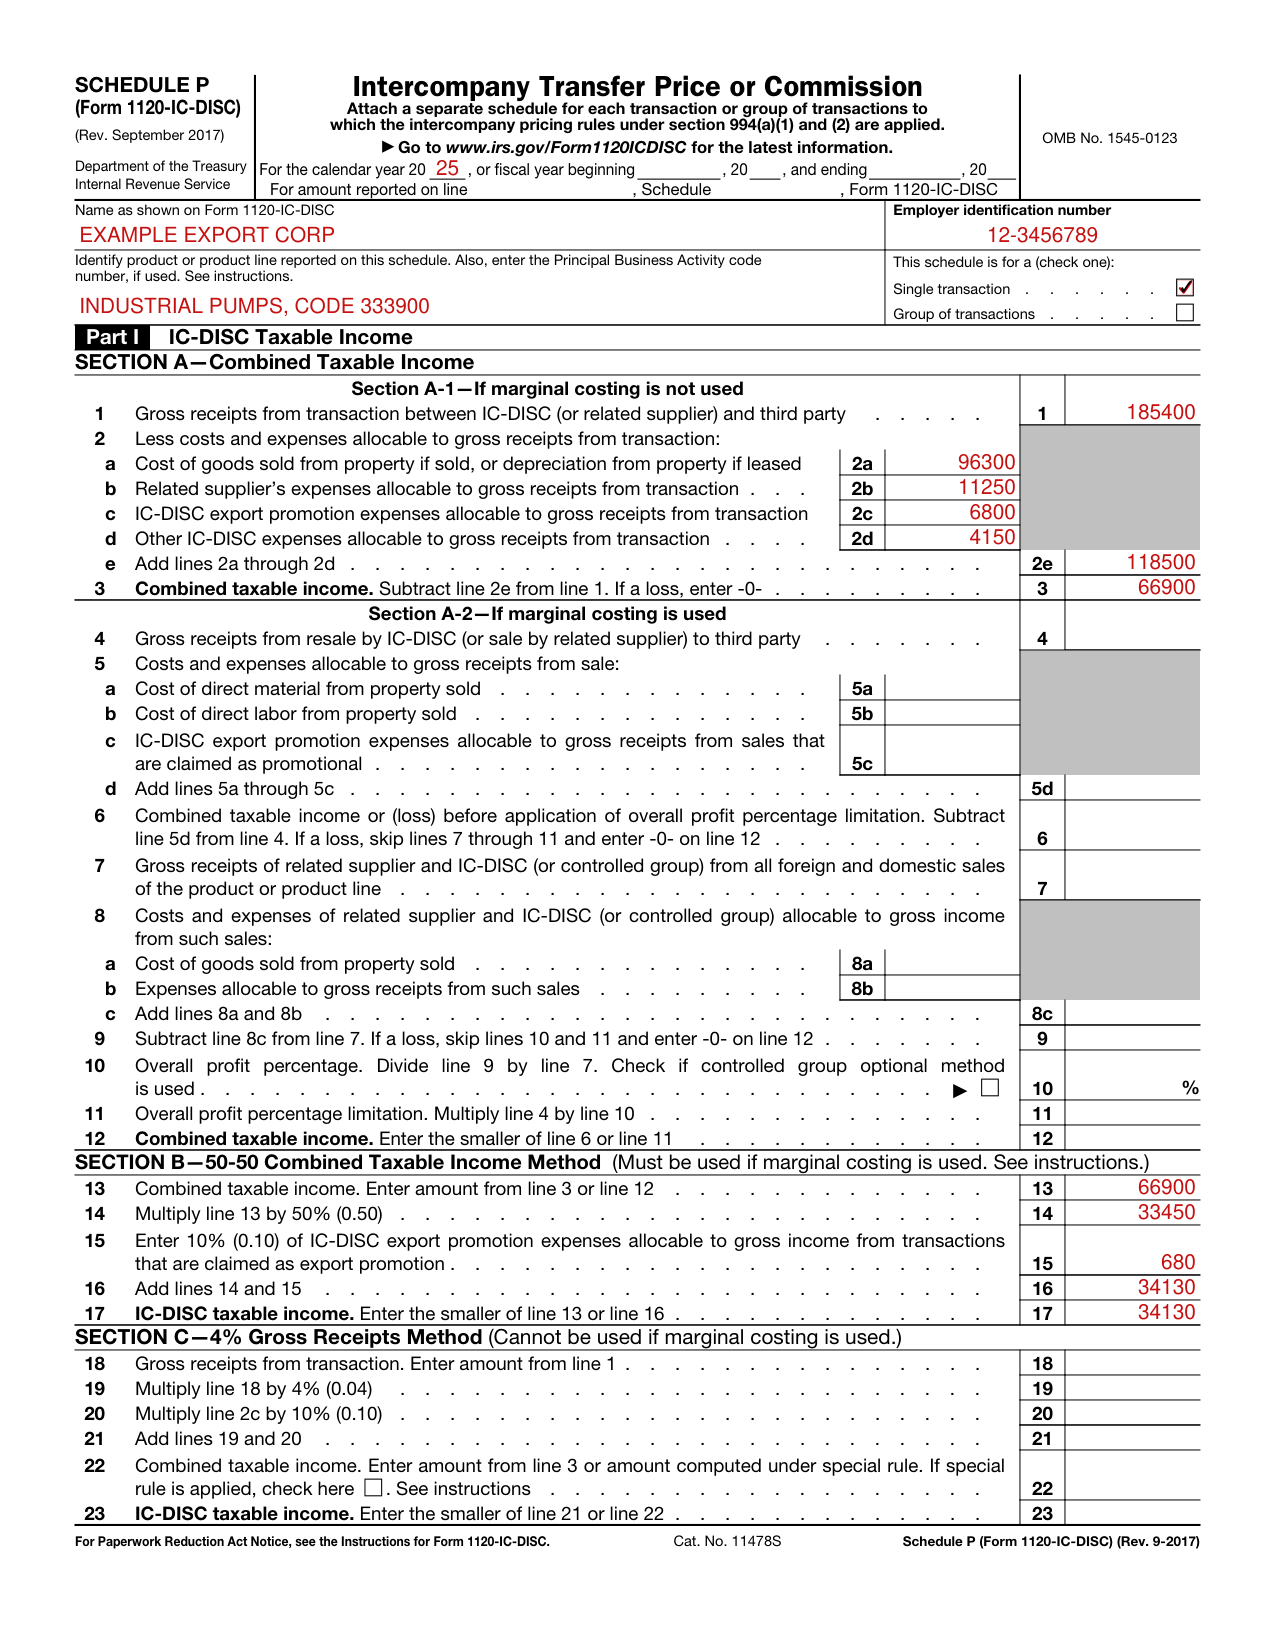
How to fill out Schedule P (Form 1120-IC-DISC), box by box
Name, product, Single transaction and Group of transactions
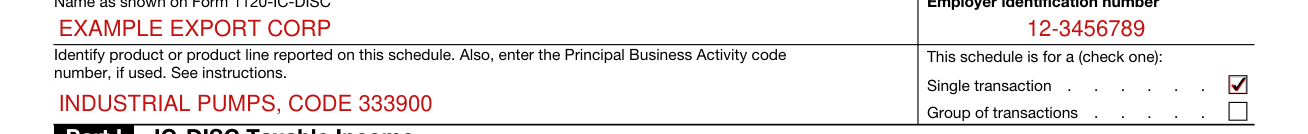
Enter the Name as shown on Form 1120-IC-DISC and the Employer identification number.
Identify the product or product line reported on this schedule. Also, enter the Principal Business Activity code number, if used. See instructions.
A product or product line determination will be accepted if it conforms to either of the following standards: (1) a recognized industry or trade usage, or (2) major product groups (or any subclassifications within a major product group) (see Schedule P (Form 1120-IC-DISC) Codes for Principal Business Activity in the Instructions for Form 1120-IC-DISC).
Check one: this schedule is for a Single transaction or a Group of transactions.
Generally, the intercompany pricing determinations are to be made on a transaction-by-transaction basis. However, the IC-DISC may make an annual election to determine intercompany pricing on the basis of groups consisting of products or product lines.
If the group basis is elected, then all transactions for that product or product line must be grouped. Each group is limited to one type of transaction (for example, sales, leases, or commissions).
Part I, Section A-1: lines 1 to 3, marginal costing not used
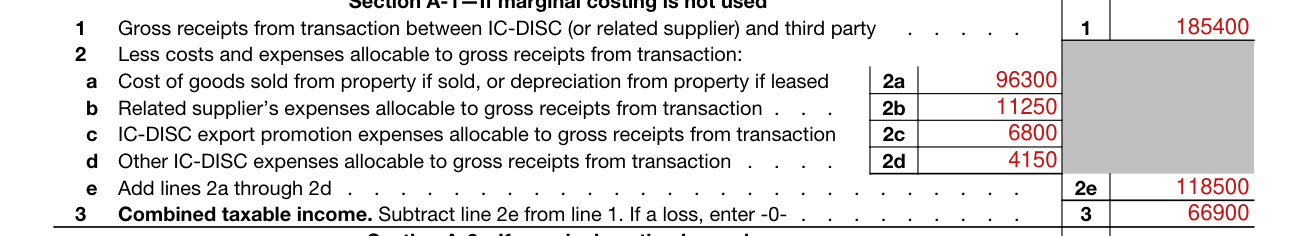
Complete Section A-1 only if marginal costing is not used.
For purposes of line 2d, be sure to include the appropriate apportionment of deductions that are not directly allocable such as interest expenses and stewardship expenses. See Temporary Regulations sections 1.861-11T(f) and 1.861-14T(f) for an explanation of appropriate apportionment.
On line 2e, add lines 2a through 2d.
On line 3, enter the Combined taxable income: subtract line 2e from line 1. If a loss, enter -0-.
Generally, the computation of taxable income under the intercompany pricing rules will not be permitted to the extent that their application would result in a loss to the related supplier.
Part I, Section A-2: lines 4 to 12, marginal costing used
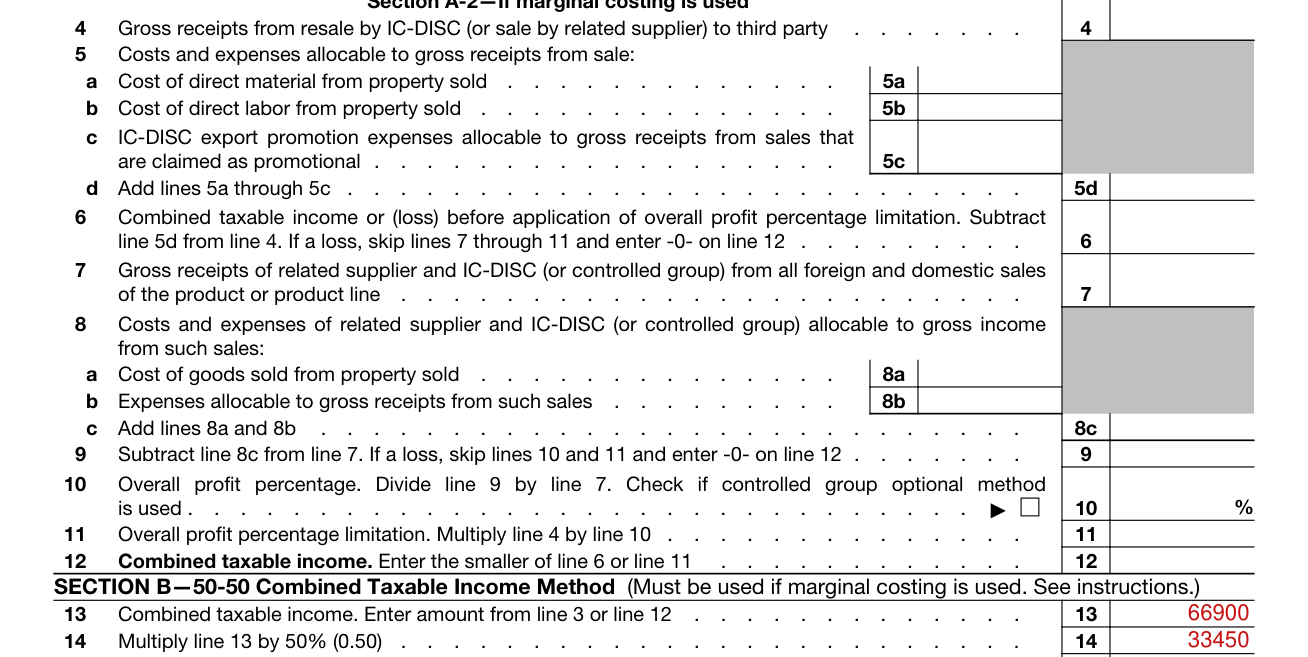
Complete Section A-2 if marginal costing is used. The marginal costing rules may be used only for sales, or commissions on sales, of property if the 50-50 method is used.
On line 6, if a loss, skip lines 7 through 11 and enter -0- on line 12.
On line 10, enter the Overall profit percentage: divide line 9 by line 7.
For line 10, the overall profit percentage may be computed under an optional method. See Regulations section 1.994-2(c)(2) for details.
On line 12, enter the Combined taxable income: the smaller of line 6 or line 11.
Part I, Section B: lines 13 to 17, 50-50 method
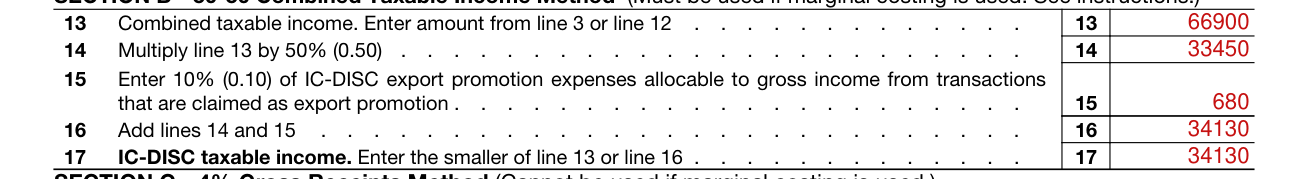
Section B, the 50-50 Combined Taxable Income Method, must be used if marginal costing is used.
In Part I, complete Section B or Section C. If marginal costing is used, you must complete Section B.
On line 14, multiply line 13 by 50% (0.50).
Do not include in combined taxable income (line 13) the discount amount reflected in receivables (on the sale of export property) that a related supplier transferred to the IC-DISC. See Regulations sections 1.994-1(c)(3) and (6)(v).
Part I, Section C: lines 18 to 23, 4% method
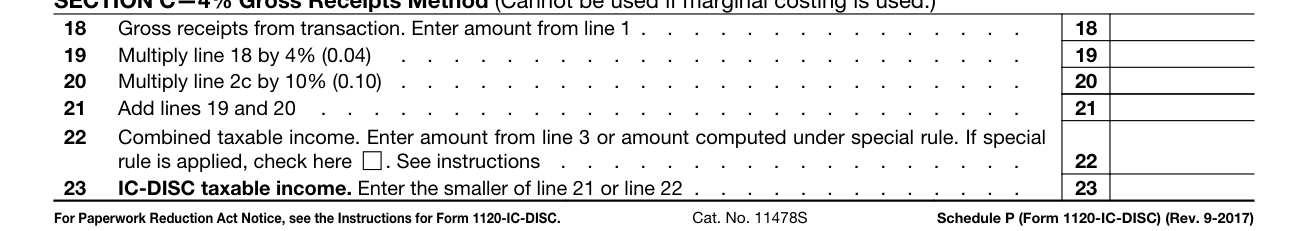
Section C, the 4% Gross Receipts Method, cannot be used if marginal costing is used.
On line 19, multiply line 18 by 4% (0.04).
If IC-DISC taxable income on a sale is computed under the 4% method and the IC-DISC chooses to apply the special rule for transfer prices or commissions, check the box in line 22 and attach a separate statement showing the computation of the limitation on IC-DISC taxable income determined under the special rule and enter the amount on line 22.
Part II: lines 24 to 26, transfer price
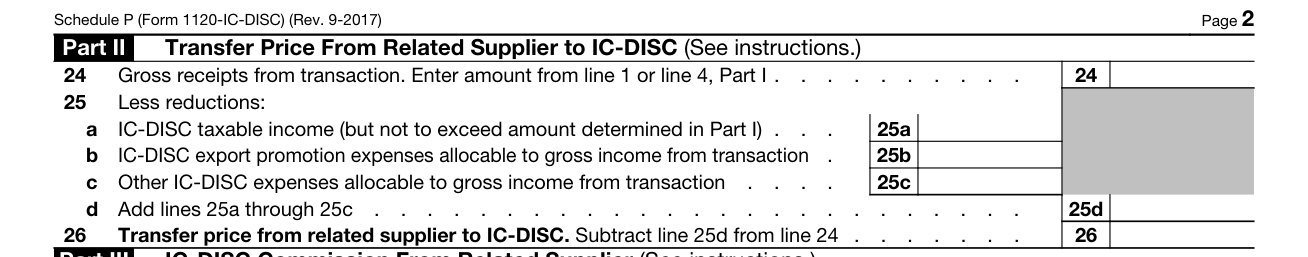
On line 24, enter the Gross receipts from transaction: the amount from line 1 or line 4, Part I.
After line 24, on line 25a under Less reductions, enter the IC-DISC taxable income (but not to exceed amount determined in Part I).
On lines 25b and 25c, enter the IC-DISC export promotion expenses allocable to gross income from transaction, and the Other IC-DISC expenses allocable to gross income from transaction. On line 25d, add lines 25a through 25c.
On line 26, enter the Transfer price from related supplier to IC-DISC: subtract line 25d from line 24.
Part III: lines 27 to 30, commission

On line 27, enter the IC-DISC taxable income (but not to exceed amount determined in Part I). On line 28, enter the IC-DISC export promotion expenses allocable to gross receipts from transaction. On line 29, enter the Other IC-DISC expenses allocable to gross receipts from transaction.
On line 30, enter the IC-DISC commission from related supplier: add lines 27 through 29.
More rules for Schedule P (Form 1120-IC-DISC)
Section references are to the Internal Revenue Code unless otherwise noted.
Section 482 method, incomplete transactions, and more than one line
The section 482 method is used
The transfer price the related supplier charged the IC-DISC, or IC-DISC commission from the related supplier, is the amount actually charged, but is subject to the arm's length standard of section 482. Do not complete Schedule P if the section 482 method is used.
The IC-DISC does not resell the property during the year
For the 50-50 and 4% methods, if the related supplier sells property to the IC-DISC during the year but the IC-DISC does not resell it during the year, the related supplier's transfer price to the IC-DISC must equal the related supplier's cost of goods sold. Do not complete Schedule P for incomplete transactions. The related supplier's transfer price to the IC-DISC must be recomputed for the year in which the IC-DISC resells the property and the transaction must then be reported on Schedule P for that year.
The computed transfer price or IC-DISC commission is entered on more than one line of Form 1120-IC-DISC
If the computed transfer price for sales, leases, or services (Part II) or IC-DISC commission (Part III) is entered on more than one line of Form 1120-IC-DISC, attach an explanation indicating the portion of the total that is applied to each line.
Sources
[1] Schedule P (Form 1120-IC-DISC) (Rev. September 2017), Intercompany Transfer Price or Commission, Internal Revenue Service (the Official source link on this page).