
Form 941 V.I. at a glance
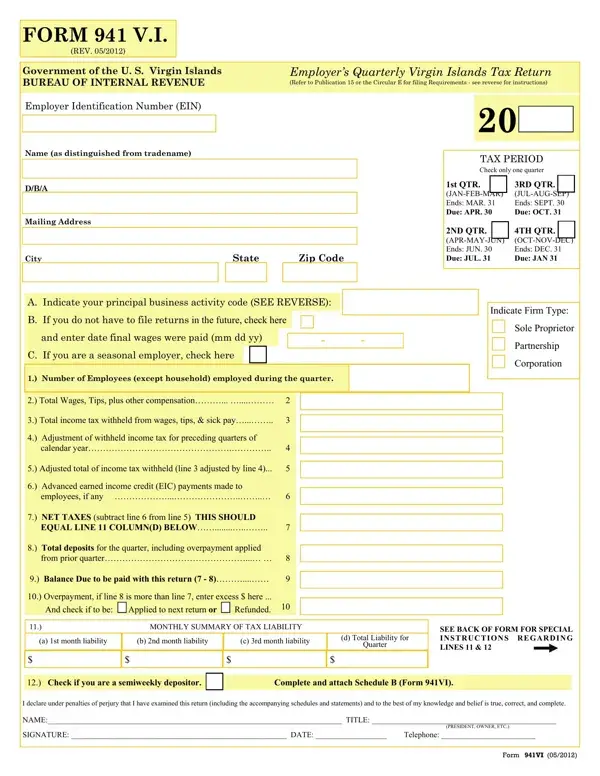
What it is: Form 941 V.I. is the Employer's Quarterly Virgin Islands Tax Return of the Government of the U. S. Virgin Islands Bureau of Internal Revenue.
Who signs: Enter the NAME, the TITLE (PRESIDENT, OWNER, ETC.), the SIGNATURE, the DATE and the Telephone.
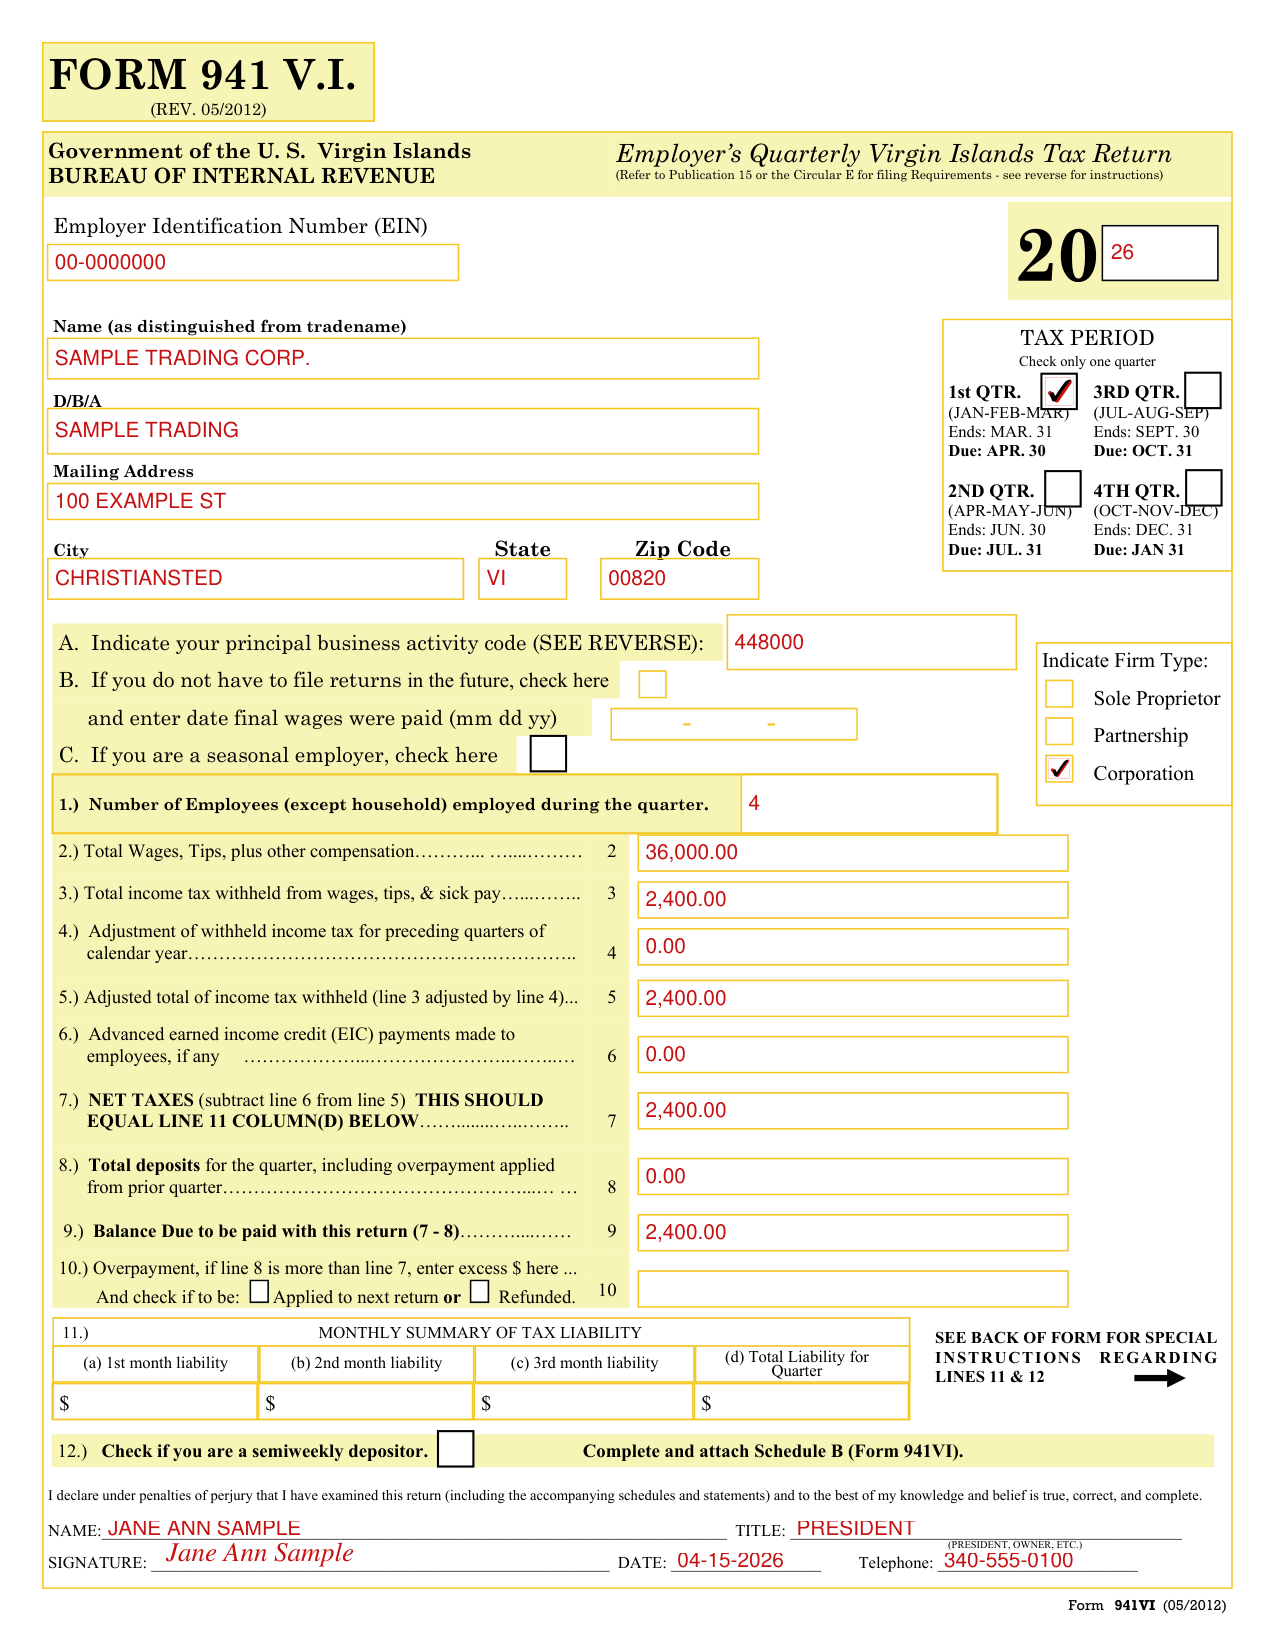
A filled-in Form 941 V.I. example: a first quarter return with no deposits
How to fill out Form 941 V.I., box by box
Employer, tax period and mailing address
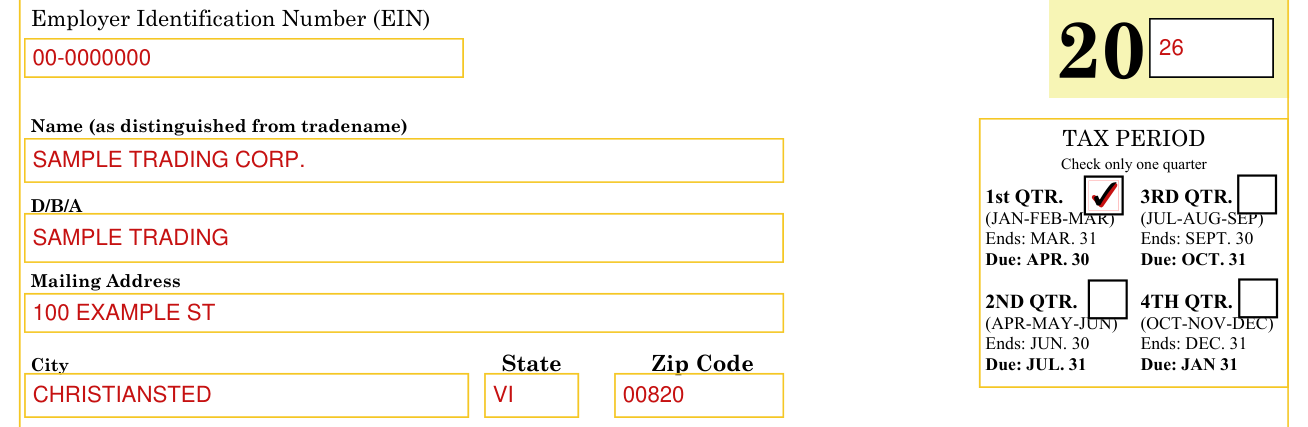
Enter the Employer Identification Number (EIN), the Name (as distinguished from tradename), the Mailing Address, City, State and Zip Code.
Under TAX PERIOD, check only one quarter: 1st QTR. (JAN-FEB-MAR) Ends: MAR. 31 Due: APR. 30, 2ND QTR. (APR-MAY-JUN) Ends: JUN. 30 Due: JUL. 31, 3RD QTR. (JUL-AUG-SEP) Ends: SEPT. 30 Due: OCT. 31, or 4TH QTR. (OCT-NOV-DEC) Ends: DEC. 31 Due: JAN 31.
Business activity code and firm type
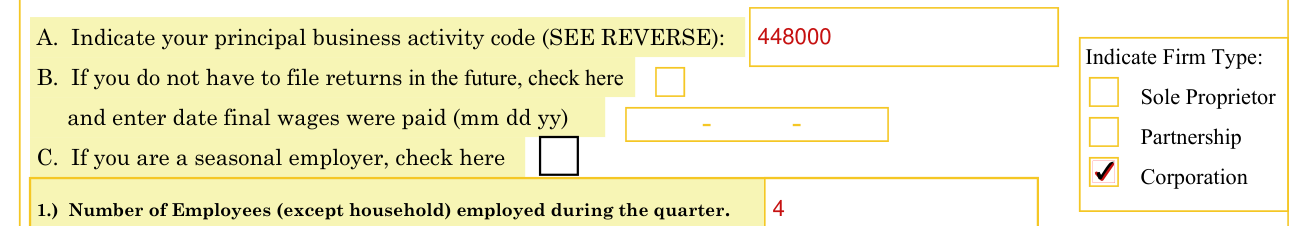
A. Indicate your principal business activity code (SEE REVERSE): select only one code from the Bureau of Internal Revenue Codes for Principal Business Activity and Principal Products or Services and enter it on front of form.
Indicate Firm Type: Sole Proprietor, Partnership or Corporation.
Final return and seasonal employer
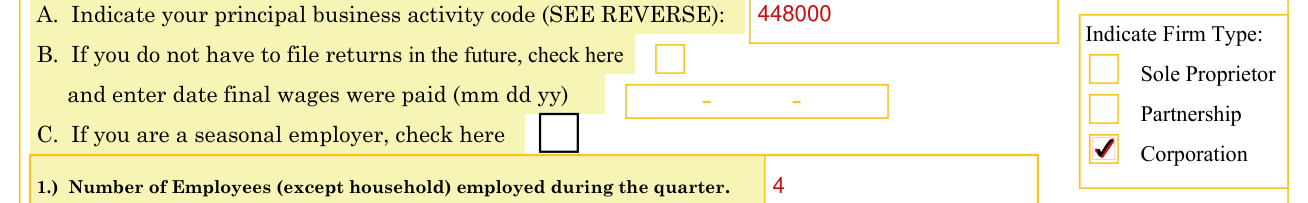
B. If you do not have to file returns in the future, check here and enter date final wages were paid (mm dd yy).
C. If you are a seasonal employer, check here.
Employees, wages and income tax withheld
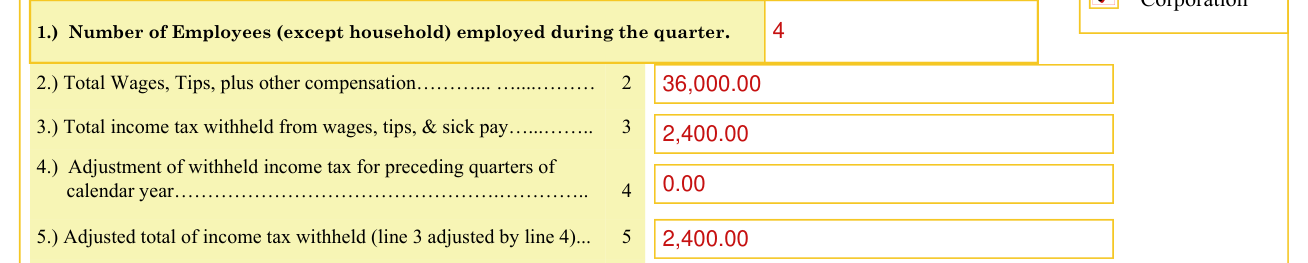
1.) Enter the number of employees (except household) on your payroll during the quarter. Do not include household employees and persons not compensated during the Quarter.
2.) Enter the total of all wages paid, tips reported, taxable fringe benefits provided and other compensation paid to employees, even if you do not have to withhold income taxes on it.
3.) Enter the income tax you withheld on wages, tips, and taxable fringe benefits.
4.) Use this line to correct errors in income tax withheld from wages paid in earlier quarters for the same calendar year. Do not use this line to adjust or to claim a refund or credit for any overpayment of income tax that you withheld or deducted from an employee in a prior year. Because any amount shown on this line increases or decreases your tax liability, the adjustment must be taken into account on line 11 Monthly Summary of Tax Liability.
You are required to provide background information and documentation supporting prior quarter adjustments or attach a statement that shows: (1) What the error was, (2) Quarter in which the error was made, (3) The amount of the error each quarter and (4) Date in which you found the error.
5.) Adjusted total of income tax withheld (line 3 adjusted by line 4): add line 4 to line 3 if you are reporting additional income tax withheld for an earlier quarter. Subtract line 4 from line 3 if you are reducing the amount of income tax withheld. If there is no entry on line 4, enter amount from line 3.
Advance EIC, net taxes, deposits and balance due
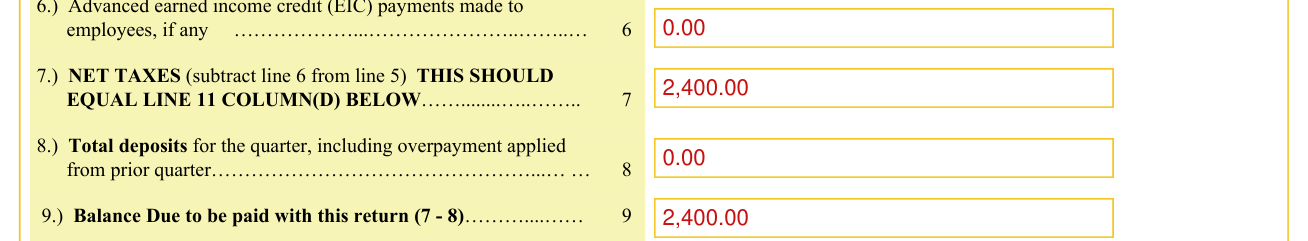
6.) Enter advance EIC payments made to employees, if any. Eligible employees may elect to receive part of the EIC as an advance payment.
7.) NET TAXES: subtract line 6 from line 5. This should equal line 11 column (d).
8.) Enter the total deposits made during the quarter and any overpayments from preceding quarters.
9.) Balance Due to be paid with this return (7 - 8). You should have a balance due only if your net tax liability for the quarter (line 7) is less than $2,500 (However, see Publication 15 or the Circular E regarding payments made under the accuracy of deposits rule) (checked November 2, 2026). If line 7 is $2,500 or more and you have deposited all taxes when due, the amount on line 9 (balance due) should be zero (checked November 2, 2026).
Overpayment
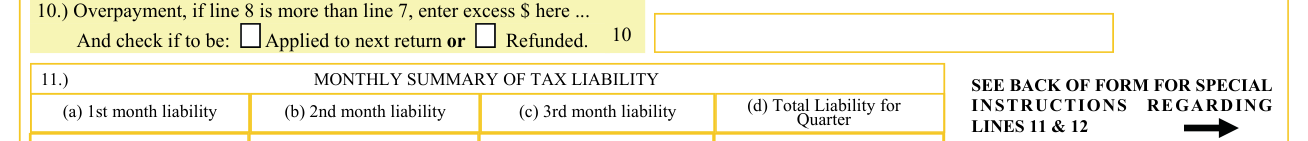
10.) If you deposited more than the correct amount for the quarter, indicate that amount in the space provided (Overpayment, if line 8 is more than line 7). This overpayment can be refunded or applied to your next return by checking the appropriate box. If you do not check either box, your overpayment will be applied to your next return. The VI BIR may apply your overpayments to any past due tax accounts.
Monthly summary of tax liability and semiweekly depositor
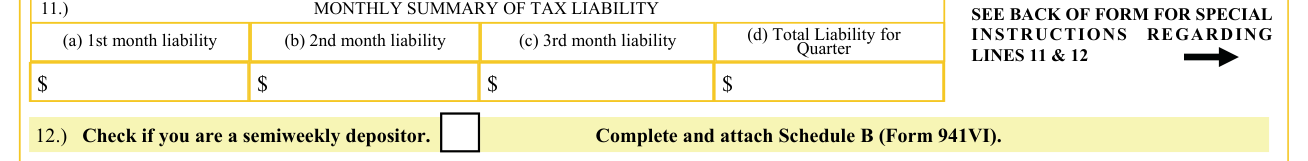
11.) MONTHLY SUMMARY OF TAX LIABILITY: complete line 11 if you are a monthly schedule depositor (see Circular E for details on deposit rules), with (a) 1st month liability, (b) 2nd month liability, (c) 3rd month liability and (d) Total Liability for Quarter. This should be a summary of your tax liability, not a summary of deposits made.
If line 7 is less than $2,500, do not complete line 11 (checked November 2, 2026).
12.) Check if you are a semiweekly depositor. Complete and attach Schedule B (Form 941VI).
Declaration and signature

You declare under penalties of perjury that you have examined this return (including the accompanying schedules and statements) and to the best of your knowledge and belief is true, correct, and complete.
Enter the NAME, the TITLE (PRESIDENT, OWNER, ETC.), the SIGNATURE, the DATE and the Telephone.
Common questions about Form 941 V.I.
What is form 941?
Form 941 V.I. is the Employer's Quarterly Virgin Islands Tax Return of the Government of the U. S. Virgin Islands Bureau of Internal Revenue. Refer to Publication 15 or the Circular E for filing Requirements - see reverse for instructions.
Sources
[1] Form 941 V.I. (05/2012), Government of the U. S. Virgin Islands Bureau of Internal Revenue (the Official source link on this page).