

Form ST-121.2 at a glance
What it is: Form ST-121.2 is the Department of Taxation and Finance New York State and Local Sales and Use Tax Exemption Certificate for Purchases of Promotional Materials.
Where and when to file: The purchaser completes the form and gives it to the vendor; complete all required entries (see instructions).
If you are purchasing promotional materials, or services relating to promotional materials, you must complete this form and give it to the vendor to certify the percentage of the purchase that is exempt from sales tax.
A filled-in Form ST-121.2 example: a shop buys printed catalogs free of sales tax
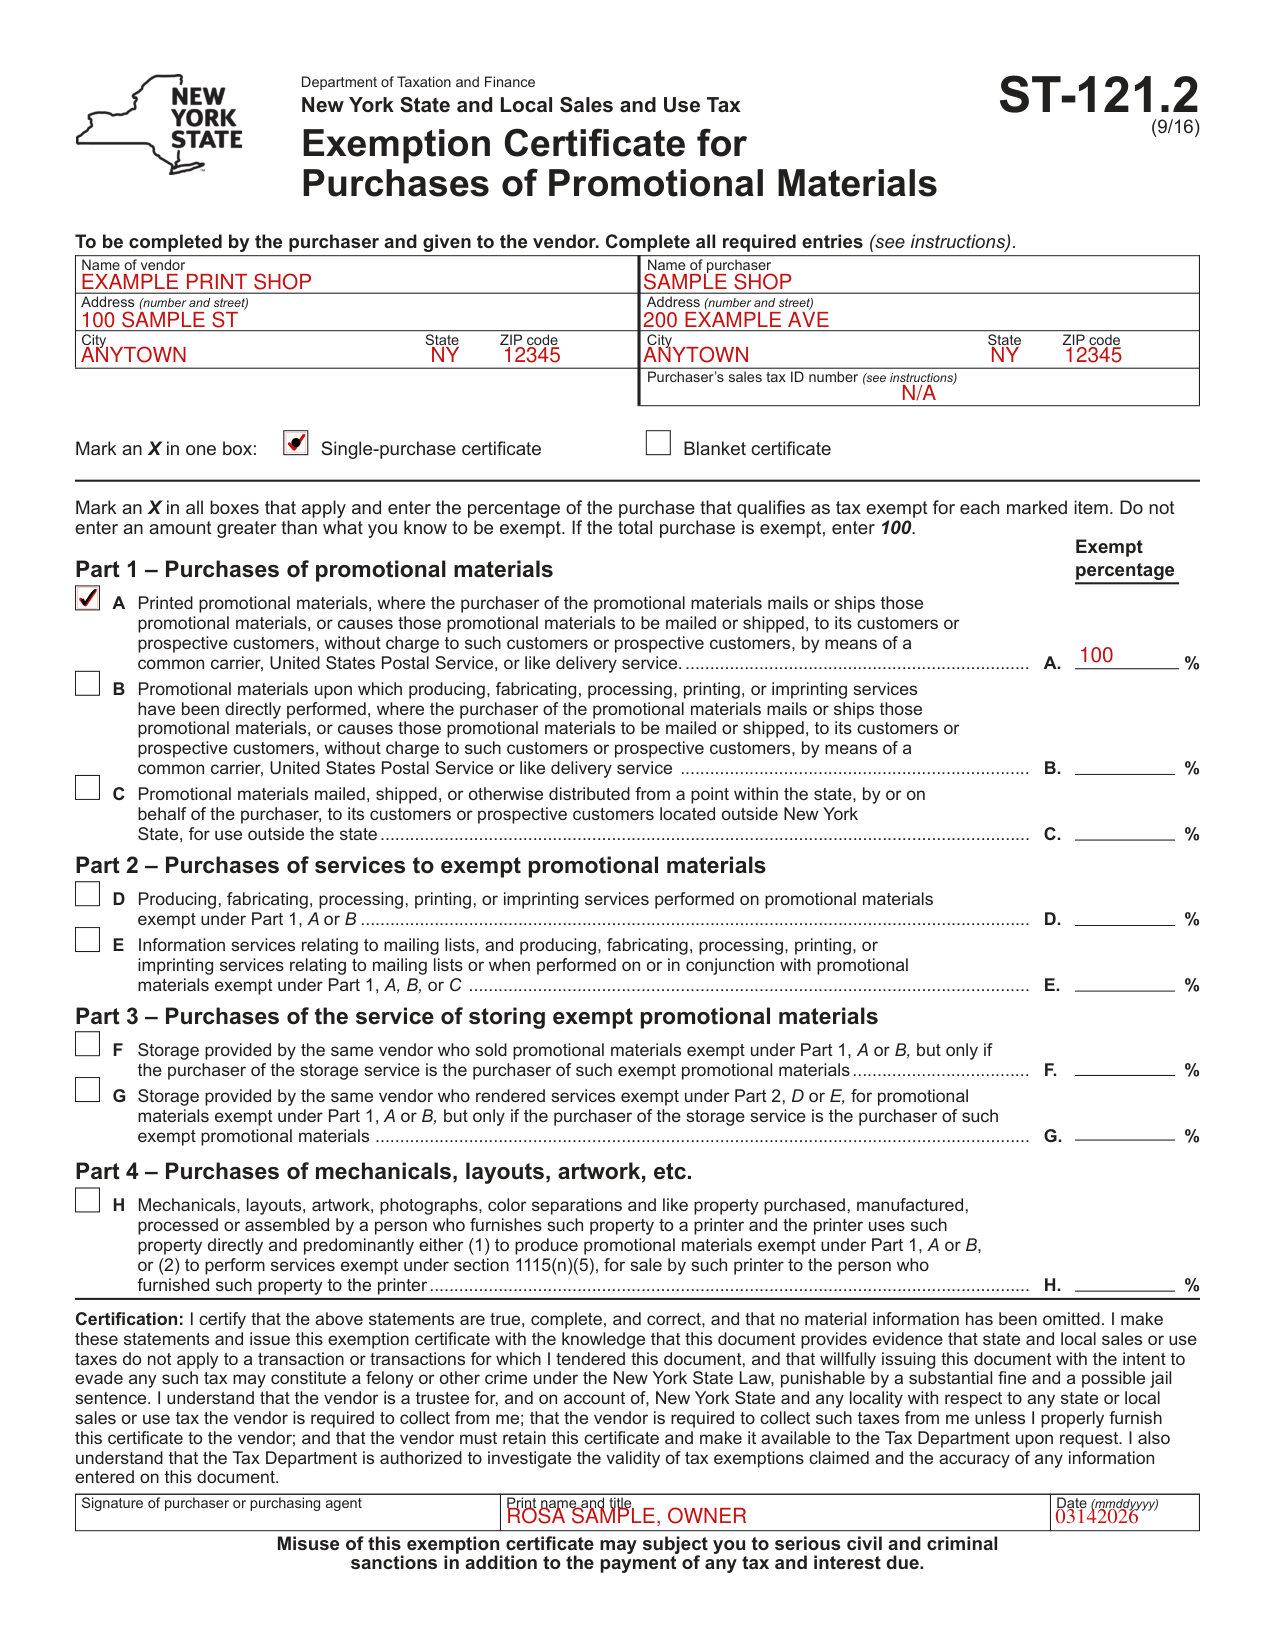
How to fill out Form ST-121.2, box by box
Name of vendor and Name of purchaser
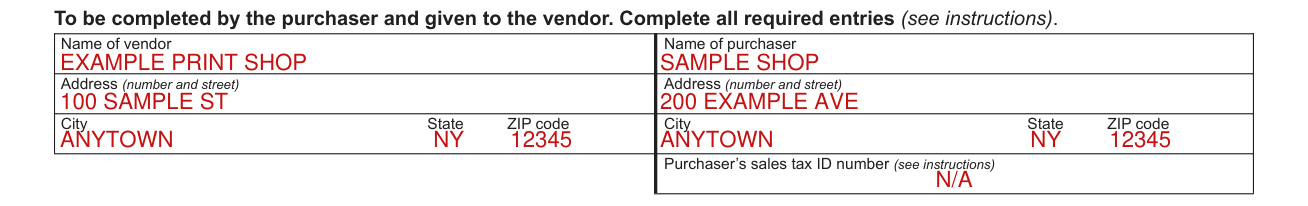
Fill in Name of vendor and Name of purchaser, then each Address (number and street), then each City, State and ZIP code.
Purchaser's sales tax ID number

Enter the Purchaser's sales tax ID number (see instructions).
If you are registered with the Tax Department for sales tax purposes, you must enter your sales tax identification number on this form.
If you are not required to be registered, enter N/A.
Single-purchase certificate or Blanket certificate

Mark an X in one box: Single-purchase certificate or Blanket certificate.
If you marked an X in the Blanket certificate box, you should periodically review the percentage(s). If any percentage changes, you must issue a new blanket certificate.
Part 1 - Purchases of promotional materials
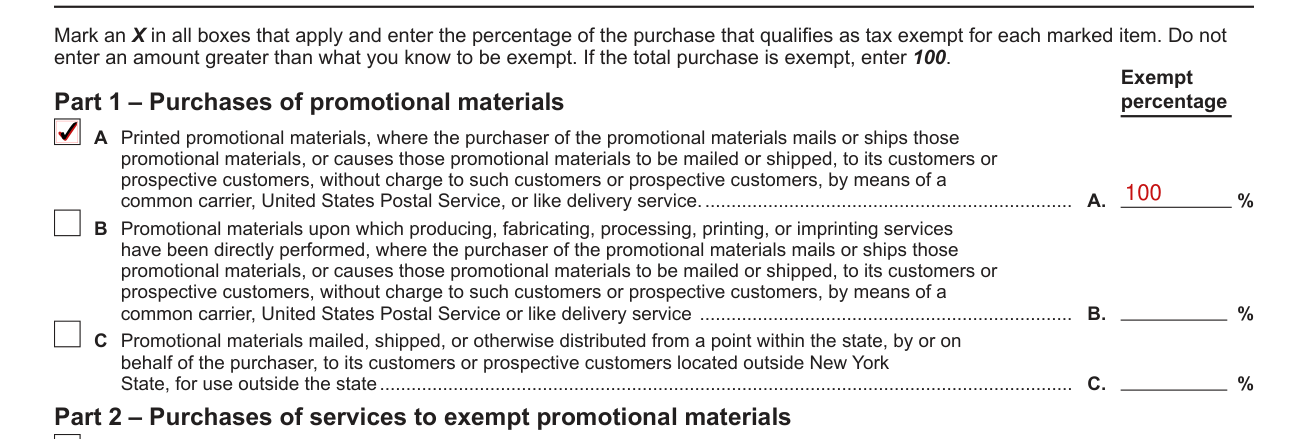
Mark an X in all boxes that apply and enter the percentage of the purchase that qualifies as tax exempt for each marked item. Do not enter an amount greater than what you know to be exempt. If the total purchase is exempt, enter 100.
Part 1 - Purchases of promotional materials: printed promotional materials include any printed materials such as catalogs, literature, and related tangible personal property (such as complimentary maps, applications, and order forms), and the envelopes used exclusively to deliver the promotional materials.
Account statements, invoices, or the envelopes used to deliver them are not promotional materials.
If you estimate too high a percentage as exempt, you must pay tax on the portion that turns out to be taxable.
If you cannot, in good faith, determine the exempt percentage, you must pay tax at the time of purchase and request a refund.
Part 2 - Purchases of services to exempt promotional materials
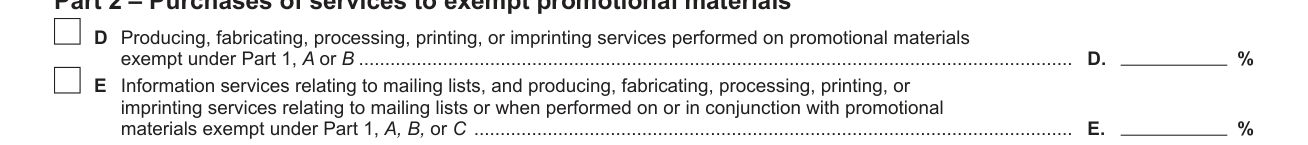
Part 2 - Purchases of services to exempt promotional materials: other purchases exempt from sales tax include information services relating to mailing lists, and producing, fabricating, processing, printing, or imprinting services relating to mailing lists or when performed on or in conjunction with exempt promotional materials (including merging names, labeling envelopes, and similar services).
Part 3 - Purchases of the service of storing exempt promotional materials
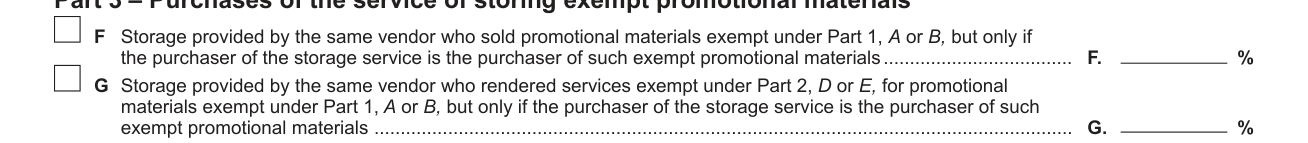
Part 3 - Purchases of the service of storing exempt promotional materials: the purchaser of promotional materials exempt as described in Part 1, A or B, may also purchase certain storage charges exempt from tax if the charges are for storing exempt promotional materials and the storage is provided by the same vendor who sold the exempt printed promotional materials, or by the same vendor who rendered exempt services to the promotional materials, as described in Part 2, D or E. Storage of other promotional materials is taxable.
Part 4 - Purchases of mechanicals, layouts, artwork, etc.
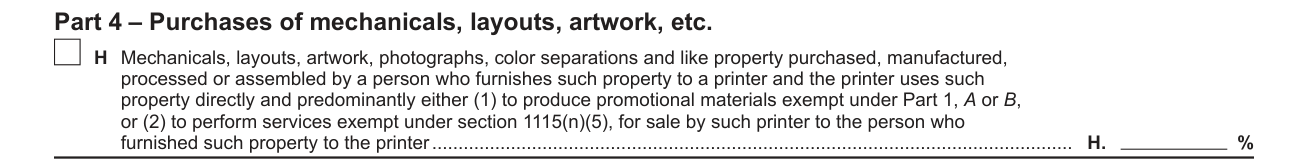
Part 4 - Purchases of mechanicals, layouts, artwork, etc.: paper, ink, artwork, mechanicals, and other supplies that you purchase and furnish to the printer are exempt if the printer uses them to produce and sell to you promotional materials exempt under Part 1, A or B.
Signature of purchaser or purchasing agent, Print name and title and Date
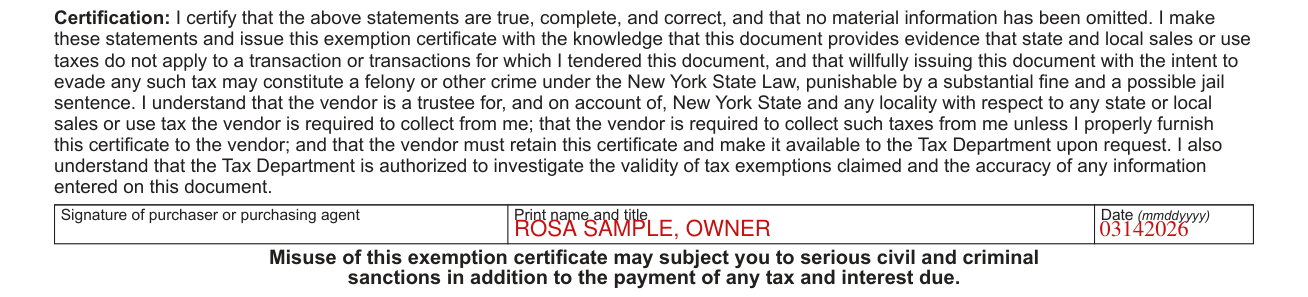
Sign as the Signature of purchaser or purchasing agent, then enter Print name and title and Date (mmddyyyy).
Misuse of this exemption certificate may subject you to serious civil and criminal sanctions in addition to the payment of any tax and interest due.
Common questions about Form ST-121.2
Is there a deadline?
The purchaser must give the vendor Form ST-121.2 with all required entries completed no later than 90 days after delivery of the property or services sold, or the sale will be deemed to have been taxable at the time of the transaction.
Sources
[1] Form ST-121.2 (9/16), New York State and Local Sales and Use Tax Exemption Certificate for Purchases of Promotional Materials, New York State Department of Taxation and Finance (the Official source link on this page).