


Form IHT205 at a glance
What it is: IHT205 is the HMRC form Return of estate information.
Who signs: By signing you declare that the information given on this form is correct and complete. Enter Name, Address and Postcode, sign on the Signature line and enter Date DD MM YYYY.
Fill in this form where the person who has died (‘the deceased') was domiciled (had their permanent home) in the UK at the date of death and the gross value of the estate for Inheritance Tax is less than or equal to: the excepted estate limit; twice the excepted estate limit and form IHT217 ‘Claim to transfer unused nil rate band for excepted estates' is attached; or £1 million and there is no Inheritance Tax to pay because of spouse, civil partner or charity exemption.
Fill in this version of this form only when the person died on or after 6 April 2011 and on or before 31 December 2021.
A filled-in Form IHT205 example: an executor fills in page 1 for a late father
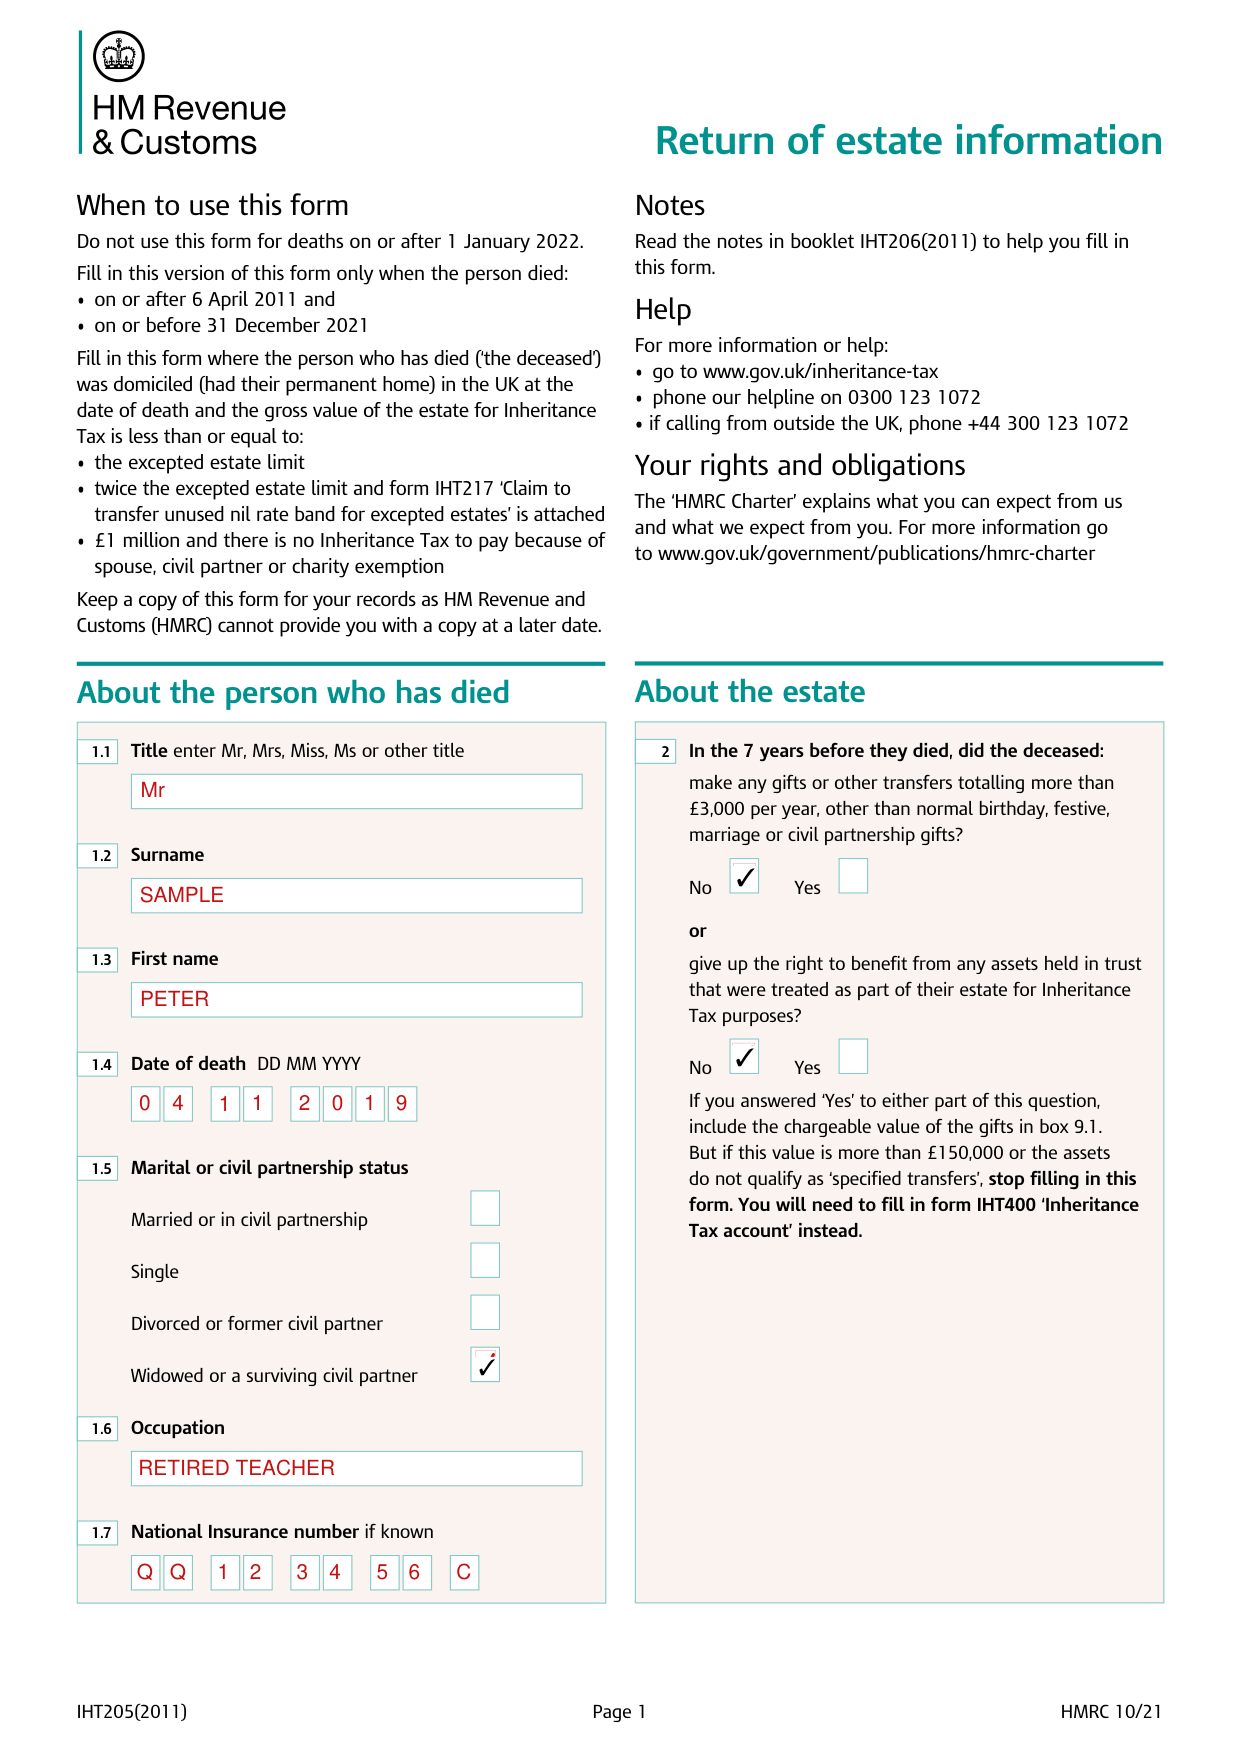
How to fill out Form IHT205, box by box
Title, name, date of death, occupation and National Insurance number
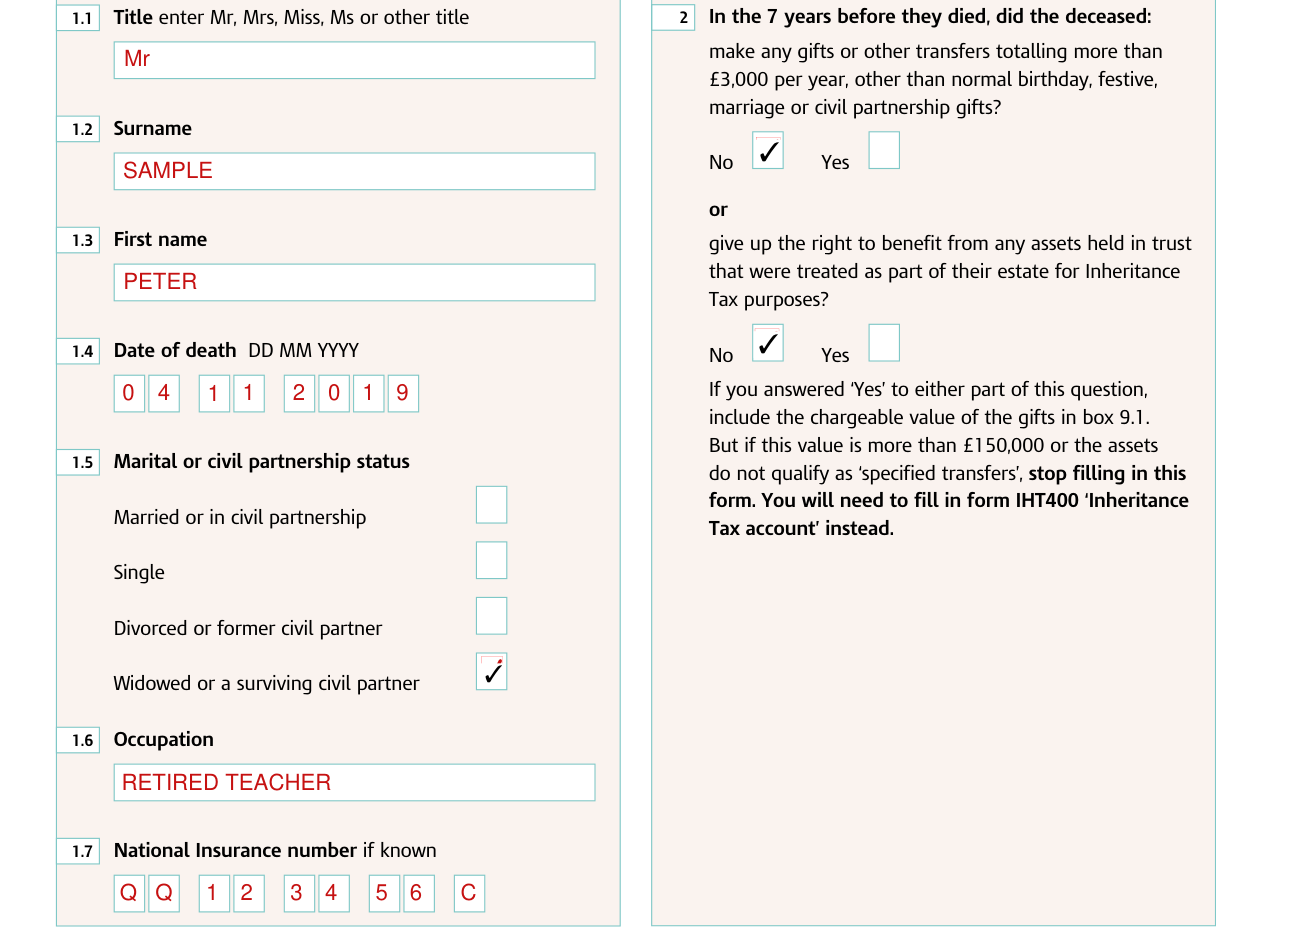
Under 1.1 Title, enter Mr, Mrs, Miss, Ms or other title.
Enter 1.2 Surname, 1.3 First name and 1.4 Date of death as DD MM YYYY.
Enter 1.6 Occupation and 1.7 National Insurance number if known.
Marital or civil partnership status
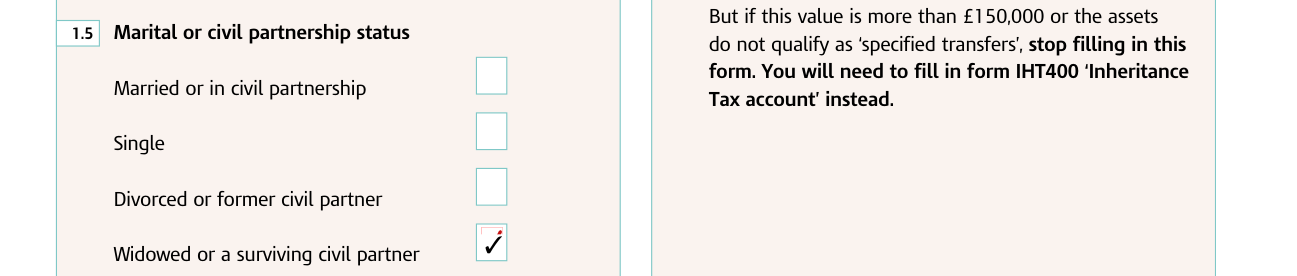
For 1.5 Marital or civil partnership status, mark Married or in civil partnership, Single, Divorced or former civil partner, or Widowed or a surviving civil partner.
2 Gifts and other transfers in the 7 years before they died
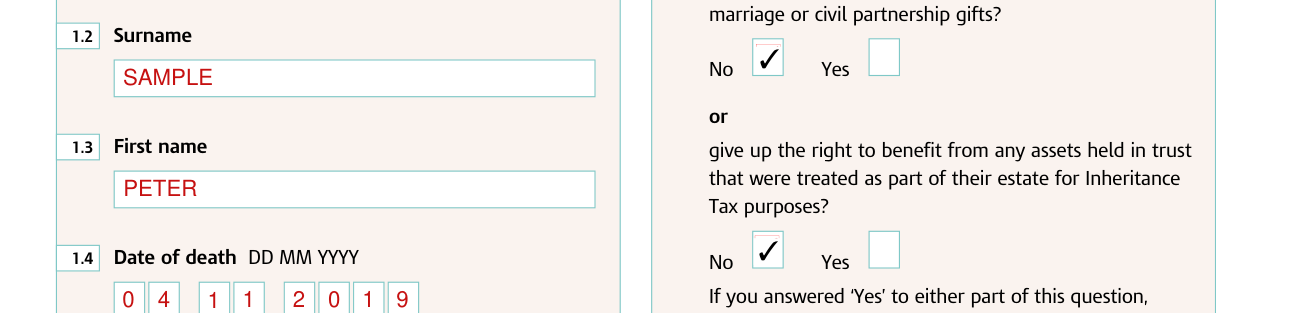
2 In the 7 years before they died, did the deceased make any gifts or other transfers totalling more than £3,000 per year, other than normal birthday, festive, marriage or civil partnership gifts? Or did the deceased give up the right to benefit from any assets held in trust that were treated as part of their estate for Inheritance Tax purposes? (checked November 8, 2026)
If you answered ‘Yes' to either part of this question, include the chargeable value of the gifts in box 9.1. But if this value is more than £150,000 or the assets do not qualify as ‘specified transfers', stop filling in this form (checked November 8, 2026). You will need to fill in form IHT400 ‘Inheritance Tax account' instead.
Questions 3 to 8: when to stop and fill in IHT400
3 Did the deceased make any of the following: a gift, on or after 18 March 1986, where they continued to benefit from, or had some right to benefit from, or use all or part of the asset? Or a gift, on or after 18 March 1986, where the person receiving the gift did not take full possession of it? Or an election on form IHT500 ‘Election for Inheritance Tax to apply to asset previously owned' that an Income Tax charge should not apply to: assets they previously owned, in which they retained a benefit, or the deceased's contribution to the purchase price of assets acquired by another person, but in which the deceased retained a benefit? If you answered ‘Yes' to any part of this question, stop filling in this form and fill in form IHT400 instead.
4 Did the deceased have the right to receive the benefit from any assets held in a trust that were treated as part of their estate for Inheritance Tax purposes? If you answered ‘Yes', and the deceased was entitled to benefit from a single trust, and the value of the assets in that trust, treated as part of their estate, was less than or equal to £150,000, include the value of the trust assets in box 9.3. But if the value was more than £150,000 (checked November 8, 2026), or there was more than one trust, stop filling in this form and fill in form IHT400 instead.
5 Did the deceased own or benefit from any assets outside the UK? If you answered ‘Yes', include the value of the overseas assets in box 9.5. But if the value of the overseas assets is more than £100,000 (checked November 8, 2026), stop filling in this form and fill in form IHT400 instead.
6 Did the deceased pay premiums on any life insurance policies that were not for their own benefit or did not pay out to the estate, and did they buy an annuity at any time? Ignore any policies paid out to a surviving spouse or civil partner. If you answered Yes, stop filling in this form. You will need to fill in form IHT400 instead.
7 Did the deceased have any kind of pension arrangement other than the State Pension? If you answered ‘No', go to the next section ‘Deceased's assets at the date of death'.
8 Did the deceased change or dispose of their pension in the 2 years before they died? Ignore any pensions paid to a surviving spouse or civil partner. If you answered ‘Yes' to this question, stop filling in this form and fill in form IHT400 instead.
Assets for which a grant is not required (boxes 9.1 to 9.5 and A)
Box 9.1 is for gifts and other lifetime transfers (after deduction of allowable exemptions) made in the 7 years before they died.
Box 9.2 is for the deceased's share of joint assets passing automatically to the surviving joint owner even if they are the husband, wife or civil partner.
Box 9.3 is for assets held in trust for the benefit of the deceased during their lifetime. Box 9.4 is for nominated assets.
Box A is the gross value of assets for which a grant is not required (add together the figures in boxes 9.1 to 9.5).
Debts payable out of assets in boxes 9.1 to 9.5 (boxes 10.1 to 10.4, B and C)
Box B is the total debts payable out of assets in boxes 9.1 to 9.5 (add together boxes 10.1 to 10.4).
Box C is the net value of assets for which a grant is not required (box A minus box B) (this value may be nil).
Assets for which a grant of representation is required (boxes 11.1 to 11.11 and D)
For the deceased's own assets for which a grant of representation is required, include the gross value for each item before deduction of any exemptions or reliefs.
Boxes 11.1 to 11.11 are for cash, stocks and shares, insurance policies, the freehold/leasehold residence and other land and buildings, and, in box 11.11, “any other assets not included above”.
Box D is the gross value of assets for which a grant is required (add together boxes 11.1 to 11.11) (read IHT206(2011) ‘Notes' page 22).
Debts of the estate and the net estate (boxes 12.1 to 12.3 and E to H)
Box E is the total debts payable out of assets in boxes 11.1 to 11.11 (add together boxes 12.1 to 12.3).
Box F is the net estate in the UK for the grant of representation (box D minus box E).
Box G is the net estate for Inheritance Tax purposes (box C + box F).
Exemptions (boxes J and K)
In box J, enter the value of any exemption for assets passing on death to either the surviving spouse or civil partner of the deceased or a qualifying charity or for national purposes. Do not include agricultural or business relief here.
Box K is the net qualifying value for excepted estates (box G minus box J) (this value may be nil). “If the value in box K is above the excepted estate limit, you must fill in form IHT400 ‘Inheritance Tax account' unless you are claiming a transfer of unused nil rate band.”
If you're claiming a transfer of unused nil rate band, you must attach a completed form IHT217 ‘Claim to transfer unused nil rate band for excepted estates' to this form.
Declaration
In the declaration, tick one box to say the gross value of the estate for Inheritance Tax (see box H on page 5) is less than or equal to: the excepted estate limit. Or twice the excepted estate limit and a claim to transfer unused nil rate band (form IHT217) is attached. Or £1 million and there is no Inheritance Tax to pay because of spouse, civil partner or charity exemption (checked November 8, 2026).
More rules for Form IHT205
Read the notes in booklet IHT206(2011) to help you fill in this form.
Keep a copy of this form for your records as HM Revenue and Customs (HMRC) cannot provide you with a copy at a later date.
Make the fullest enquiries so that you can show that the figures on this form are correct. If you cannot find the value for an item, you may include your best estimate.
Common questions about Form IHT205
When is this form not the right one?
Do not use this form for deaths on or after 1 January 2022.
Sources
[1] Form IHT205 (2011), Return of estate information, HM Revenue and Customs (the Official source link on this page).