
Form 14402 at a glance
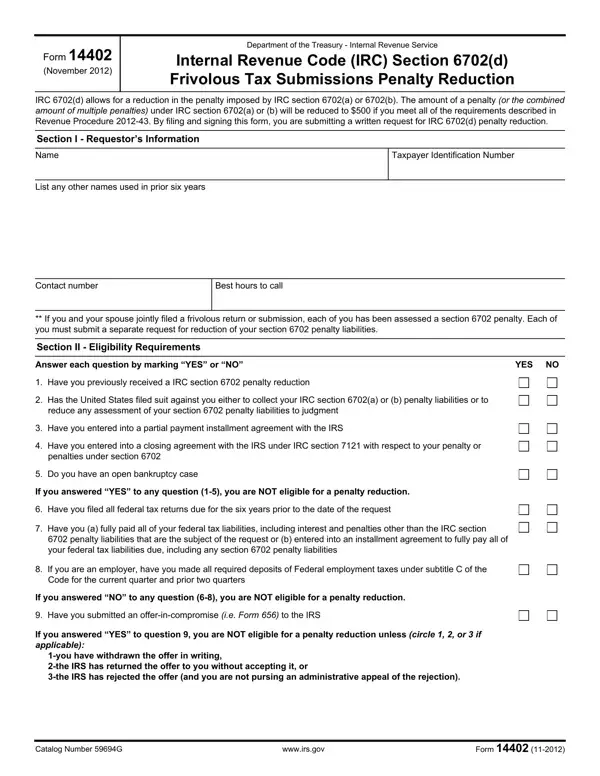
What it is: This is the Department of the Treasury - Internal Revenue Service Internal Revenue Code (IRC) Section 6702(d) Frivolous Tax Submissions Penalty Reduction form.
Who signs: Under Section V - Declaration Under Penalties Of Perjury, sign and enter the Date signed.
Where and when to file: To request a reduction of your unpaid section 6702 penalty liabilities, you must mail a completed Form 14402 to the Internal Revenue Service, Frivolous Return Program, 1973 N Rulon White Blvd., M/S 4450, Ogden, UT 84404.
Use Form 14402 to request a reduction in your unpaid section 6702 penalty liabilities (page 3 of Form 14402, 11-2012, Catalog Number 59694G). Any person may use it for any unpaid section 6702 penalty liabilities.
A filled-in Form 14402 example: a filer asks for a penalty reduction
How to fill out Form 14402, box by box
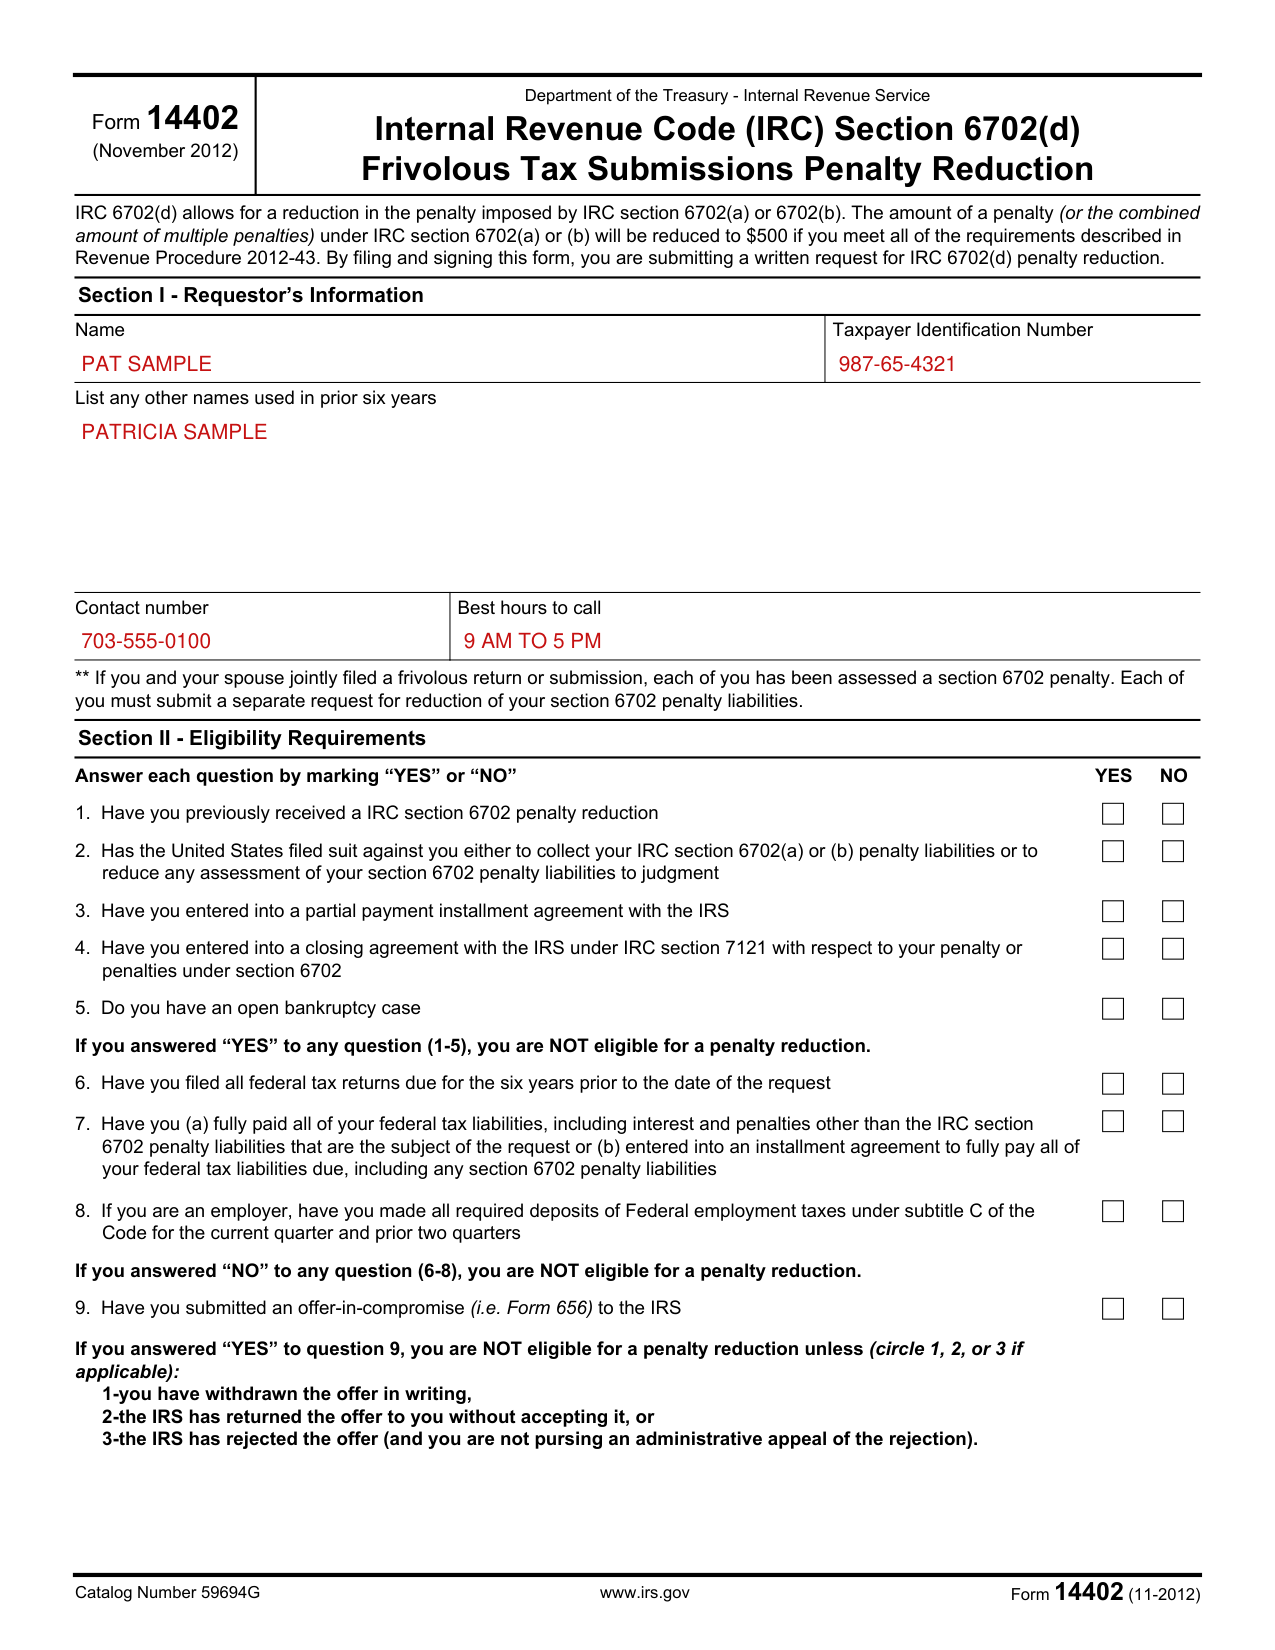
Section I - Requestor's Information
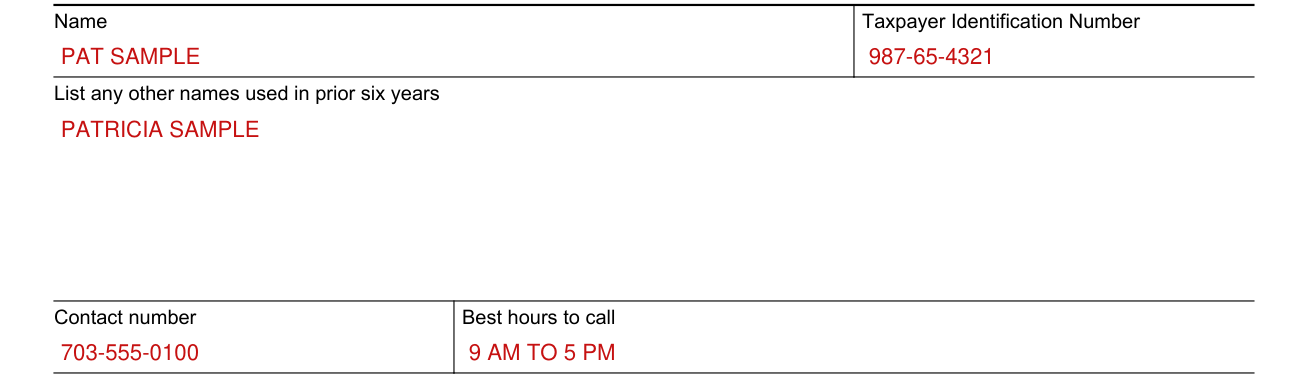
Provide your name, Social Security Number (SSN) or other Tax Identification Number, and contact information so your account can be accessed and you can be contacted if any of the information you provide on the form needs to be clarified.
If you and your spouse jointly filed a frivolous return or submission, each of you has been assessed a section 6702 penalty. Each of you must submit a separate request for reduction of your section 6702 penalty liabilities.
List any other names used in prior six years.
Enter the Contact number and the Best hours to call.
Section II - Eligibility Requirements
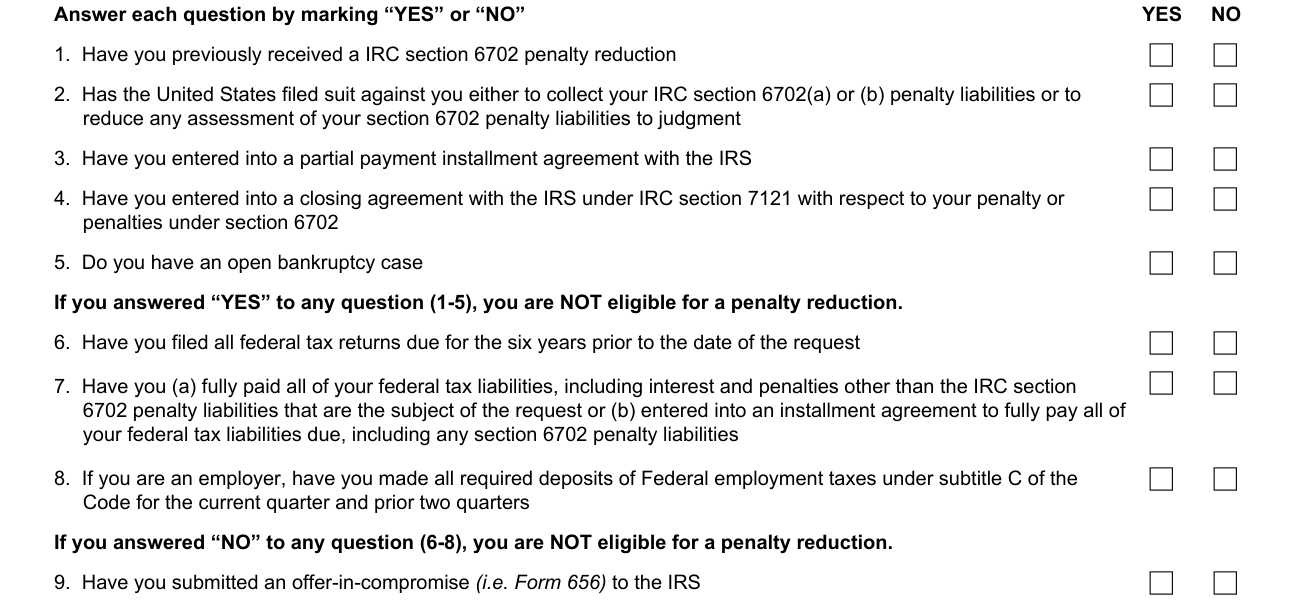
Answer each question by marking “YES” or “NO”. You must check either “YES” or “NO” to every question in this section to determine whether you meet the requirements described in Revenue Procedure 2012-43.
Question 1, Have you previously received a IRC section 6702 penalty reduction: if any of your section 6702 penalty liabilities have previously been reduced, then you are not eligible for another reduction of any section 6702 penalty liabilities.
Question 2: if the United States has filed suit against you either to collect your section 6702 penalty liabilities or to reduce any assessment of your section 6702 penalty liabilities to judgment, then you are not eligible for a section 6702 penalty reduction. Unless you have been served a complaint filed by the Department of Justice in United States District Court to collect your unpaid tax liabilities, you should check “NO” to this question.
Question 3: if you have entered into a partial payment installment agreement, then you are not eligible for a section 6702 penalty reduction because successful completion of the agreement will result in you paying less than the full amount of your federal tax liabilities.
Question 4: if you have entered into a closing agreement with the IRS under section 7121 (for example, Form 906, Closing Agreement on Final Determination Covering Specific Matters) with respect to your section 6702 penalty liabilities, then you are not eligible for a section 6702 penalty reduction.
Question 5: if you have an open bankruptcy case, then you are not eligible for a section 6702 penalty reduction.
If you answered “YES” to any question (1-5), you are NOT eligible for a penalty reduction.
Have you filed all federal tax returns due for the six years prior to the date of the request? This requirement means a person must file all individual returns and all returns for any entity in which the person has a controlling interest.
Question 7: you are not eligible for a section 6702 penalty reduction unless you have paid all your federal tax liabilities other than section 6702 penalties and interest thereon or you have entered into an installment agreement to fully pay all your federal tax liabilities including the section 6702 penalty liabilities.
Question 8: if you are an employer that has not made all required deposits of Federal employment taxes under subtitle C of the Code for the current quarter and the prior two quarters, then you are not eligible for a section 6702 penalty reduction.
If you answered “NO” to any question (6-8), you are NOT eligible for a penalty reduction.
Question 9, Have you submitted an offer-in-compromise (i.e. Form 656) to the IRS: if you answered “YES” to question 9, you are NOT eligible for a penalty reduction unless (circle 1, 2, or 3 if applicable): 1-you have withdrawn the offer in writing, 2-the IRS has returned the offer to you without accepting it, or 3-the IRS has rejected the offer (and you are not pursing an administrative appeal of the rejection).
Section III - Payment Information
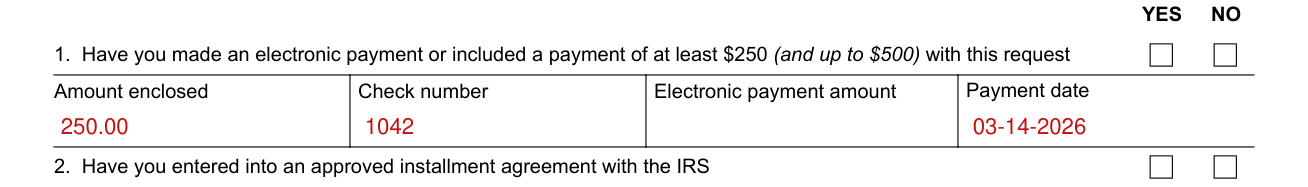
Section III - Payment Information: the minimum payment is $250.00 unless you are in compliance with a full payment installment agreement. You must pay this $500 balance in one of two ways. (checked November 17, 2026)
1. Have you made an electronic payment or included a payment of at least $250 (and up to $500) with this request: you may submit a payment of at least $250 (but not more than $500) with your request for reduction, or a payment of the entire $500 balance. Enter the Amount enclosed, Check number, Electronic payment amount and Payment date. (checked November 17, 2026)
You must submit a payment of at least $250 with your request for reduction even if you have, prior to filing your request for reduction, paid either voluntarily or by an overpayment offset, a portion of the section 6702 penalty liabilities that are the subject of your request for reduction. (checked November 17, 2026)
Your payment will be applied to your unpaid section 6702 penalty liabilities, whether or not your request for reduction is granted. If you choose to pay less than $500 and a request for a penalty reduction is granted, you will remain liable for the remaining balance of the reduced penalties until the balance is satisfied. (checked November 17, 2026)
2. Have you entered into an approved installment agreement with the IRS: if you have entered into and are in compliance with an installment agreement to fully pay all assessed federal tax liabilities (including the section 6702 penalty liabilities) for which the period for collection under section 6502 remains open, you may pay the reduced section 6702 penalty of $500 as part of the installment agreement. (checked November 17, 2026)
If you answered “NO” to both questions 1 and 2, then you will NOT receive a reduction of your section 6702 penalty liabilities.
Section IV - Request For Penalty Reduction Relief
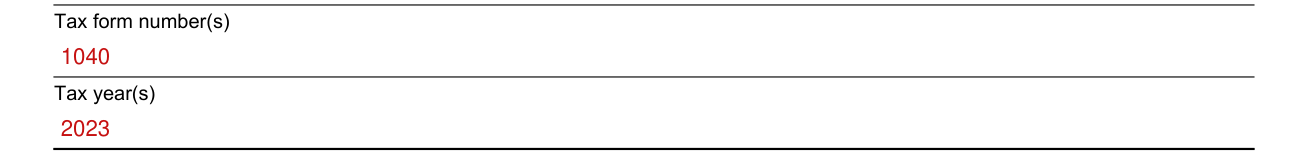
Under Section IV - Request For Penalty Reduction Relief, Requested Penalty Reduction, enter the Tax form number(s) and Tax year(s).
Section V - Declaration Under Penalties Of Perjury
Under Section V - Declaration Under Penalties Of Perjury, sign and enter the Date signed.
Under penalties of perjury, I declare that I have filed all returns (including any accompanying schedules and statements) and paid or entered into a full payment installment agreement to pay all taxes and liabilities as described in Revenue Procedure 2012-43. To the best of my knowledge and belief, the information on this form is true, correct, and complete.
I understand that any request for reduction of my section 6702 penalty liabilities will be rejected if it does not meet all of the conditions of Revenue Procedure 2012-43, asserts positions identified as frivolous under section 6702(c), or is determined to have been made with an intention to delay or impede tax administration.
More rules for Form 14402
If you do not provide this information, your request will be denied.
The amount of a penalty (or the combined amount of multiple penalties) under IRC section 6702(a) or (b) will be reduced to $500 if you meet all of the requirements described in Revenue Procedure 2012-43. IRC 6702(d) allows for a reduction in the penalty imposed by IRC section 6702(a) or 6702(b). (checked November 17, 2026)
Common questions about Form 14402
Is there a penalty?
You may be subject to civil and criminal penalties if you provide false or fraudulent information.
When is this form not the right one?
Do not use Form 14402 if you want to challenge the merits of a section 6702 penalty assessment. Other procedures may be available to challenge the merits, such as paying the penalty and filing a refund claim or raising the issue in a Collection Due Process hearing. Do not use Form 14402 to request a refund of any section 6702 penalty liabilities that you have already paid in full or in part. If you have fully paid any assessed section 6702 penalty liabilities, you are not eligible for reduction. You should not submit this form if you have already fully paid your section 6702 liabilities because you have no outstanding section 6702 penalty liabilities to reduce.
Sources
[1] Form 14402 (11-2012), Internal Revenue Code (IRC) Section 6702(d) Frivolous Tax Submissions Penalty Reduction, Internal Revenue Service (the Official source link on this page).