
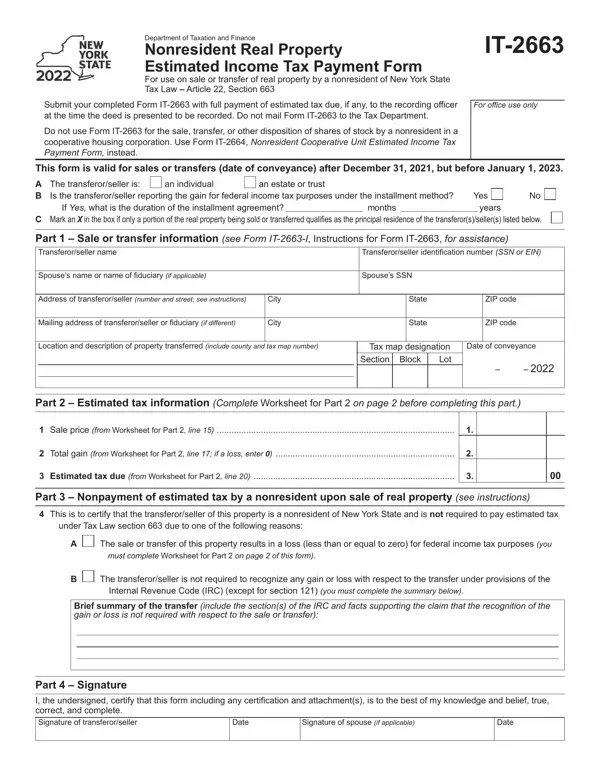

Form IT-2663 at a glance
What it is: Form IT-2663 is the Nonresident Real Property Estimated Income Tax Payment Form, for use on sale or transfer of real property by a nonresident of New York State.
Who signs: Sign (Signature of transferor/seller) and enter the Date; the spouse (if applicable) signs (Signature of spouse) and enters the Date.
A filled-in Form IT-2663 example: a nonresident pays estimated tax on a sale
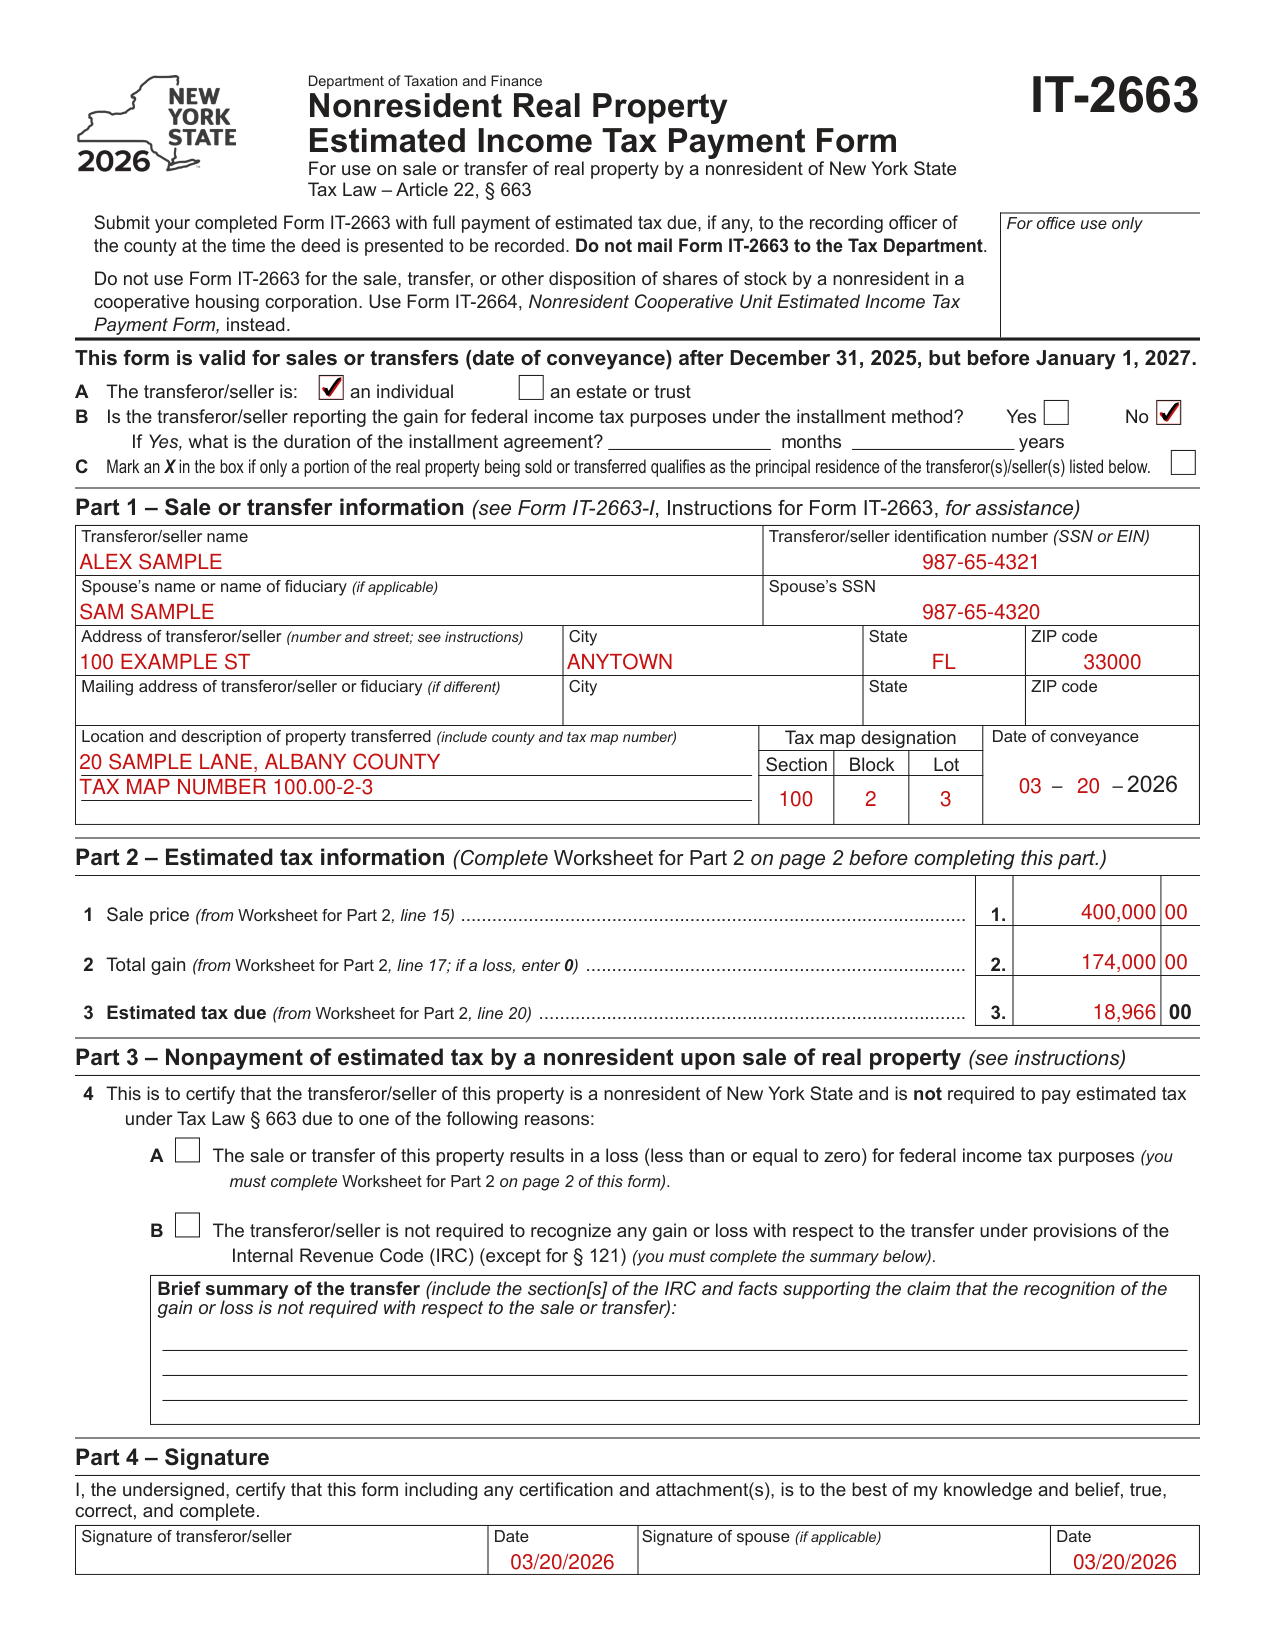
How to fill out Form IT-2663, box by box
A to C: transferor/seller, installment method and principal residence
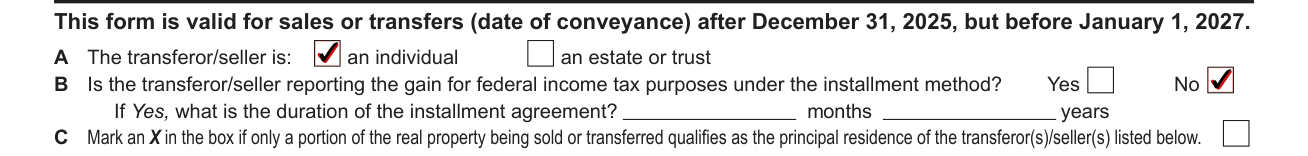
A: The transferor/seller is an individual or an estate or trust. B: Is the transferor/seller reporting the gain for federal income tax purposes under the installment method? Yes or No. If Yes, what is the duration of the installment agreement? Enter months and years. C: Mark an X in the box if only a portion of the real property being sold or transferred qualifies as the principal residence of the transferor(s)/seller(s) listed on this form.
Transferor/seller, spouse, address and mailing address (if different)
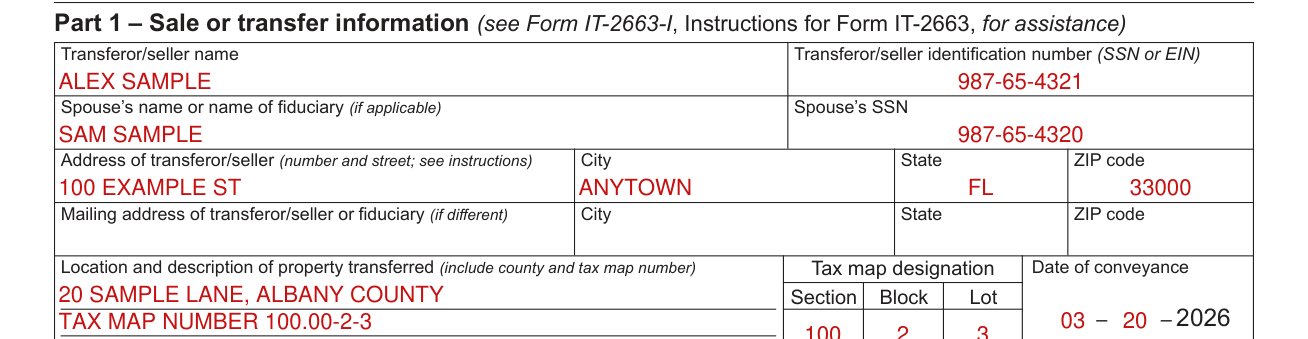
For assistance with Part 1, see Form IT-2663-I, Instructions for Form IT-2663.
Enter the transferor/seller name and the transferor/seller identification number (SSN or EIN).
Enter the spouse's name or name of fiduciary (if applicable) and the spouse's SSN.
Enter the address of transferor/seller (number and street; see instructions), city, state and ZIP code.
Enter the mailing address of transferor/seller or fiduciary (if different), city, state and ZIP code.
Location and description of property, tax map designation and date of conveyance

Enter the location and description of property transferred (include county and tax map number) and the date of conveyance.
Enter the tax map designation: Section, Block and Lot.
Part 2 - Estimated tax information
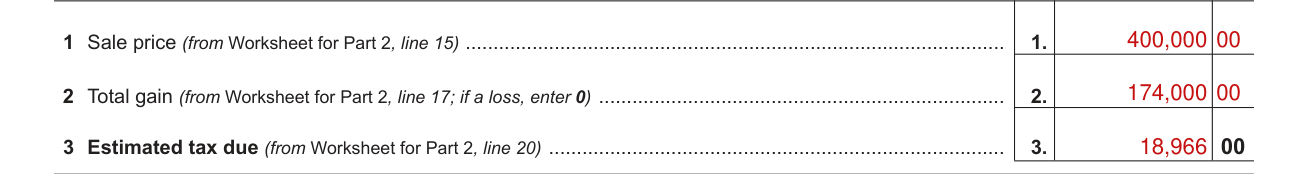
Complete Worksheet for Part 2 on page 2 before completing Part 2.
On line 1, enter the sale price from Worksheet for Part 2, line 15.
On line 2, enter the total gain from Worksheet for Part 2, line 17; if a loss, enter 0.
On line 3, enter the estimated tax due from Worksheet for Part 2, line 20.
Part 3, line 4: not required to pay estimated tax
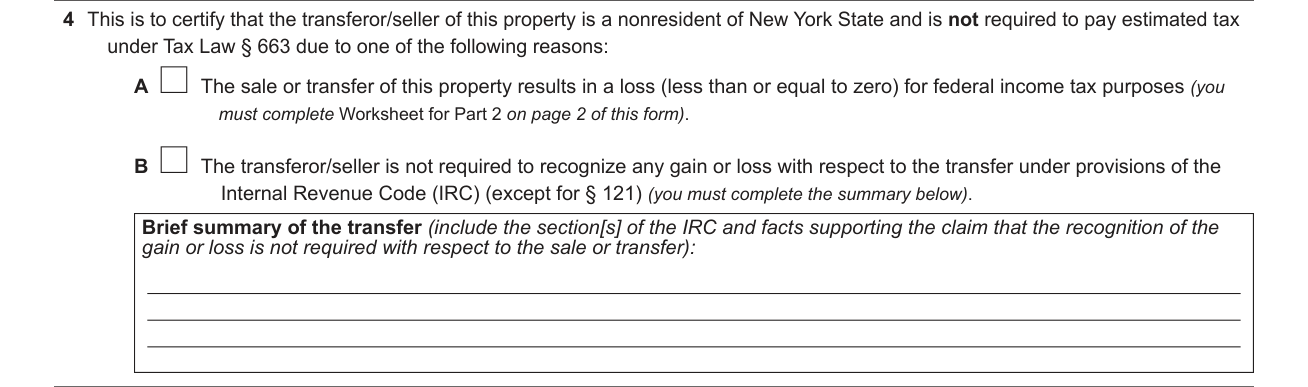
On line 4, certify that the transferor/seller of this property is a nonresident of New York State and is not required to pay estimated tax under Tax Law § 663 due to one of the following reasons.
A: The sale or transfer of this property results in a loss (less than or equal to zero) for federal income tax purposes (you must complete Worksheet for Part 2 on page 2 of this form).
B: The transferor/seller is not required to recognize any gain or loss with respect to the transfer under provisions of the Internal Revenue Code (IRC) (except for § 121) (you must complete the summary).
Enter a brief summary of the transfer (include the section[s] of the IRC and facts supporting the claim that the recognition of the gain or loss is not required with respect to the sale or transfer).
Part 4 - Signature

Certify that this form including any certification and attachment(s), is to the best of your knowledge and belief, true, correct, and complete.
Sign (Signature of transferor/seller) and enter the Date; the spouse (if applicable) signs (Signature of spouse) and enters the Date.
Lines 5 to 14: cost or other basis
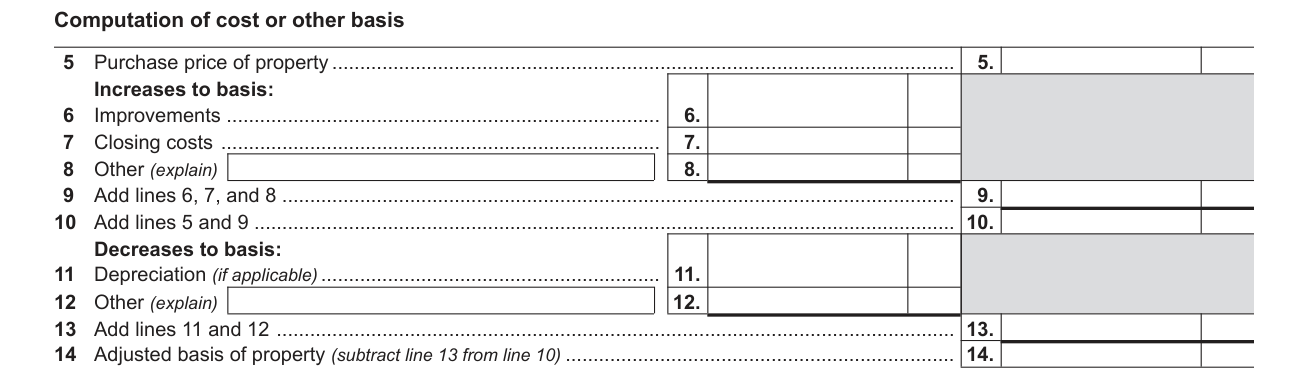
Enter the purchase price of property on line 5. Under increases to basis, enter improvements on line 6, closing costs on line 7 and other (explain) on line 8, then add lines 6, 7, and 8 on line 9. Add lines 5 and 9 on line 10. Under decreases to basis, enter depreciation (if applicable) on line 11 and other (explain) on line 12, then add lines 11 and 12 on line 13. Subtract line 13 from line 10 for the adjusted basis of property on line 14.
Lines 15 to 20: gain or loss and estimated tax due
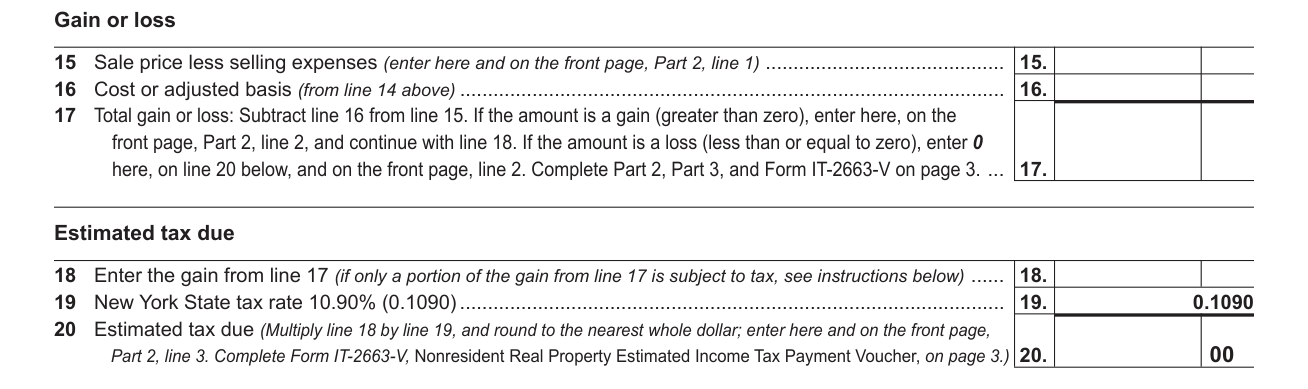
On line 15, enter the sale price less selling expenses (enter here and on the front page, Part 2, line 1). On line 16, enter the cost or adjusted basis (from line 14 above). On line 17, subtract line 16 from line 15. If the amount is a gain (greater than zero), enter here, on the front page, Part 2, line 2, and continue with line 18. If the amount is a loss (less than or equal to zero), enter 0 here, on line 20 below, and on the front page, line 2. Complete Part 2, Part 3, and Form IT-2663-V on page 3.
On line 18, enter the gain from line 17 (if only a portion of the gain from line 17 is subject to tax, see instructions below). On line 20, multiply line 18 by line 19, and round to the nearest whole dollar; enter here and on the front page, Part 2, line 3. Complete Form IT-2663-V, Nonresident Real Property Estimated Income Tax Payment Voucher, on page 3.
On line 19, when computing tax due on the gain from the transfer or sale of the real property, you must use the tax rate equal to the highest rate of tax for the tax year as set forth in the Tax Law § 601. For tax year 2026 that rate is 10.90% (0.1090).
Line 20 is the amount of your required estimated tax payment. Enter this amount on the front page, Part 2, line 3 and as your estimated tax payment on Form IT-2663-V on page 3.
Form IT-2663-V: payment and identification
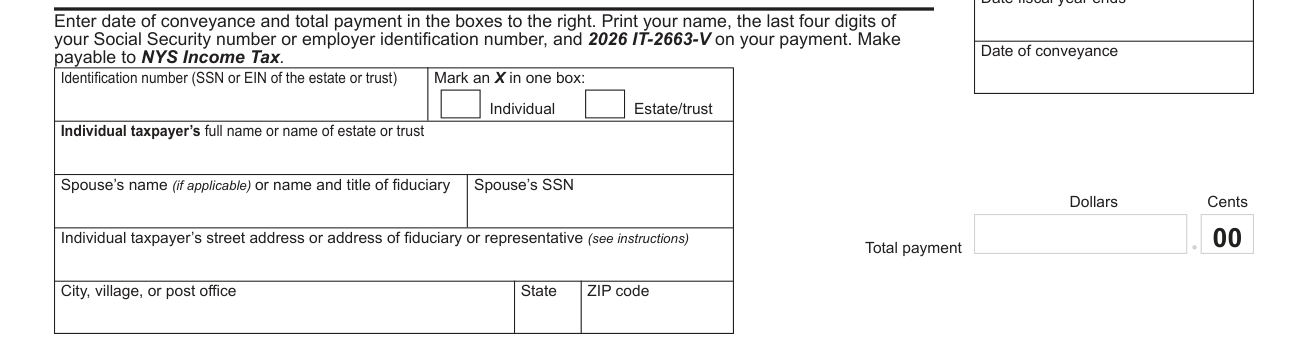
You must complete Form IT-2663-V, even if there is no payment of estimated personal income tax due.
You must attach a separate check or money order made payable in U.S. funds to NYS Income Tax for the full amount of estimated personal income tax due as shown on Part 2, line 3, and Form IT-2663-V (below).
Enter date of conveyance and total payment in the boxes to the right. Print your name, the last four digits of your Social Security number or employer identification number, and 2026 IT-2663-V on your payment.
Enter the identification number (SSN or EIN of the estate or trust) and mark an X in one box: Individual or Estate/trust.
Enter the individual taxpayer's full name or name of estate or trust, the spouse's name (if applicable) or name and title of fiduciary, the spouse's SSN, the individual taxpayer's street address or address of fiduciary or representative (see instructions), city, village, or post office, state and ZIP code.
If your situation is different
The gain is reported as an installment sale
If the gain is being reported as an installment sale, enter the amount of gain that you (and your spouse, if applicable) will be reporting on your 2026 federal income tax return.
Only a portion of the property is inside New York State or qualifies as your principal residence
If only a portion of the property is located inside New York State, enter the gain allocated to the portion of the property located inside New York State.
If only a portion of the property qualifies as your principal residence, enter the gain allocated to the portion of the property that did not qualify as your principal residence and will be reported on your federal income tax return for 2026.
Attach a statement to Form IT-2663 showing how you computed the allocation.
Two or more persons sell the property
If two or more persons transfer or sell the real property, allocate the total gain on the property among the transferors/sellers in the same manner as the gain is allocated for federal income tax purposes. Attach a statement to Form IT-2663 showing each transferor's/seller's name, SSN or EIN, address, and share of the gain.
A nonresident estate or trust
A nonresident estate or trust must enter the amount of the gain, without regard to any distributions, from line 17.
Common questions about Form IT-2663
What is form it 2663 used for?
Form IT-2663 is the Nonresident Real Property Estimated Income Tax Payment Form, for use on sale or transfer of real property by a nonresident of New York State. This form is valid for sales or transfers (date of conveyance) after December 31, 2025, but before January 1, 2027.
Where do I file it?
Submit your completed Form IT-2663 with full payment of estimated tax due, if any, to the recording officer of the county at the time the deed is presented to be recorded. Do not mail Form IT-2663 to the Tax Department.
When is this form not the right one?
Do not use Form IT-2663 for the sale, transfer, or other disposition of shares of stock by a nonresident in a cooperative housing corporation. Use Form IT-2664, Nonresident Cooperative Unit Estimated Income Tax Payment Form, instead.
Sources
[1] Form IT-2663 (2026), Nonresident Real Property Estimated Income Tax Payment Form, New York State Department of Taxation and Finance (the Official source link on this page).