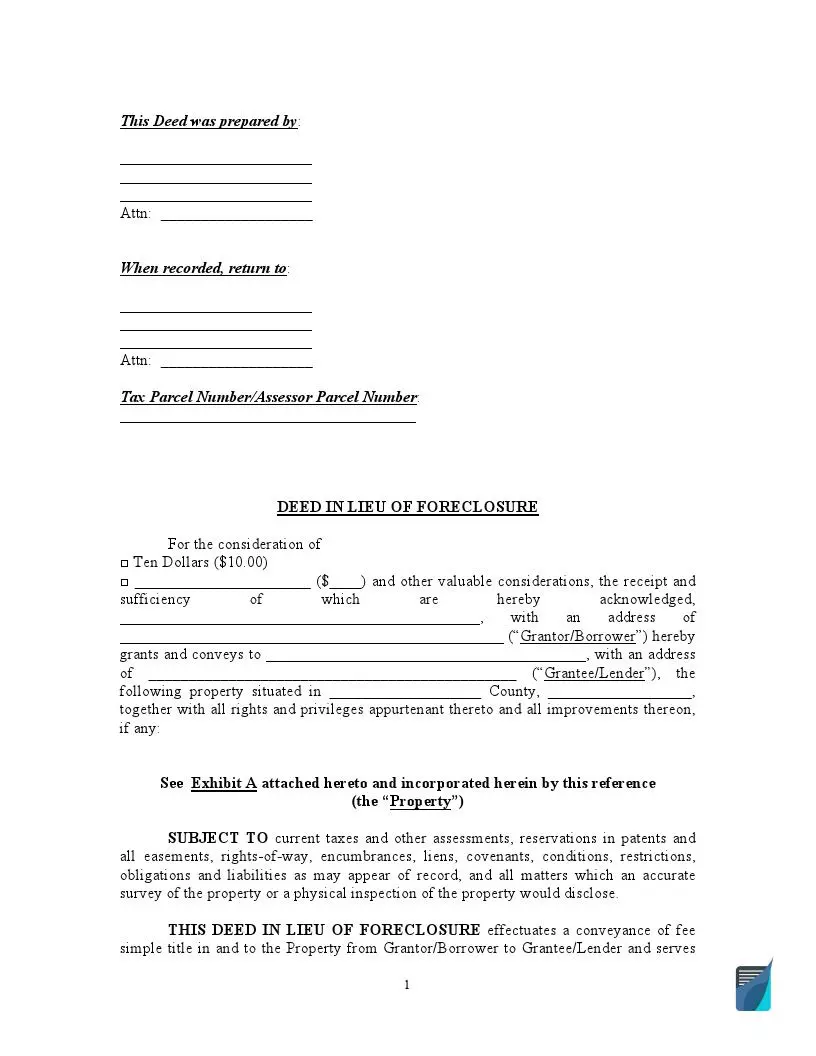
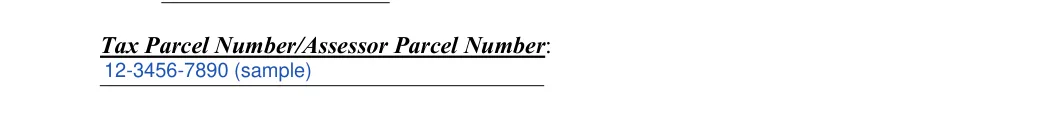A deed in lieu of foreclosure form is a document a borrower uses to give a property to the lender and settle a mortgage they can no longer pay. This legal instrument serves to release a borrower from financial obligations while transferring the property in question to the lender. It is one option to talk through with your lender.
Last Updated: October 2026. This guide is reviewed and updated regularly to reflect current law. If you notice an error or outdated information, please contact us.
Create a Personalized Deed in Lieu of Foreclosure Form online in under 5 minutes!
Build Your Document
Answer a few simple questions to make your document in minutes
Save and Print
Save progress and finish on any device, download and print anytime
Sign and Use
Your valid, lawyer-approved document is ready
... or download your Deed in Lieu of Foreclosure Form as a PDF file
In a deed in lieu of foreclosure, a lender and a borrower agree to skip the foreclosure process, which can be slow and costly for both sides. If the parties manage to come to a voluntary settlement, they write the agreement conveying all interest in the property from the mortgagor to the mortgagee.
Thus, the former frees themselves of unpaid balances and, in most cases, any other liabilities related to the mortgage loan. The latter saves time and money while getting an opportunity to recoup at least part of their losses related to the default loan.
In this document the borrower is also called the mortgagor or the Grantor, and the lender is also called the mortgagee or the Grantee. The FormsPal template uses the labels Grantor/Borrower and Grantee/Lender.
What Are the Benefits and Risks of a Deed in Lieu of Foreclosure?
Since there are other instruments to resolve the issue of delinquent mortgages, both lenders and borrowers should weigh up the pros and cons of opting for a deed in lieu of foreclosure. Being rather helpful in some circumstances, this type of agreement may turn out less favorable or even unacceptable in other scenarios. So, the parties should size up their specific situation while keeping in mind the following common benefits and risks.
Lender’s perspective
Advantages
It might seem that a mortgage provider can benefit nothing from this agreement since it leaves the mortgagee with some property to be sold before they will be able to cover their losses. However, it still might be a better option compared with foreclosure, as the latter is a quite time-consuming procedure, especially in states with judicial foreclosure.
Also, a foreclosure procedure entails repossession costs, which otherwise can be eliminated by the lender. Another scenario the mortgagee should consider before making a decision is the possibility of the borrower filing for bankruptcy. In this case, the mortgage provider will face further delays and expenses, which can be avoided through a voluntary settlement with the mortgagor.
Disadvantages
A deed in lieu of foreclosure is surely not the best option for a lender if the real estate in question is encumbered by another mortgage or other liens. Since the agreement transfers legal ownership of the property to the loan supplier, the latter will be liable for all the encumbrances. Besides, the lender might fail to sell the asset gained within a short time and/or for the right price if the property is in poor condition or if the house prices have dropped down.
Borrower’s perspective
Advantages
Borrowers are more likely to ask for a deed in lieu of foreclosure since it saves them from both the financial burden and public dishonor. While they are doomed to lose their homes due to the overdue loan anyway, foreclosure is a more extensive and painful process than arranging a settlement with the lender.
A deed in lieu of foreclosure can even cover a deficiency if the outstanding loan amount is higher than the fair market value of the property. The deficiency can be either forgiven in full or significantly reduced.
And obviously, foreclosure leaves a spot on a credit reputation, which hampers any attempts to get a loan in the future. Although a deed in lieu of foreclosure shows up on a credit report too, it takes only two years to remove it as against seven years of foreclosure.
Besides, if the mortgagee has incentives to get the rights over the property as fast as possible (for example, when the lender has a buyer in sight), the borrower can gain other financial benefits except for the release from the debt obligations. Namely, the mortgage provider can offer a “cash for keys” agreement to have the house vacated fast and left in a good condition.
Disadvantages
On the other side, a deed in lieu of foreclosure still spoils the borrower’s credit reputation, not to mention that it deprives the mortgagor of the home. If the latter wants to continue the struggle for the property, it is better to consider alternative ways.
Moreover, the borrower can in no way make the loan supplier enter into this agreement, so it all depends on the good will and dealmaking skills of the parties. Nobody can guarantee that the lender would write off the whole debt either. In this case, the debtor will be left without the home and still in debt. But if the creditor agrees to issue a waiver, the shortfall will be considered a taxable gain for the mortgagor, which is also a drawback.
How Do You Ask a Lender for a Deed in Lieu of Foreclosure?
Both a lender and a borrower can initiate negotiations about a deed in lieu of foreclosure, but the latter ones tend to come up with this proposal more often. Upon making the decision, the debtor needs to submit a corresponding application along with documents proving poor financial position.
The ower has to clearly express their voluntary offer and the reasons behind it. The loan supplier is obliged to respond with written consent or denial. If the mortgagee accepts the offer, the letter must contain clear conditions under which the party will agree to the ownership transfer.
However, the conditions are usually negotiable, so the borrower can proceed with their efforts to arrive at a settlement even if the initial terms are not acceptable.
Reasons why the deed can be rejected
It is clear that the lender will not be interested in an offer if it is associated with delays, money loss, or probable litigations. So, the most common reasons for a lender to reject an offer are:
all kinds of encumbrances placed on the property, which will be transferred along with the ownership;
significant price depreciation when the home’s current price is much lower than the amount owed;
the poor condition of the real estate, which makes the lender doubt that the money gained from the sale would cover the outstanding loan;
the asset is subject to government-backed loans that imply a payout for the mortgagee in case of foreclosure;
the mortgage is part of a PSA, which might require the mortgagor to make a financial contribution prior to receiving consent to a deed in lieu of foreclosure.
Create a Personalized Deed in Lieu of Foreclosure Form online in under 5 minutes!
What to Include in the Deed
A deed in lieu of foreclosure form can provide a faster way for formalizing the agreement since it requires simple filling out blank spaces with necessary information. The details that must be specified in the settlement for it to be legally valid include:
both parties’ full names and addresses
legal description and address of the property
total consideration equivalent to the fair market value
execution date
both parties’ signatures notarized
However, the agreement might contain additional information, for example, associated with a deficiency balance or other conditions the parties agreed upon.
How to Fill Out the Deed in Lieu of Foreclosure
The steps below follow the FormsPal deed in lieu of foreclosure template. Open it with the Create My Document button at the top of this page, or download the PDF and fill it in with the FormsPal PDF editor. Work from the top of page 1 to the notary block on page 3, then finish with Exhibit A on page 4.
The screenshots under each step show the FormsPal Deed in Lieu of Foreclosure template filled with sample entries in blue, so you can see where each answer goes. The names, addresses, dates and amounts are examples only.
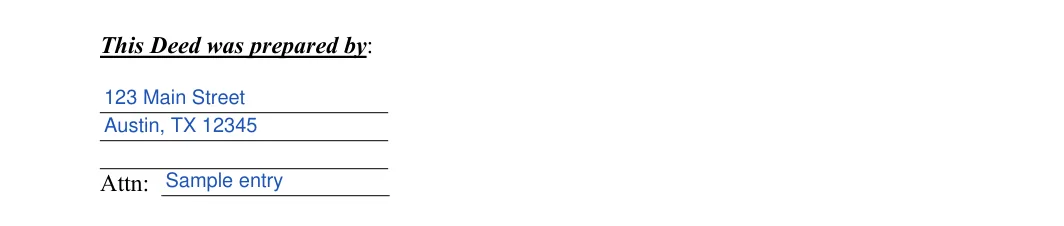
This Deed was prepared by: Fill in the lines at the top of page 1 with the mailing address of the person who prepared the deed, and add the Attn contact.Step 1: sample entries, not a real document.
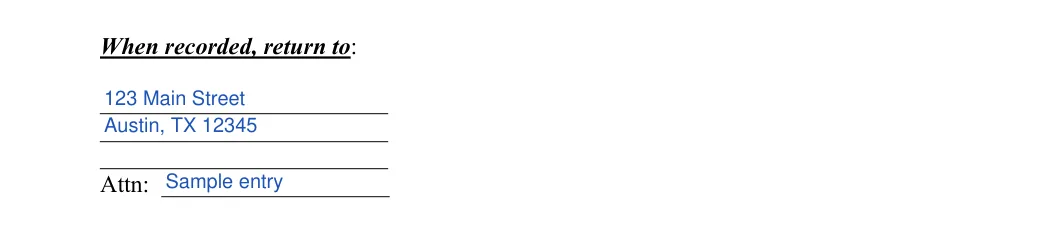
When recorded, return to: Enter the mailing address that follows these words, along with the Attn contact.Step 2: sample entries, not a real document.
Tax Parcel Number/Assessor Parcel Number: Type the property's tax parcel or assessor parcel number on this line. It often appears on a property tax bill.Step 3: sample entries, not a real document.
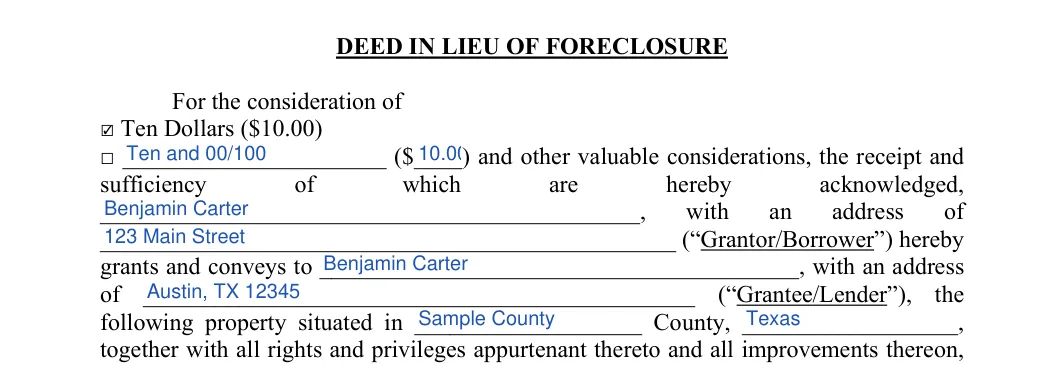
Consideration, parties and property: Under the DEED IN LIEU OF FORECLOSURE heading, check the box for Ten Dollars ($10.00), or check the second box and write in the amount. Then enter the Grantor/Borrower with an address, the Grantee/Lender with an address, and the county and state where the property sits.Step 4: sample entries, not a real document.
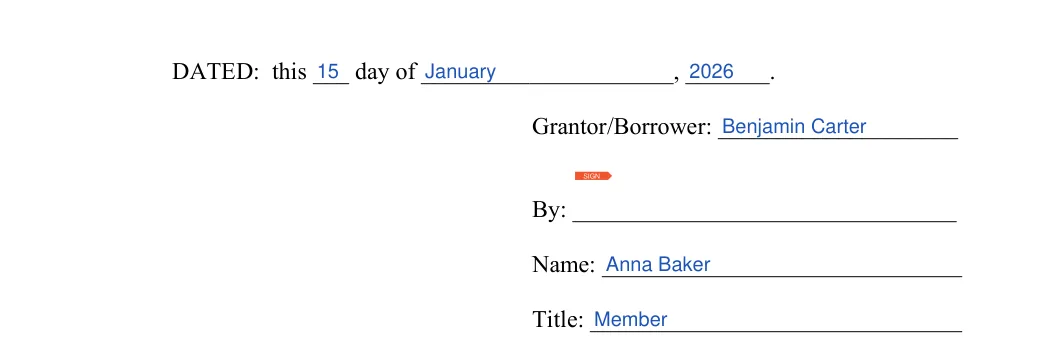
Date and signature: On page 3, fill in the day, month and year after DATED. Then add the Grantor/Borrower name, the Name and Title of the person signing, and sign on the By line.Step 5: sample entries, not a real document.
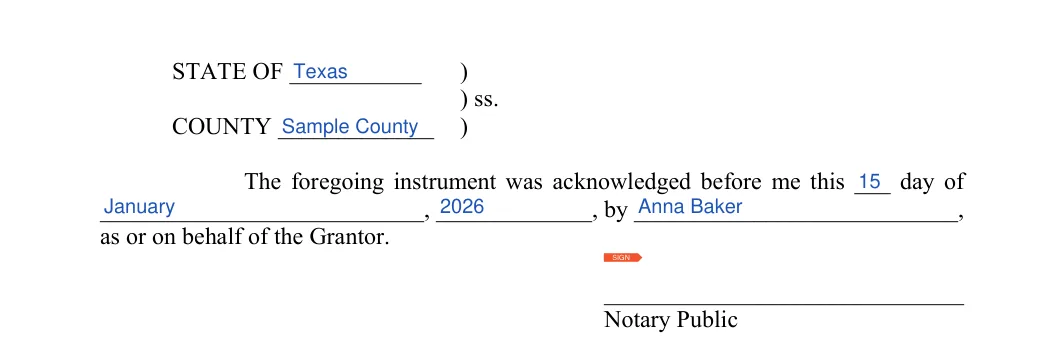
State, county and notary block: Enter the state and county at the top of the notary block. Then add the day, month and year and the name of the person signing after the word "by". The notary completes the Notary Public line.Step 6: sample entries, not a real document.
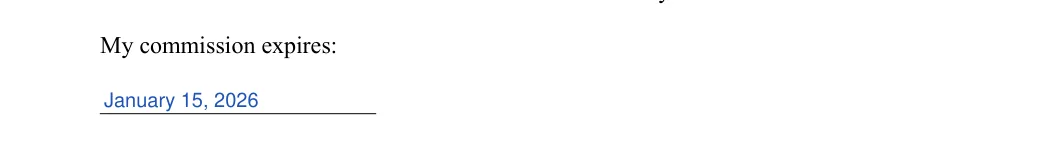
My commission expires: Leave this line for the notary, who adds the date the commission ends.Step 7: sample entries, not a real document.
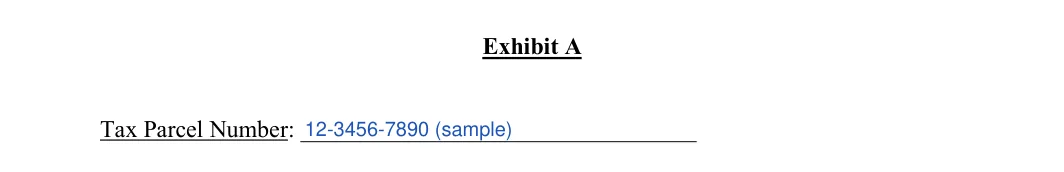
Exhibit A: On page 4, enter the Tax Parcel Number again at the top of Exhibit A. Page 1 refers to this page for the property, so you can type the property description below the number.Step 8: sample entries, not a real document.
Frequently Asked Questions
What is a deed in lieu of foreclosure?
It is the document a borrower and a lender use to transfer a property to the lender instead of going through foreclosure. The FormsPal template has spaces for the borrower, the lender, the property and a notary block.
What do I need before I start the form?
Gather the names and mailing addresses of the borrower and the lender, the address and county of the property, and its tax parcel number. Also decide the amount for the consideration line and the date you plan to sign.
Can I fill out the form online?
Yes. Select Create My Document at the top of the page, answer the questions, and save or print the finished deed. You can also download the blank PDF.
Where do I find the tax parcel number?
Look for it on a property tax bill or on the county assessor's website. Copy it exactly as it appears.
Should I keep a copy of the signed deed?
Yes. Keep a copy of the signed deed with your other home records.
General information, not legal or tax advice.
Mara Erlach
Writer & Attorney
Mara has been practicing estate planning and trust law in California since 2003, taking pride in helping clients of all backgrounds and asset profiles form a complete and customized estate plan. Her specialties are: estate planning, wills and trusts, trust and probate administration.