
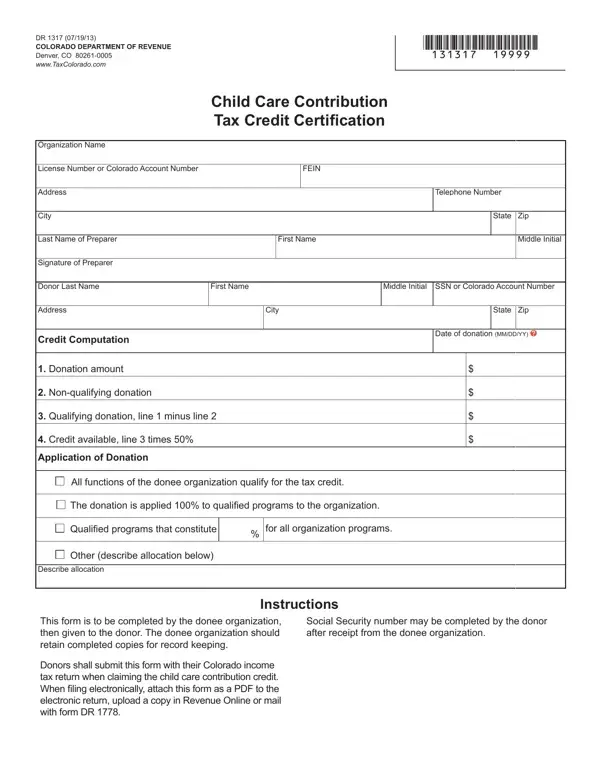

Colorado Form DR 1317 at a glance
What it is: This is the Child Care Contribution Tax Credit Certificate.
Where and when to file: This form must be completed by the recipient of the contribution and filed with the donor's Colorado income tax return.
This form must be completed by the contribution recipient, or a duly authorized employee or agent of the recipient, and furnished to the donor upon receipt of a qualifying contribution.
A filled-in Colorado Form DR 1317 example: a child care center fills in Sections A and B
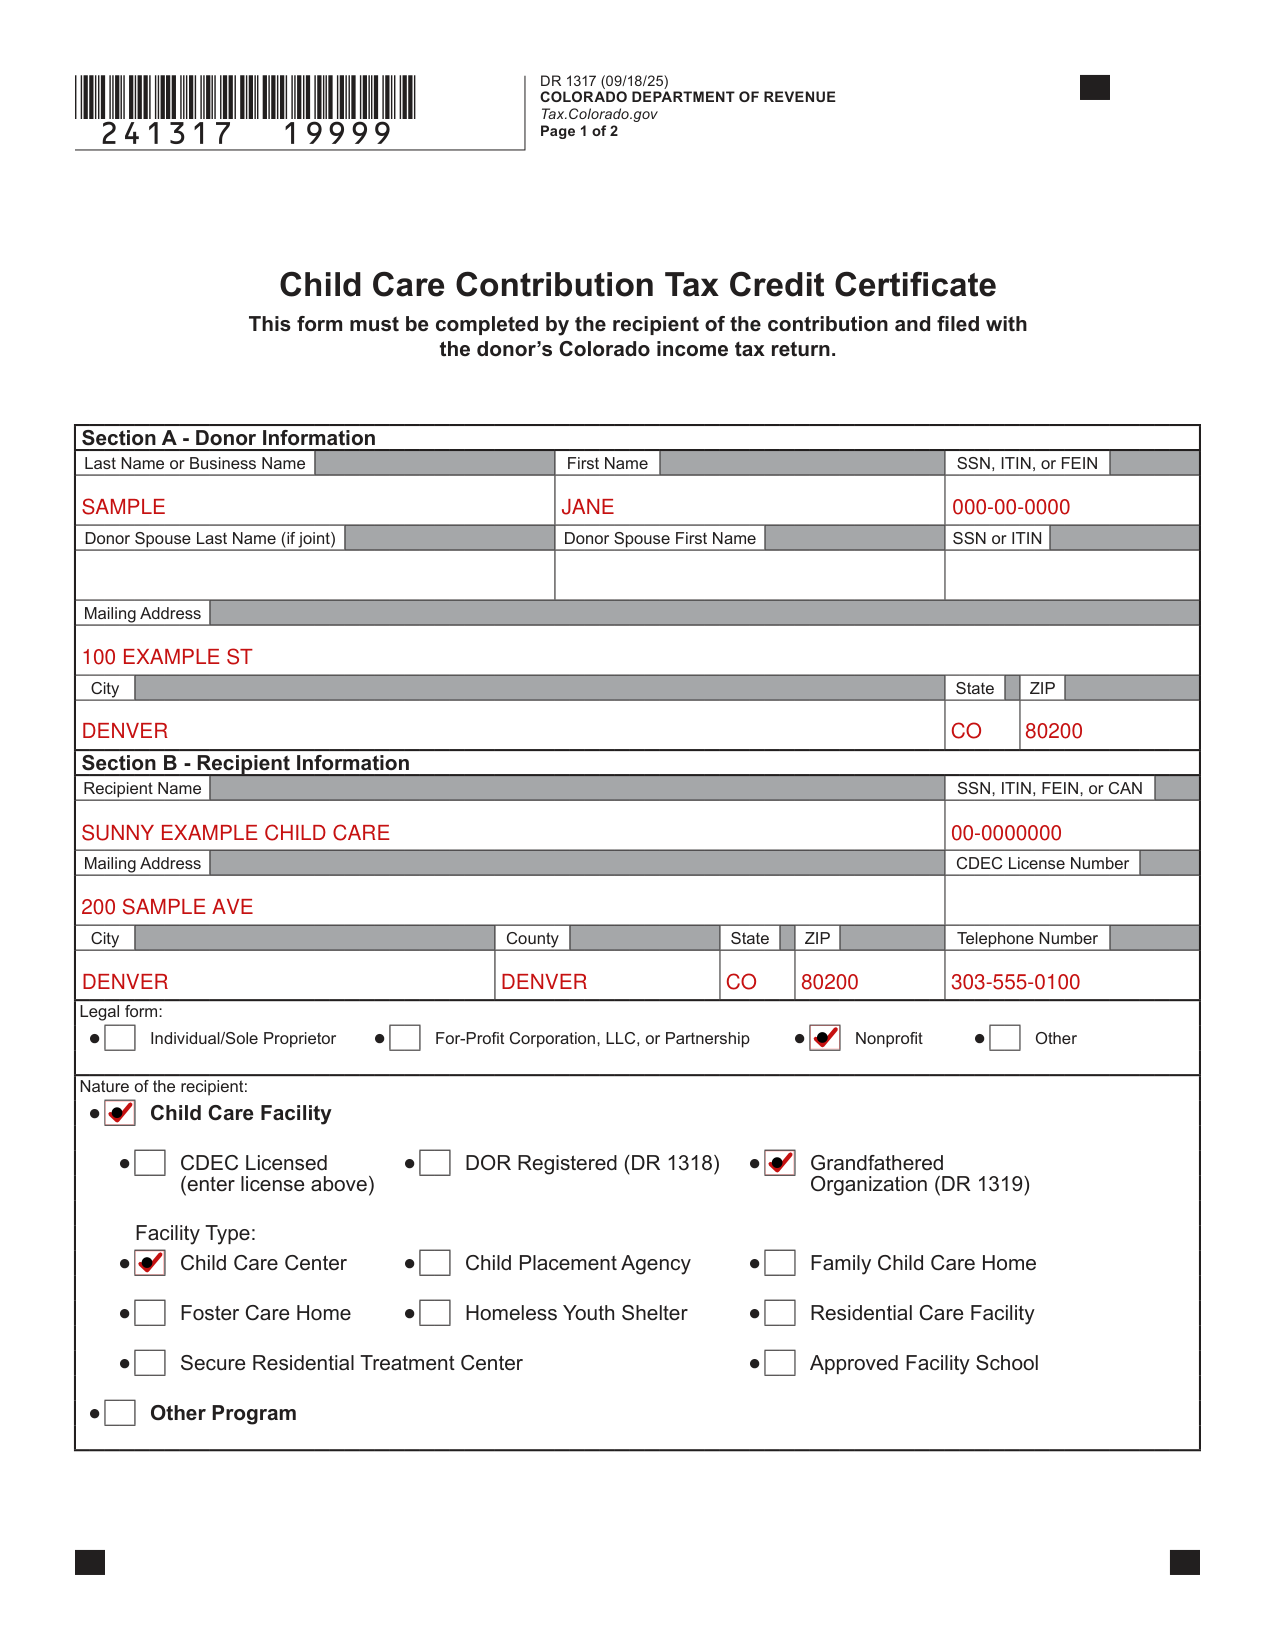
How to fill out Colorado Form DR 1317, box by box
Section A - Donor Information
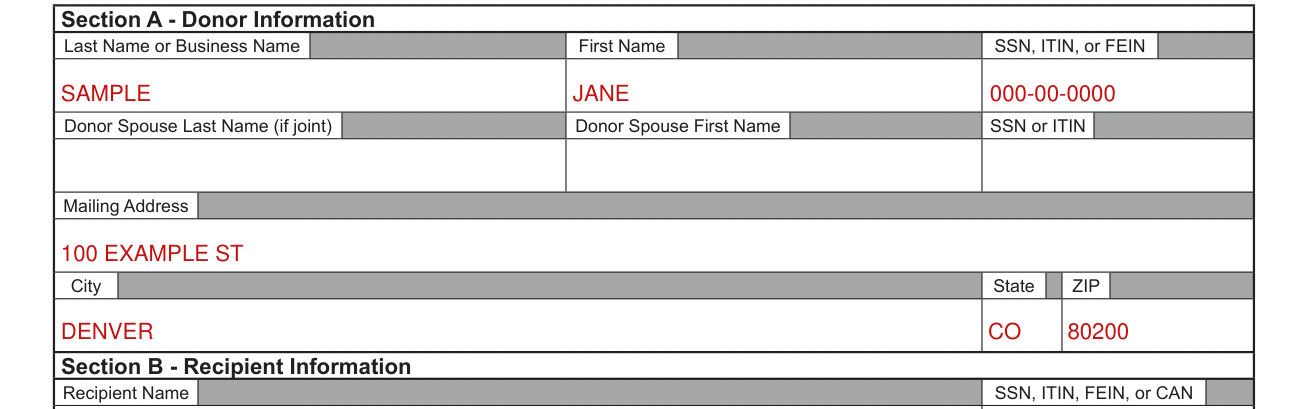
Section A - Donor Information: enter the name, mailing address, and telephone number of the donor.
If the donor is a corporation, partnership, LLC, or other legal entity, enter the donor's legal name in the field for the donor's last name or business name.
In the case of a donation by two individuals filing a joint return, enter the last and first name of both individuals.
The recipient organization may furnish this form (and retain a copy) without the social security number (SSN), individual taxpayer identification number (ITIN) or federal employer identification number (FEIN) of the donor.
The donor must complete those fields prior to filing their Colorado income tax return.
Legal entities must use the identification number that will be used to file their Colorado income tax return.
Section B - Recipient Information
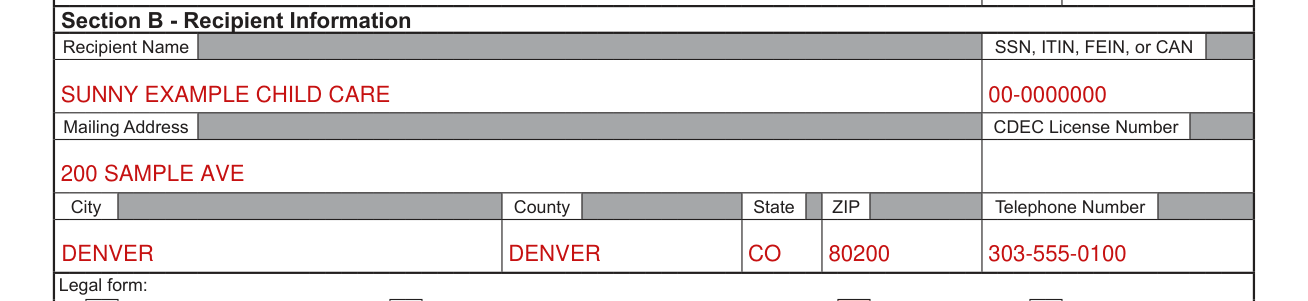
Section B - Recipient Information: enter the name of the recipient.
If the recipient is an individual or sole proprietor, enter the individual's first and last name.
Otherwise, enter the legal name of the recipient.
Enter the recipient's SSN, ITIN, FEIN, or Colorado account number (CAN).
If the recipient is an LLC that is disregarded as separate from its owner, enter the name and tax identification number of the owner.
Enter the mailing address for the office where the Department should direct any inquiries regarding this form.
Enter the county in which the recipient is located.
If the recipient is located in multiple counties, enter the county where this contribution will be principally used.
If the recipient operates a child care facility licensed, or required to be licensed, by the Colorado Department of Early Childhood, enter the facility's license number.
Legal form

Mark the appropriate box to indicate the legal form of the recipient.
Nature of the recipient
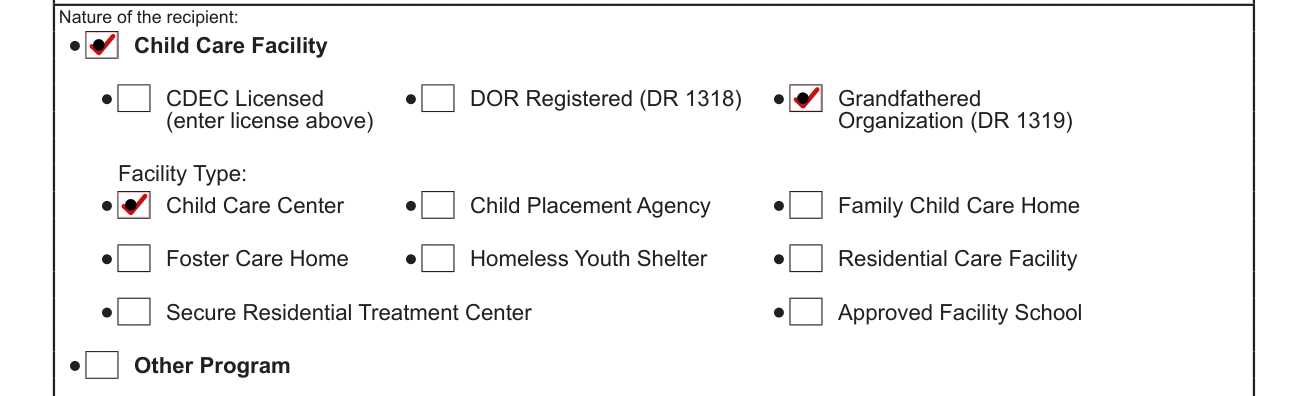
Mark the appropriate box to describe the nature of the recipient.
Note that the approved facility school must be affiliated with a licensed or certified hospital in the state that is also a nonprofit organization.
Mark the "other program" box if the recipient is not a child care facility and will use the contribution for grant, loan, training, or information distribution programs.
Section C - Contribution Information
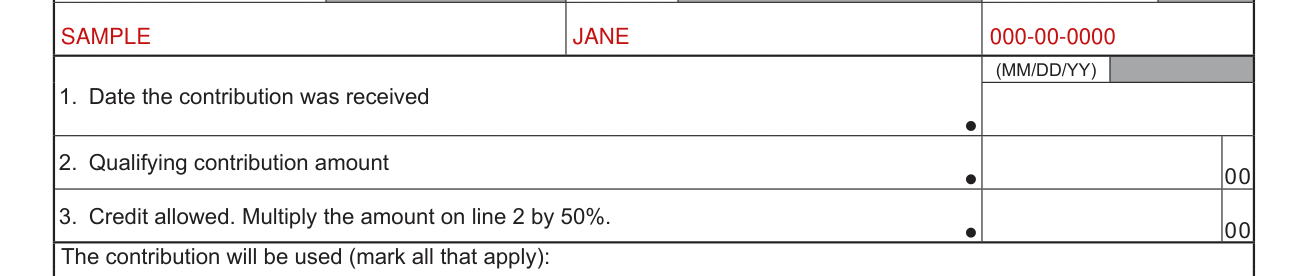
Line 1 Receipt date: Enter the date the money was received from the donor.
Line 2 Qualifying contribution amount: Enter the amount of the contribution, but do not enter amounts received that do not qualify for the child care contribution credit.
Refer to paragraph (10) of Department Rule 39-22-121 for information regarding contributions split between qualified and nonqualified purposes.
Line 3 Credit allowed: Multiply the amount on line 2 by 50% (0.50) and enter the result on this line 3.
If the amount on line 2 is greater than $200,000, then enter $100,000 on this line 3 (checked November 8, 2026).
Contribution use
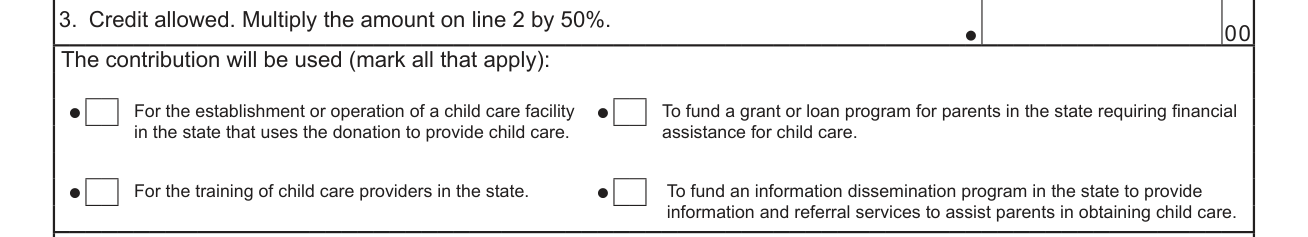
Contribution use: Mark all of the boxes that describe the qualifying use of the contribution.
For the establishment or operation of a child care facility in the state that uses the donation to provide child care.
To fund a grant or loan program for parents in the state requiring financial assistance for child care.
For the training of child care providers in the state.
To fund an information dissemination program in the state to provide information and referral services to assist parents in obtaining child care.
Section D - Certification
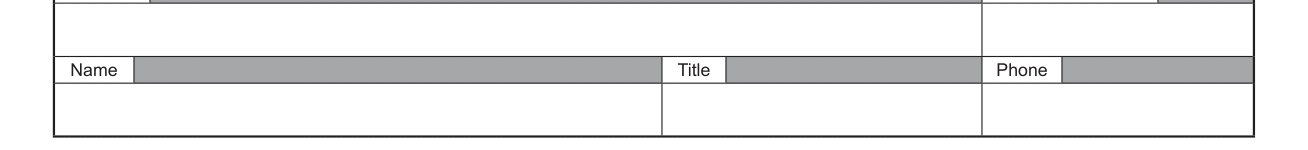
Section D - Certification: the person completing this form on behalf of the contribution recipient must review it for completeness and accuracy, read the certification statement in this section D, and sign and date the form.
Enter the name, title, and phone number of the person who completed this form on behalf of the contribution recipient.
First, the recipient is eligible to receive contributions qualifying for the income tax credit allowed by section 39-22-121, C.R.S.
Second, the above-named donor made a qualifying contribution on the date listed on line 1, and in the amount listed on line 2.
Third, the contribution will be used only for the purpose(s) indicated by the box(es) checked in Section C, which purposes are directly related to promoting child care in Colorado.
And fourth, if the recipient is a child care facility, neither the donor nor a person related to the donor has a financial interest in the child care facility to the best of my knowledge and belief.
Make a copy of this form for your records, and promptly furnish the original to the donor.
More rules for Colorado Form DR 1317
Taxpayers that make a qualifying monetary contribution to promote child care in Colorado may claim an income tax credit equal to 50% of the total qualifying contribution.
The maximum credit allowed for a tax year is $100,000 (checked November 8, 2026).
Section 39-22-121 (1.7), C.R.S., defines "child care" as care provided to a child 12 years of age or younger.
If your situation is different
You are the donor
As the donor, you are responsible for verifying that the organization is authorized to receive contributions eligible for the child care contribution tax credit.
A list of child care facilities licensed by the Department of Early Childhood can be accessed at ColoradoShines.com/search.
The list of unlicensed, license exempt, and other programs registered with the Department can be downloaded from Tax.Colorado.gov/DR1317.
To claim credit for a qualifying contribution, you must obtain a completed DR 1317 form from the recipient and file it with your Colorado income tax return.
Note that the amount of credit allowed for contributions made during the tax year may not exceed $100,000 per taxpayer (checked November 8, 2026).
For purposes of this rule, two individuals filing a joint return are considered one taxpayer.
The child care contribution tax credit is nonrefundable, meaning that the total amount a taxpayer may use in a tax year, together with other nonrefundable credits, cannot exceed the taxpayer's Colorado income tax liability.
Taxpayers may carry forward any excess for up to five tax years and must use the excess credits in the earliest tax year possible.
When filing electronically, attach this form as a PDF to the electronic return, upload a copy using the e-filer attachment feature at Colorado.gov/RevenueOnline, or mail a copy with form DR 1778.
Common questions about Colorado Form DR 1317
Where do I file it?
This form must be completed by the recipient of the contribution and filed with the donor's Colorado income tax return.
Is there a penalty?
"I declare, under penalties of perjury, that the statements made herein are true and correct to the best of my knowledge and belief."
When is this form not the right one?
Taxpayers may not claim the credit for contributions that are not directly related to promoting child care in the state or for contributions that a taxpayer makes to a child care facility in which the taxpayer or a person related to the taxpayer has a financial interest.
Sources
[1] Colorado Form DR 1317 (09/18/25), Child Care Contribution Tax Credit Certificate, Colorado Department of Revenue (the Official source link on this page).