
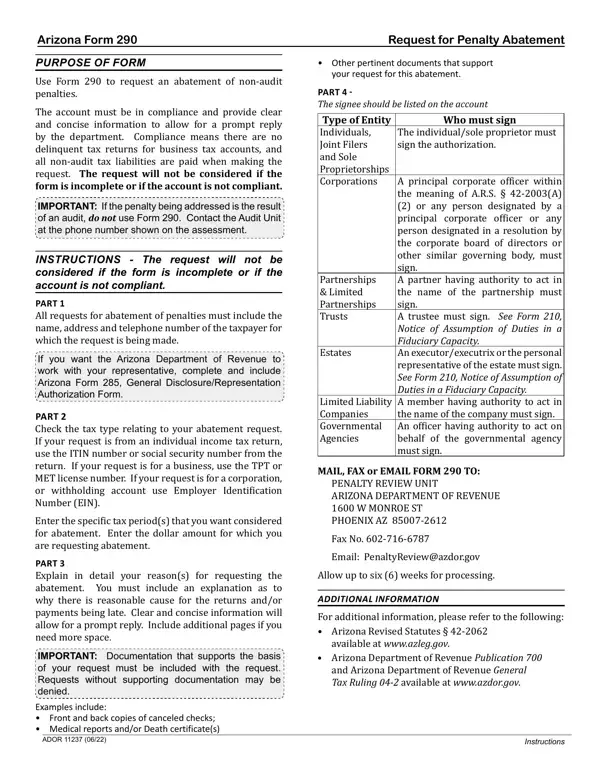
Form 290 at a glance
What it is: Arizona Form 290 is the Request for Penalty Abatement.
Where and when to file: Allow up to six (6) weeks for processing.
Use Form 290 to request an abatement of non-audit penalties.
Individuals, Joint Filers and Sole Proprietorships: the individual/joint filers/sole proprietor must sign.
A filled-in Form 290 example: an individual asks for a penalty to be abated after an illness
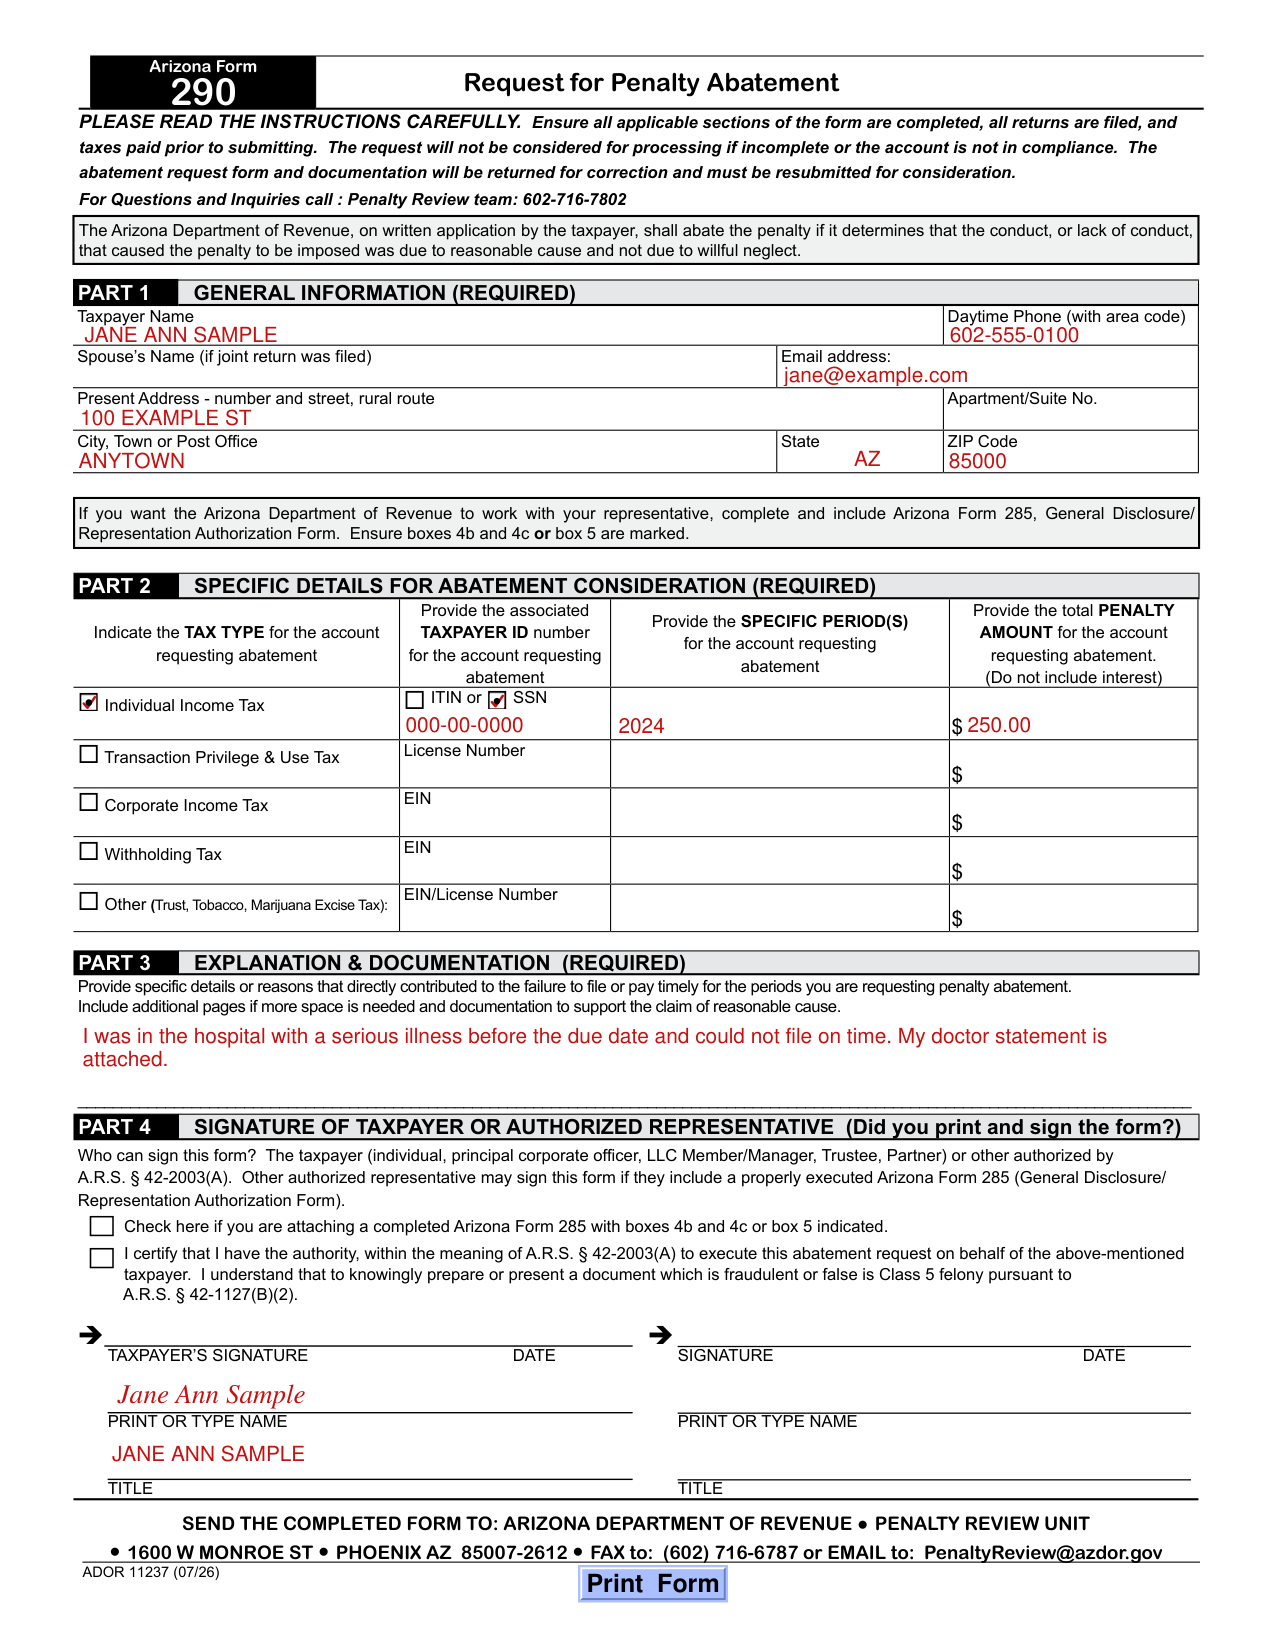
How to fill out Form 290, box by box
Part 1, General information
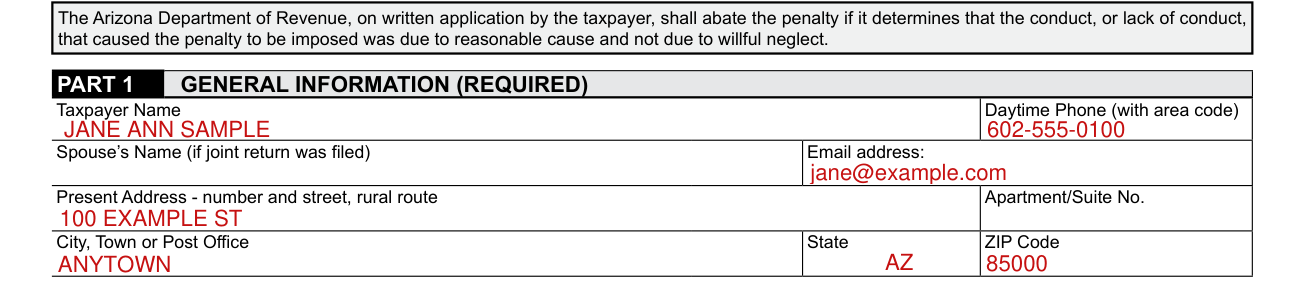
In Part 1, all requests for abatement of penalties must include the name, address, email address and telephone number of the taxpayer for which the request is being made.
Enter the Spouse's Name if a joint return was filed.
Part 2, Specific details for abatement consideration
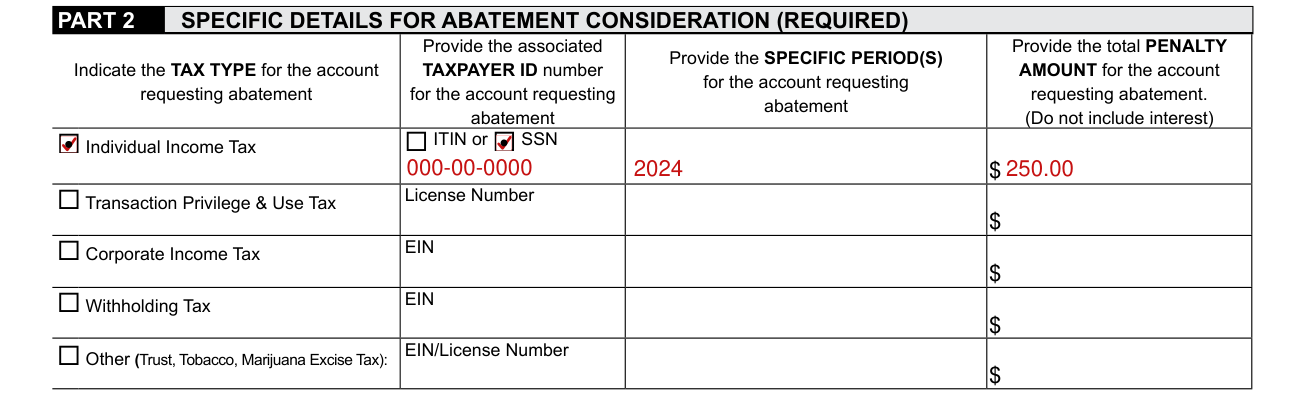
Indicate the tax type for the account requesting abatement.
Provide the associated taxpayer ID number for the account requesting abatement.
If your request is for an individual income tax return, use the Individual Taxpayer Identification Number (ITIN) number or social security number from the return.
If your request is for a business account, use the Transaction Privilege Tax (TPT) or Marijuana Excise Tax (MET) license number.
If your request is for a corporate or withholding account, use an Employer Identification Number (EIN).
Provide the specific period(s) for the account requesting abatement.
Enter the specific tax period(s) in date format, based on the filing frequency, that you want considered for the abatement. Annual filers: 2015-2016. Quarterly filers: 01/2017-03/2017 or Q2 2018. Monthly filers: 07/2017-02/2019.
Provide the total penalty amount for the account requesting abatement. (Do not include interest)
Enter the dollar amount for which you are requesting penalty abatement. There is no statutory provision that permits abatement of interest based on reasonable cause. In Part 3, explain in detail your reason(s) for requesting the abatement. Include in the explanation as to why there is reasonable cause for the returns and/or payments being late. Include additional pages if you need more space.
Part 3, Explanation and documentation
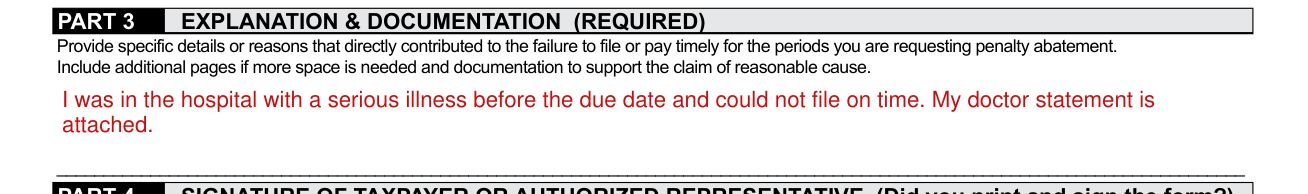
In Part 3, provide specific details or reasons that directly contributed to the failure to file or pay timely for the periods you are requesting penalty abatement.
You must include documentation that supports the basis of your request. Requests without supporting documentation may be denied.
Examples include: proof of timely payment, including front and back of canceled checks; medical reports and/or Death Certificate(s); other pertinent documents that support your request for this abatement; proof an extension has been filed.
Part 4, Signature of taxpayer or authorized representative
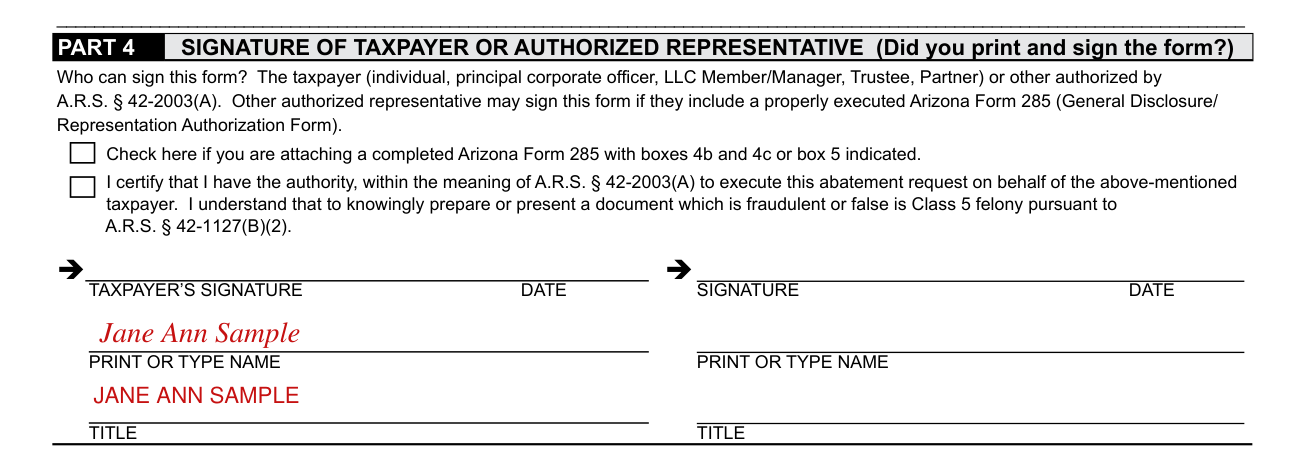
The taxpayer (individual, principal corporate officer, LLC Member/Manager, Trustee, Partner) or other authorized by A.R.S. § 42-2003(A) can sign this form.
Other authorized representative may sign this form if they include a properly executed Arizona Form 285 (General Disclosure/ Representation Authorization Form). Check here if you are attaching a completed Arizona Form 285 with boxes 4b and 4c or box 5 indicated.
A responsible party that has the authority to act on behalf of the taxpayer should check the box in Part 4 and certify that they have the authority, within the meaning of A.R.S. § 42-2003(A), to execute this abatement request on behalf of the taxpayer.
I understand that to knowingly prepare or present a document which is fraudulent or false is Class 5 felony pursuant to A.R.S. § 42-1127(B)(2).
More rules for Form 290
On written application by the taxpayer, the Arizona Department of Revenue shall abate the penalty if it determines that the conduct, or lack of conduct, that caused the penalty to be imposed was due to reasonable cause and not due to willful neglect.
Handwritten signature, date, print the signer's name and title. An electronic signature with a digital certificate is accepted.
Situations where reasonable cause may not exist: ignorance of the law or lack of awareness of filing and paying requirements; delegation of duties; financial difficulties have no effect on the taxpayer's ability to file returns in a timely fashion.
For questions and inquiries call: Penalty Review team: 602-716-7802
Penalties and/or fees not considered for abatement are interest, TPT licensing fees, audit assessed penalties and any disallowed accounting credit(s) for TPT.
Reasons and other situations
The penalty is the result of an audit
If the penalty being addressed is the result of an audit, do not use Form 290. Contact the Audit Unit at the phone number shown on the assessment.
The delay was caused by a death
In the case of individual returns, delay caused by the death of a taxpayer or member of the taxpayer's immediate family. A copy of the death certificate must be provided.
You are unable to obtain records
Absence of records: the taxpayer is unable to obtain records necessary to determine the amount of tax due for reasons beyond the taxpayer's control. An example would be a fire which destroys the taxpayer's records.
You want the department to work with your representative
If you want the Arizona Department of Revenue to work with your representative, complete and include Arizona Form 285, General Disclosure/ Representation Authorization Form. Ensure boxes 4b and 4c or box 5 are marked.
Before you go
The account for which the abatement request is being submitted must be in compliance. Compliance means there are no delinquent tax returns and all non-audit tax liabilities are paid when making the request.
The request will not be considered for processing if incomplete or the account is not in compliance. The abatement request form and documentation will be returned for correction and must be resubmitted for consideration.
Common questions about Form 290
Where do I file it?
Send the completed form to: Arizona Department of Revenue, Penalty Review Unit, 1600 W Monroe St, Phoenix AZ 85007-2612, FAX to: (602) 716-6787 or EMAIL to: PenaltyReview@azdor.gov.
Sources
[1] Form 290 (07/26), Request for Penalty Abatement, Arizona Department of Revenue (the Official source link on this page).