
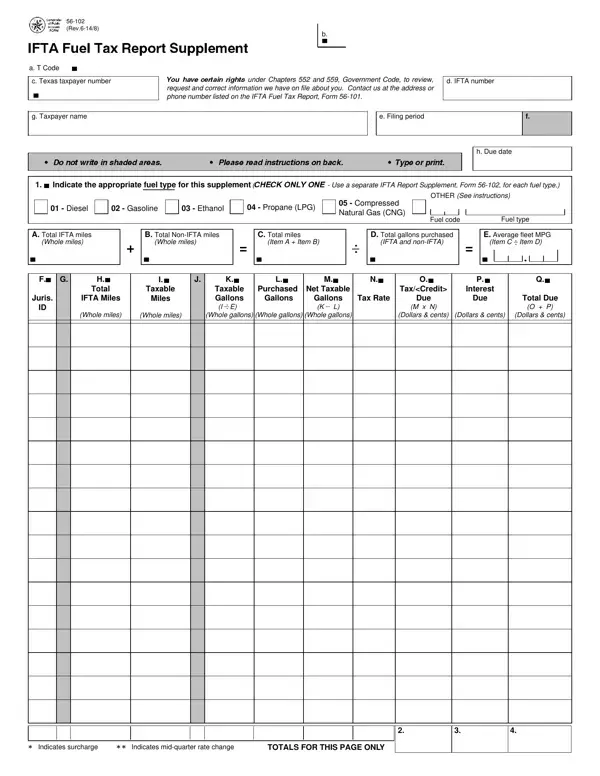

Form 56-102 at a glance
What it is: Form 56-102 is the IFTA Fuel Tax Report Supplement. Use a separate Form 56-102 for each fuel type.
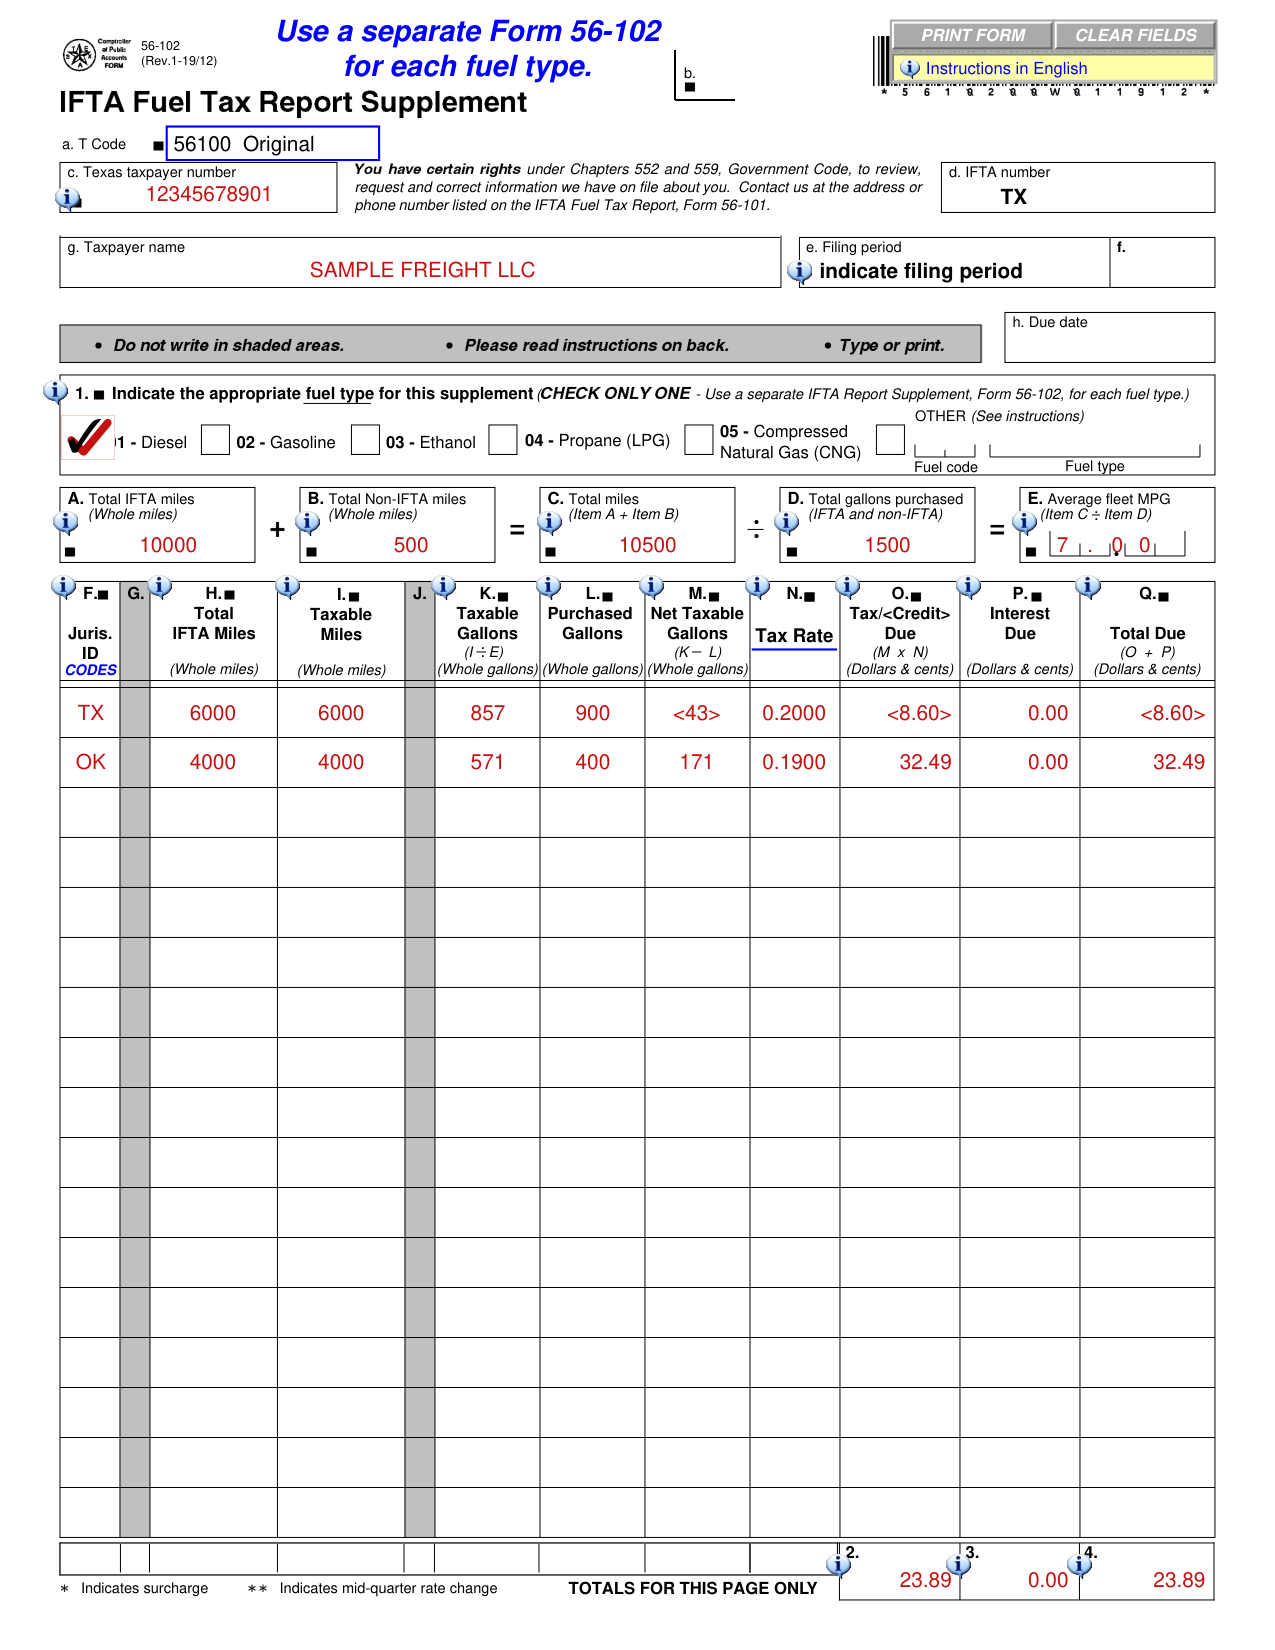
A filled-in Form 56-102 example: a fleet reports diesel in two jurisdictions
How to fill out Form 56-102, box by box
Item 1, the fuel type

Form 56-102 (Rev.1-19/12), Item 1: indicate the appropriate fuel type if it is not preprinted.
Place an "X" in the applicable box for Diesel, Gasoline, Ethanol, Propane or Compressed Natural Gas.
Only for OTHER fuel types, place an "X" in the last box and enter the fuel code and fuel type.
Items A to E, miles and gallons

In Item A, enter the total miles traveled in IFTA jurisdictions by all qualified motor vehicles in your fleet using the fuel type indicated.
Report all miles traveled whether the miles are taxable or nontaxable. For IFTA jurisdictions with a surcharge, include miles traveled only once for that jurisdiction.
The total in Column H for all pages must equal item A. Round mileage to the nearest whole mile.
In Item B, include total miles traveled in non-IFTA jurisdictions of Northwest Territories and Yukon Territory of Canada, Mexico, Alaska and the District of Columbia by all qualified motor vehicles in the fleet.
Report all mileage traveled whether the mileage is taxable or non-taxable. Round mileage to the nearest whole mile.
In Item C, add the amount in Item A and the amount in Item B to determine the total miles traveled by all qualified motor vehicles in your fleet.
In Item D, enter the total gallons of fuel purchased in both IFTA and non-IFTA jurisdictions by all qualified motor vehicles in your fleet using the fuel type indicated.
Round gallons to the nearest whole gallon. Fuel is considered "purchased" when it is pumped into your qualified vehicle.
In Item E, divide Item C by Item D. Round to 2 decimal places.
Columns F, H and I, jurisdiction and miles
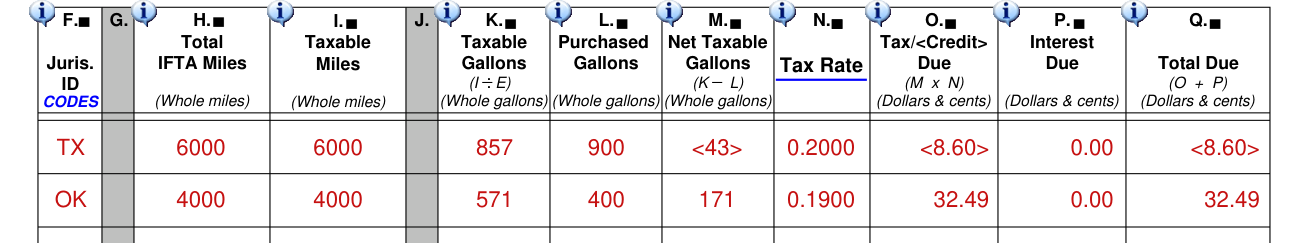
In Column F, preprinted are all IFTA member jurisdictions in which you have indicated operations during the previous four quarters.
If you did not operate in a jurisdiction listed, make no entries for that jurisdiction. If you operated in any jurisdiction other than those listed, enter the jurisdiction's two letter abbreviation from the table.
In Column H, enter the total miles (taxable and nontaxable) traveled in each IFTA jurisdiction for this fuel type only.
For lines where surcharges are reported, this column should be left blank.
In Column I, enter the IFTA taxable miles for each jurisdiction. Trip permit miles are not considered taxable in any jurisdiction.
Columns K, L and M, gallons
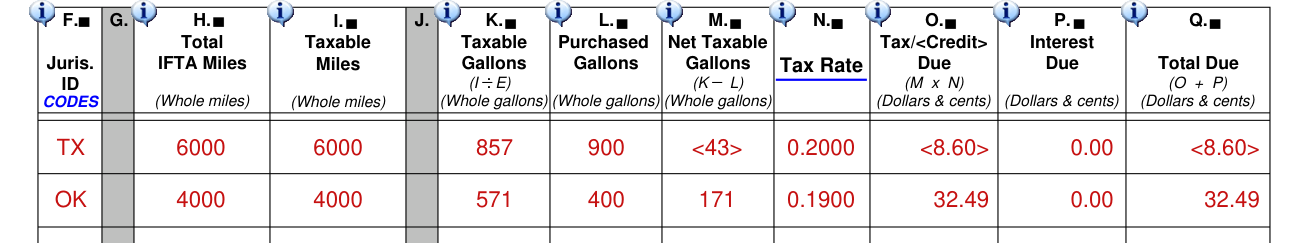
In Column K, divide the amount in Column I by the amount in Item E to determine the total taxable gallons of fuel consumed in each jurisdiction.
In Column L, enter the total gallons of fuel purchased tax paid in each IFTA jurisdiction.
Keep your receipts for each purchase claimed.
Column L cannot be greater than Item D.
In Column M, subtract Column L from Column K for each jurisdiction. If Column K is greater than Column L, enter the taxable gallons. If Column L is greater than Column K, enter the credit gallons. Use brackets < > to indicate credit gallons.
Columns N, O, P and Q, rate and amounts due
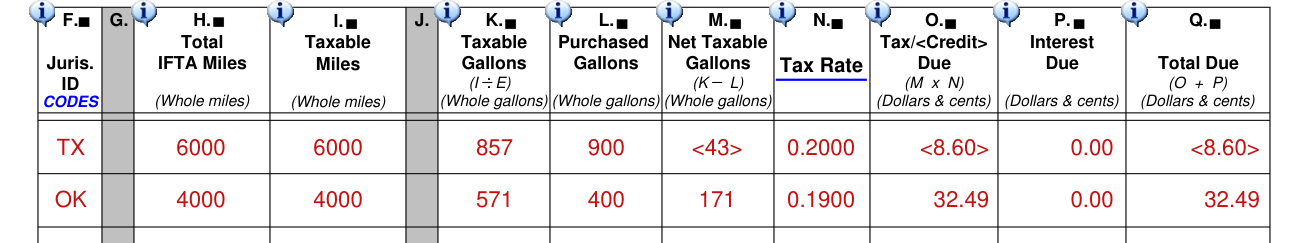
In Column N, the tax rate is listed for each preprinted IFTA jurisdiction on your report. If the tax rate is not preprinted, enter the tax rate for the appropriate fuel type from the enclosed tax rate chart.
In Column O, multiply the amount in Column M by the tax rate for that jurisdiction in Column N to determine the tax or credit. Enter credit amount in brackets < >.
In Column P, if you file late, compute interest on the tax due for each jurisdiction for each fuel type. Interest is computed on tax due from the due date of the report until the date the payment is postmarked.
In Column Q, for each jurisdiction add the amounts in Column O and Column P, and enter the total dollar amount due or credit amount. Enter credit amount in brackets < >.
Items 2, 3 and 4, totals for this page only

In Item 2, enter the total of amounts in Column O, in Item 3 the total of amounts in Column P, and in Item 4 the total of amounts in Column Q, for all jurisdictions listed on this page for the fuel type indicated.
More rules for Form 56-102
Some jurisdictions impose an additional charge on each taxable gallon of fuel used in that jurisdiction. This surcharge is not paid at the pump or upon withdrawal from bulk storage facilities; the surcharge is collected on the quarterly IFTA report.
If you have traveled in any of the jurisdictions that impose a surcharge, you must calculate and pay the surcharge on this report. To calculate the amount due for the surcharge, multiply the number of taxable gallons (K) used in that jurisdiction by the surcharge rate.
Fuel tax surcharges need to be reported on separate lines of the report supplements.
Sometimes jurisdictions change their tax rate during a quarter. When this occurs, it is necessary to separate the miles traveled during each rate period and report them on separate lines of the report supplement.
If you traveled in a jurisdiction that had a mid-quarter rate change, that jurisdiction should be listed multiple times on the supplement. If you did not incur travel during one of the rate periods, show zeros for that period.
When using bulk storage, report only gallons removed for use in your qualified motor vehicles. Fuel remaining in storage cannot be claimed until it is used.
Common questions about Form 56-102
Is there a deadline?
Reports must be postmarked no later than the last day of the month following the end of the quarter to be timely. If the last day of the month falls on a Saturday, Sunday or national holiday, the due date will be the next business day.
Sources
[1] Form 56-102 (Rev.1-19/12), IFTA Fuel Tax Report Supplement, Texas Comptroller of Public Accounts (the Official source link on this page).