

Form DRS-PW at a glance
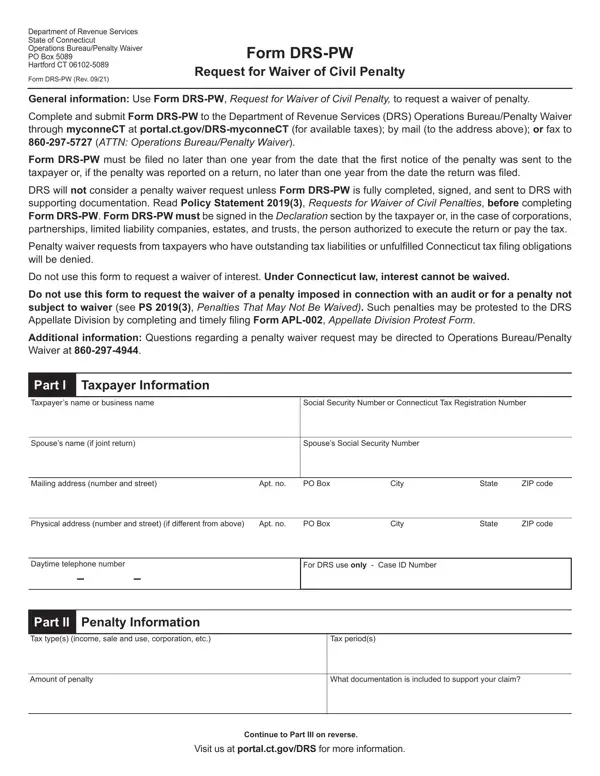
What it is: Form DRS-PW is the Request for Waiver of Civil Penalty.
Who signs: DRS will not consider a penalty waiver request unless Form DRS-PW is fully completed, signed, and sent to DRS with supporting documentation. Read Policy Statement 2019(3), Requests for Waiver of Civil Penalties, before completing Form DRS-PW. Form DRS-PW must be signed in the Declaration section by the taxpayer or, in the case of corporations, partnerships, limited liability companies, estates, and trusts, the person authorized to execute the return or pay the tax.
What to bring and attach to Form DRS-PW
Attach any documentation that you believe supports your penalty waiver request.
A filled-in Form DRS-PW example: a waiver request after a serious illness
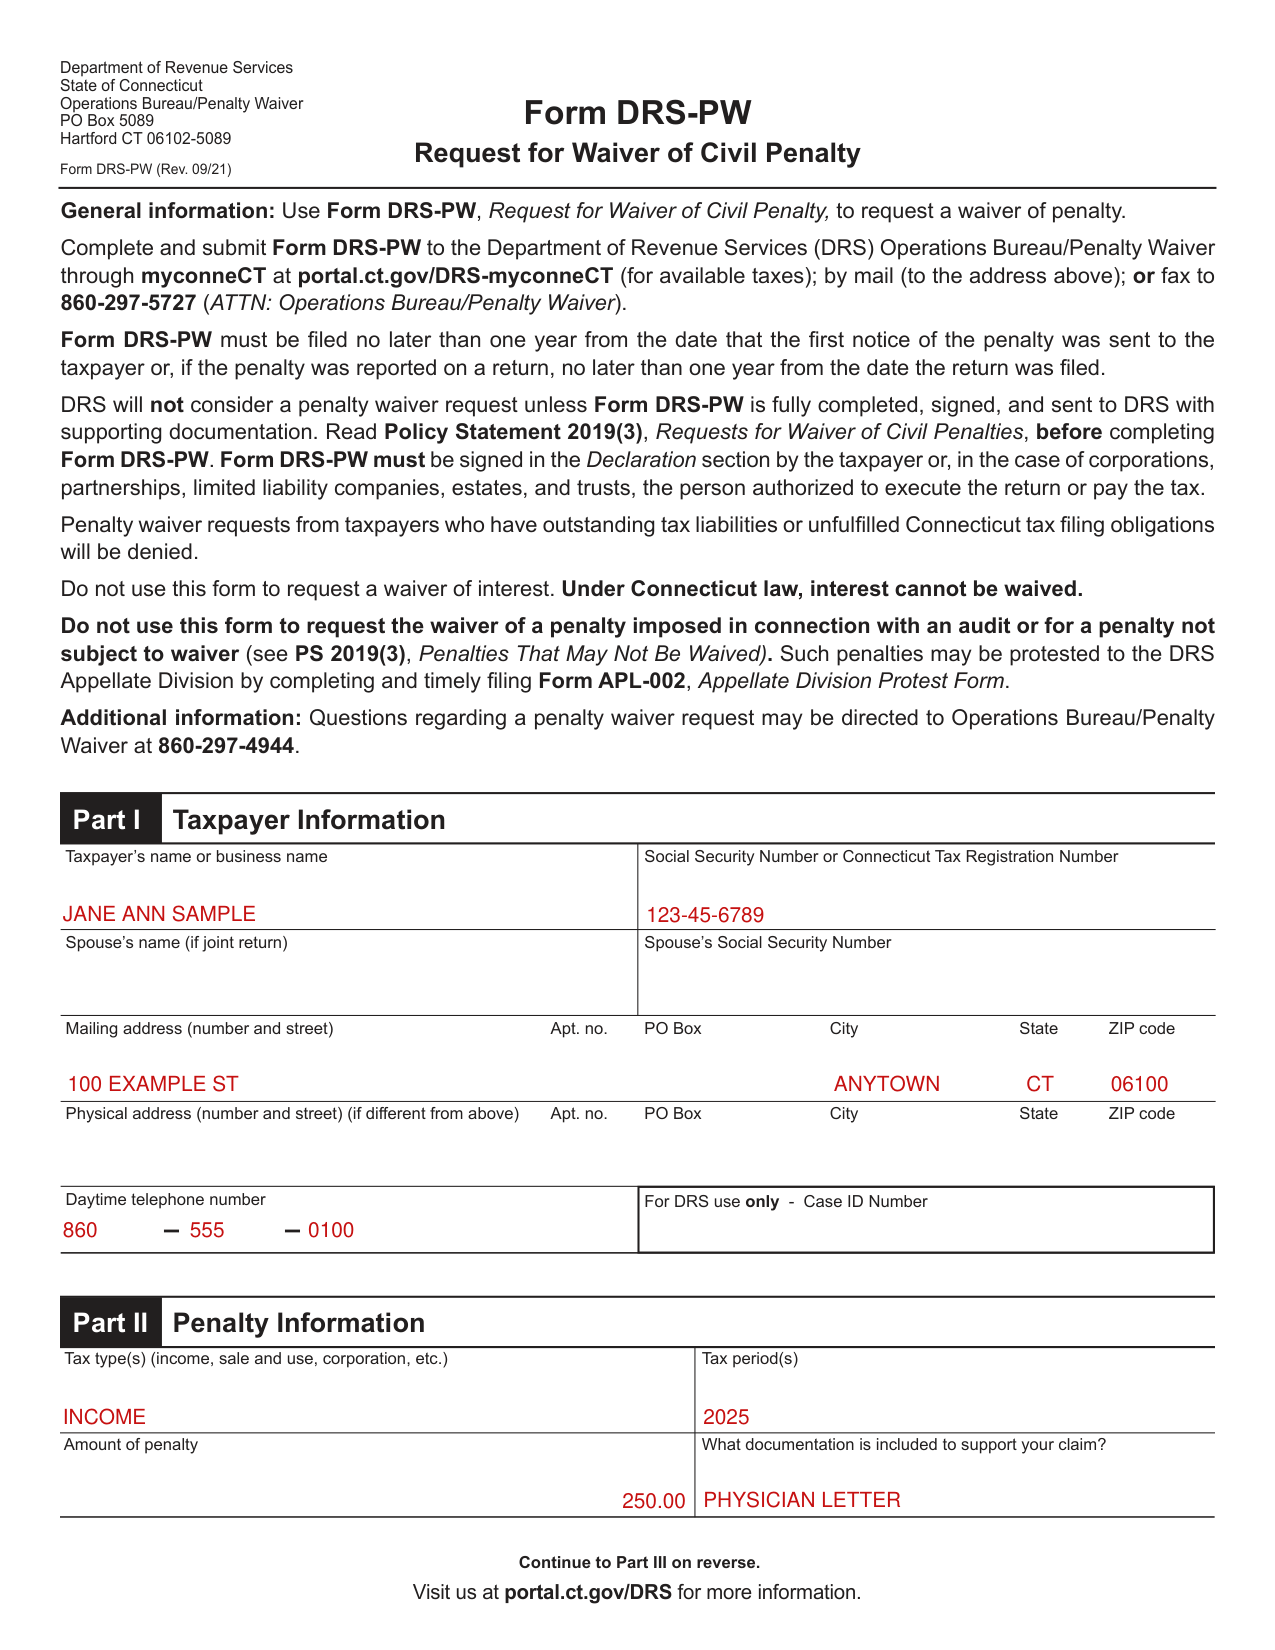
How to fill out Form DRS-PW, box by box
Part I Taxpayer Information
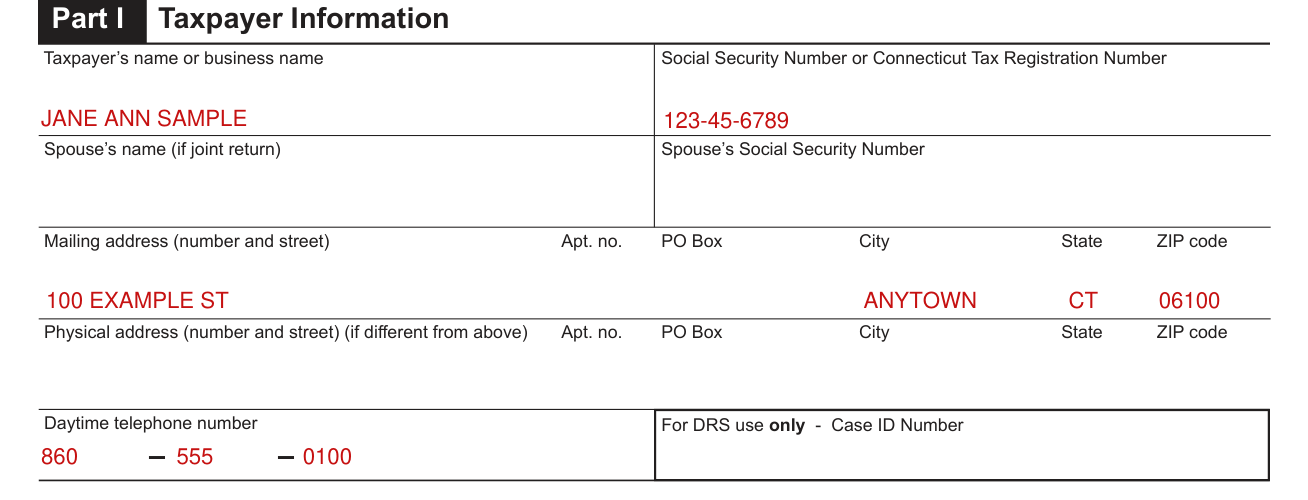
In Part I Taxpayer Information, enter the Taxpayer's name or business name and the Social Security Number or Connecticut Tax Registration Number.
Enter the Spouse's name (if joint return) and the Spouse's Social Security Number.
Enter the Mailing address (number and street), Apt. no., PO Box, City, State and ZIP code. Enter the Physical address (number and street) (if different from the Mailing address), Apt. no., PO Box, City, State and ZIP code.
Enter the Daytime telephone number; the Case ID Number is for DRS use only.
Part II Penalty Information
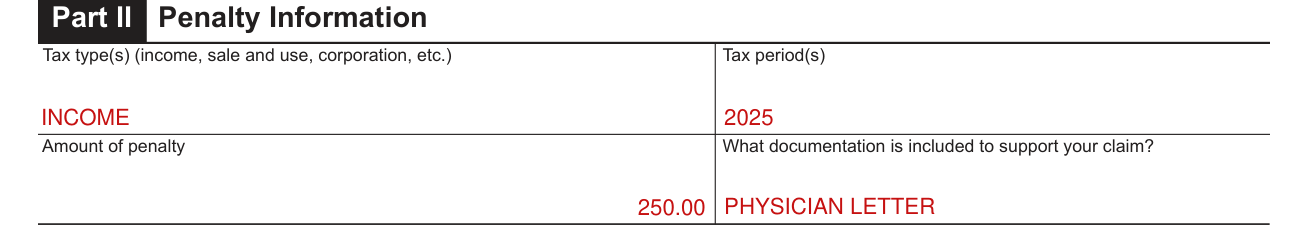
In Part II Penalty Information, enter the Tax type(s) (income, sale and use, corporation, etc.) and the Tax period(s).
Enter the Amount of penalty and what documentation is included to support your claim.
Part III Facts and Circumstances
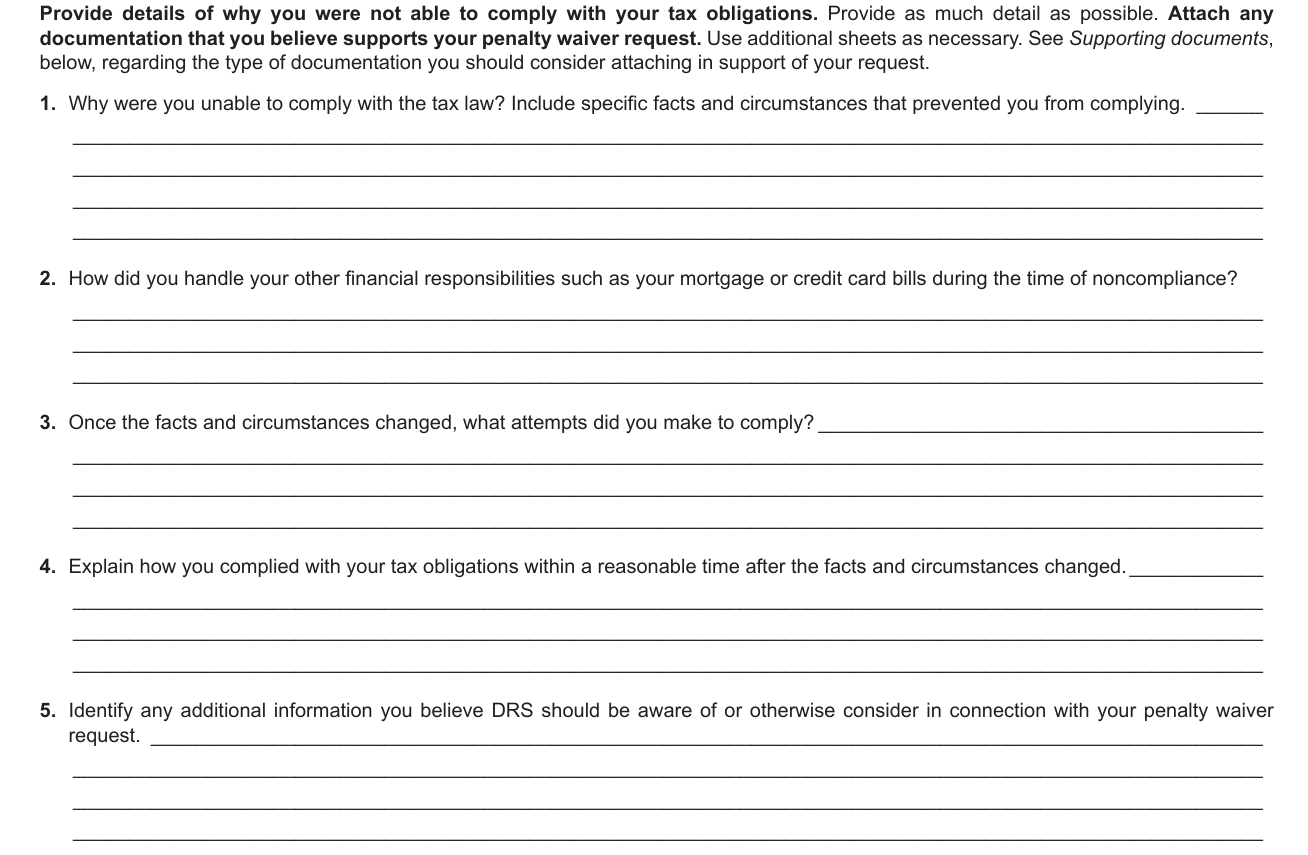
In Part III Facts and Circumstances, provide details of why you were not able to comply with your tax obligations. Provide as much detail as possible. Use additional sheets as necessary.
1. Why were you unable to comply with the tax law? Include specific facts and circumstances that prevented you from complying.
2. How did you handle your other financial responsibilities such as your mortgage or credit card bills during the time of noncompliance?
3. Once the facts and circumstances changed, what attempts did you make to comply?
4. Explain how you complied with your tax obligations within a reasonable time after the facts and circumstances changed.
5. Identify any additional information you believe DRS should be aware of or otherwise consider in connection with your penalty waiver request.
Declaration
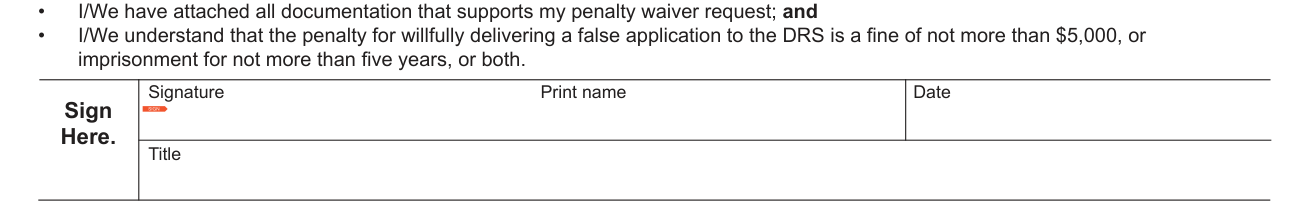
In the Declaration, you declare under the penalty of law that: you have read and understand the provisions of PS 2019(3); you have no outstanding tax liability; you have no unfulfilled Connecticut tax filing obligations with DRS; you have answered each question to the best of your knowledge and belief; and you have attached all documentation that supports your penalty waiver request.
Sign on the Signature line, then enter Print name, Date and Title.
More rules for Form DRS-PW
Use Form DRS-PW, Request for Waiver of Civil Penalty, to request a waiver of penalty.
Other situations
A waiver of interest or of a penalty imposed in connection with an audit
Do not use this form to request a waiver of interest. Under Connecticut law, interest cannot be waived.
Do not use this form to request a waiver of a penalty imposed in connection with an audit or for a penalty not subject to waiver (see PS 2019(3), Penalties That May Not Be Waived). Such penalties may be protested to the DRS Appellate Division by completing and timely filing Form APL-002, Appellate Division Protest Form.
You are claiming loss of business records
Supporting documents: What type of documentation should you consider attaching to your penalty waiver request? The type of supporting documentation will depend on the basis of your request.
If you are claiming the noncompliance was due to a loss of business records necessary to prepare a tax return as a result of fire or other casualty, you should provide copies of police or fire reports and documentation from your insurance company.
If DRS determines there was sufficient time to reconstruct the lost records before the due date, the failure to comply will not be due to reasonable cause.
You are claiming a serious illness
If you are claiming the noncompliance was due to a serious illness, you should provide letters from physicians or other medical providers detailing the illness and explaining how that illness (or treatments associated therewith) impacted your ability to comply with your Connecticut tax obligations.
Common questions about Form DRS-PW
Is there a deadline?
Form DRS-PW must be filed no later than one year from the date that the first notice of the penalty was sent to the taxpayer or, if the penalty was reported on a return, no later than one year from the date the return was filed.
Where do I file it?
Complete and submit Form DRS-PW to the Department of Revenue Services (DRS) Operations Bureau/Penalty Waiver through myconneCT at portal.ct.gov/DRS-myconneCT (for available taxes); by mail to Operations Bureau/Penalty Waiver, PO Box 5089, Hartford CT 06102-5089; or fax to 860-297-5727 (ATTN: Operations Bureau/Penalty Waiver).
Is there a penalty?
In the Declaration, you understand that the penalty for willfully delivering a false application to the DRS is a fine of not more than $5,000, or imprisonment for not more than five years, or both (checked November 8, 2026).
Where to get help with Form DRS-PW
Questions regarding a penalty waiver request may be directed to Operations Bureau/Penalty Waiver at 860-297-4944.
Sources
[1] Form DRS-PW (Rev. 09/21), Request for Waiver of Civil Penalty, Connecticut Department of Revenue Services (the Official source link on this page).