

Form ET-101 at a glance
What it is: ET-101 is the Non-Resident South Carolina Preliminary Estate Tax Notice to Probate Judge, to be filed by personal representative, or person in possession of property.
Who signs: Signature - The signature of one personal representative is sufficient.
In the case of a non-resident decedent, at such time as Exemplification or Petition for Letters of Ancillary Administration is filed with the Probate Judge, this form must be executed, in duplicate, and filed with the Probate Court by the personal representative or person in possession of real and/or tangible personal property having a situs in the State of South Carolina and owned by a non-resident decedent at date of death together with other assets of the decedent's estate regardless of situs.
Persons required to file notice - The duly qualified personal representative, or any person in actual or constructive possession of property included in the statutory gross estate, must file this notice as follows: (1) The personal representative, qualified under an appointment by a court, must file the notice unless at the time of his qualification the notice has already been filed; (2) Any person in actual or constructive possession of property included in the statutory gross estate, must file the notice unless a personal representative qualifies within 3 months after the decedent's death.
Persons in actual or constructive possession of such property include custodians, fiduciaries, transferees, joint owners, partners, distributees, debtors, agents, factors, brokers, bankers, safe deposit companies, and warehouse companies.
A filled-in Form ET-101 example: a personal representative files the notice
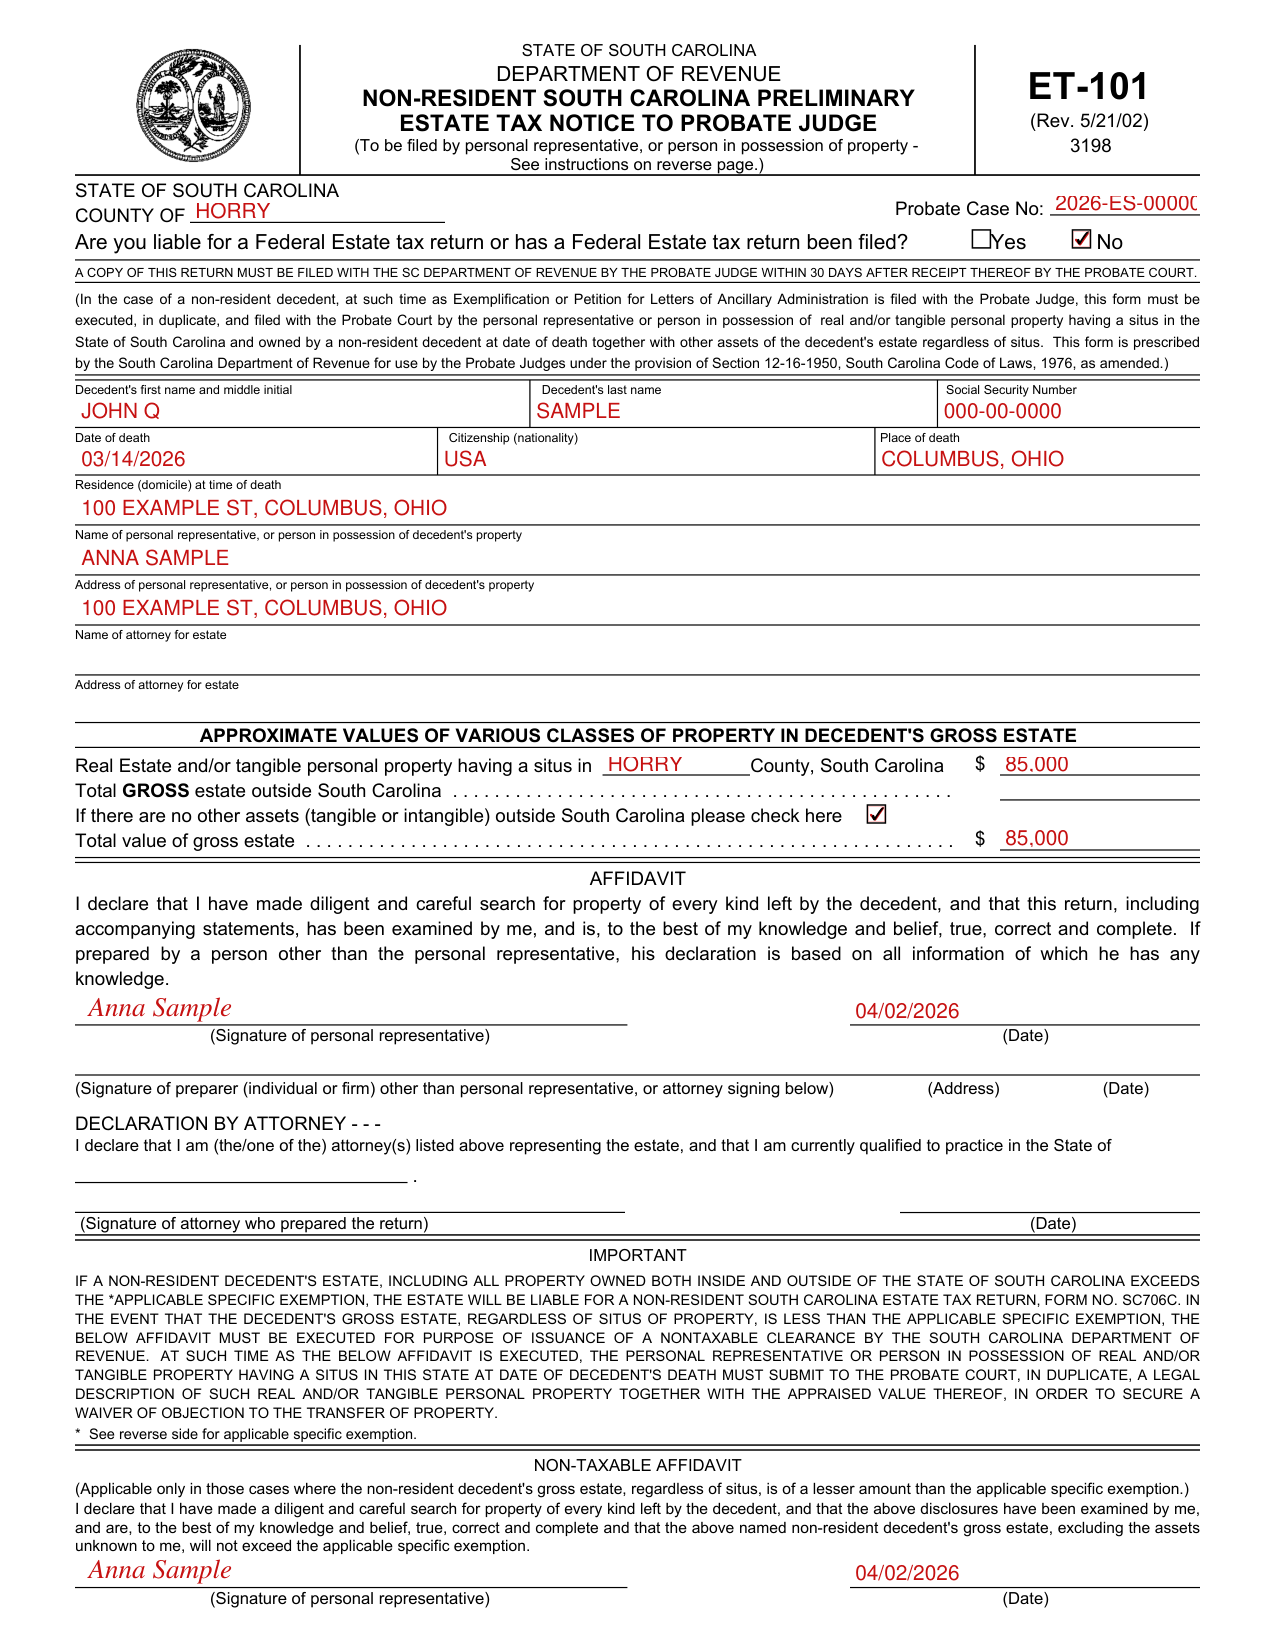
How to fill out Form ET-101, box by box
County, probate case number and Federal Estate tax return

Enter the COUNTY OF and the Probate Case No.
Check Yes or No: Are you liable for a Federal Estate tax return or has a Federal Estate tax return been filed?
The decedent
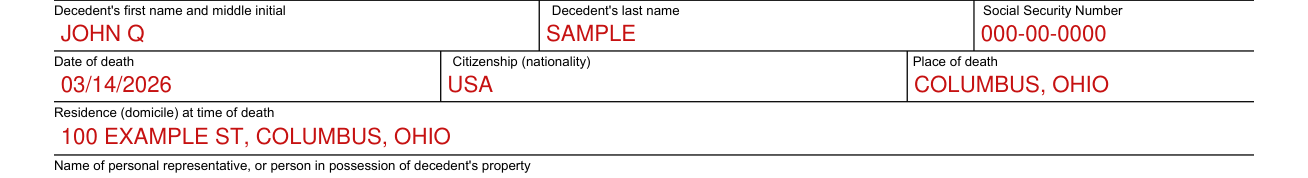
Enter the Decedent's first name and middle initial, the Decedent's last name and the Social Security Number.
Enter the Date of death, the Citizenship (nationality) and the Place of death.
Enter the Residence (domicile) at time of death.
Personal representative

Enter the Name and the Address of personal representative, or person in possession of decedent's property.
Attorney for the estate
Enter the Name of attorney for estate and the Address of attorney for estate.
Approximate values of various classes of property
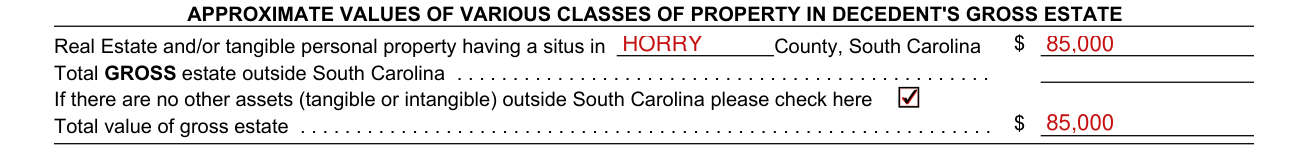
Enter the approximate values of various classes of property in decedent's gross estate.
Enter the value of Real Estate and/or tangible personal property having a situs in the County, South Carolina.
Enter the Total GROSS estate outside South Carolina.
If there are no other assets (tangible or intangible) outside South Carolina please check here.
Enter the Total value of gross estate.
Affidavit
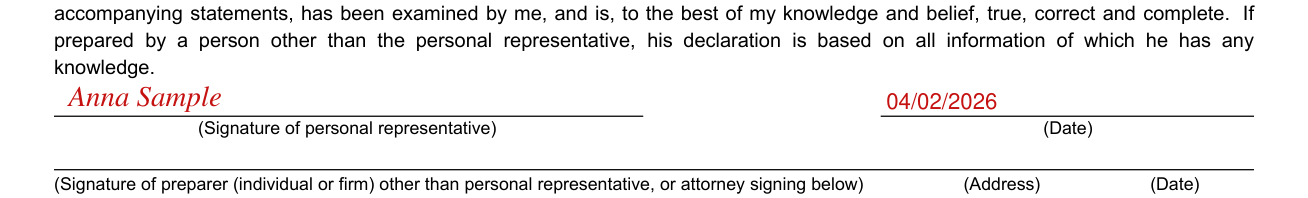
Affidavit: "I declare that I have made diligent and careful search for property of every kind left by the decedent, and that this return, including accompanying statements, has been examined by me, and is, to the best of my knowledge and belief, true, correct and complete. If prepared by a person other than the personal representative, his declaration is based on all information of which he has any knowledge."
The personal representative signs on the (Signature of personal representative) line and enters the (Date).
A preparer other than the personal representative, or an attorney signing, signs on the Signature of preparer line (individual or firm) and enters the (Address) and (Date).
Declaration by attorney

By signing the Declaration by attorney, the attorney declares to be one of the attorneys representing the estate and currently qualified to practice in the State entered.
The attorney who prepared the return signs on the (Signature of attorney who prepared the return) line and enters the (Date).
Non-taxable affidavit
If a non-resident decedent's estate, including all property owned both inside and outside of the State of South Carolina exceeds the *applicable specific exemption, the estate will be liable for a non-resident South Carolina estate tax return, Form No. SC706C.
In the event that the decedent's gross estate, regardless of situs of property, is less than the applicable specific exemption, the affidavit must be executed for purpose of issuance of a nontaxable clearance by the South Carolina Department of Revenue.
At such time as the affidavit is executed, the personal representative or person in possession of real and/or tangible property having a situs in this state at date of decedent's death must submit to the Probate Court, in duplicate, a legal description of such real and/or tangible personal property together with the appraised value thereof, in order to secure a waiver of objection to the transfer of property.
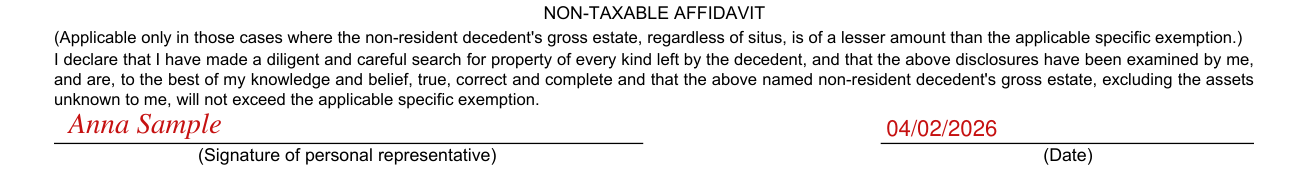
Non-taxable affidavit (Applicable only in those cases where the non-resident decedent's gross estate, regardless of situs, is of a lesser amount than the applicable specific exemption.) "I declare that I have made a diligent and careful search for property of every kind left by the decedent, and that the disclosures have been examined by me, and are, to the best of my knowledge and belief, true, correct and complete and that the non-resident decedent's gross estate, excluding the assets unknown to me, will not exceed the applicable specific exemption."
More rules for Form ET-101
Lien - A lien upon the property of a non-resident decedent having a situs in this state for the estate tax is provided by Section 12-16-1510, South Carolina Code of Laws, 1976, as amended.
Common questions about Form ET-101
Who signs it?
Signature - The signature of one personal representative is sufficient. If this form is filed by a person other than the personal representative, such person must sign this form and should use a descriptive title.
Is there a deadline?
Time for filing notice - In the absence of an ancillary administration in this state, the notice must be filed together with exemplifications with the Probate Judge of the county in which the property is located, within 90 days from date of death.
Where do I file it?
If the property is in several counties, file in the county in which the greater part of the property is located, within 90 days after date of death. When an ancillary administration is commenced, the notice must accompany the Petition for Letters of Ancillary Administration.
Is there a penalty?
Penalties - Penalties are provided for under Chapter 54 of Title 12.
Sources
[1] Form ET-101 (Rev. 5/21/02), South Carolina Department of Revenue (the Official source link on this page).