


Form REV-1630 at a glance
What it is: REV-1630 is the 2025 Underpayment of Estimated Tax by Individuals; use it to determine if you paid enough estimated tax in each of the four payment periods (Section I).
Where and when to file: Estimated payment due dates: a April 15, 2025; b June 16, 2025; c Sept. 15, 2025; d Jan. 15, 2026. If you are using this form to calculate penalty on your 2025 return, enclose a copy of this form (including applicable worksheet) with Form PA-40.
Taxpayers who do not make the correct amount of estimated payments or those who do not meet any of the exceptions to the interest penalty and have an estimated underpayment penalty may complete the form to determine the amount of their estimated underpayment penalty.
Taxpayers who meet the qualifications for Exception 1 for one or more of the estimated tax payment periods may complete the form to calculate the penalty or to show why the penalty should not be applied.
Use this form to determine if any exceptions to the interest penalty apply (Section II). If an exception does not apply, use this form to calculate the interest due (Section III).
This form must be filed even if one of the exceptions applies.
A filled-in Form REV-1630 example: a filer stops at Line 3
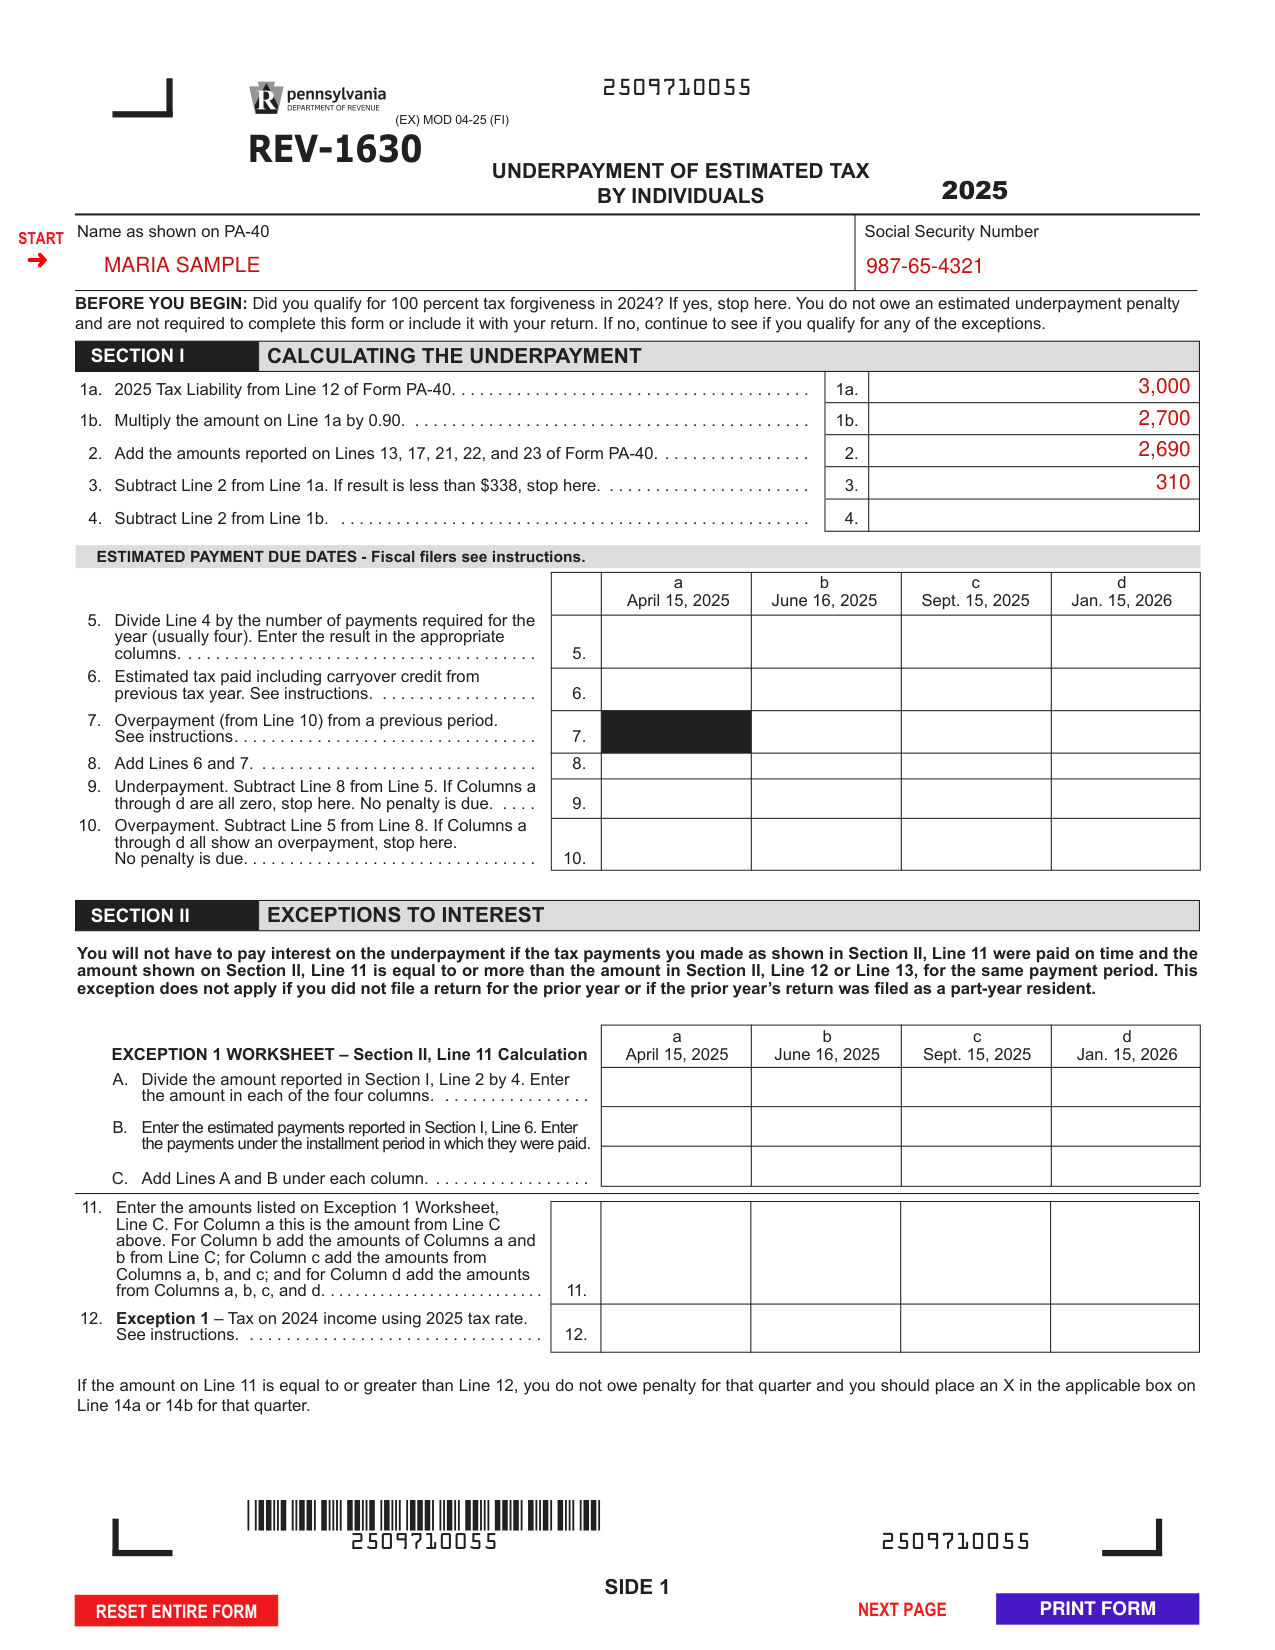
How to fill out Form REV-1630, box by box
Name as shown on PA-40 and Social Security Number

If a jointly filed return, enter the name of the primary taxpayer (name shown first on the PA-40, Personal Income Tax Return). Enter the Social Security number (SSN) of the taxpayer.
Calculating the underpayment, Lines 1a to 4
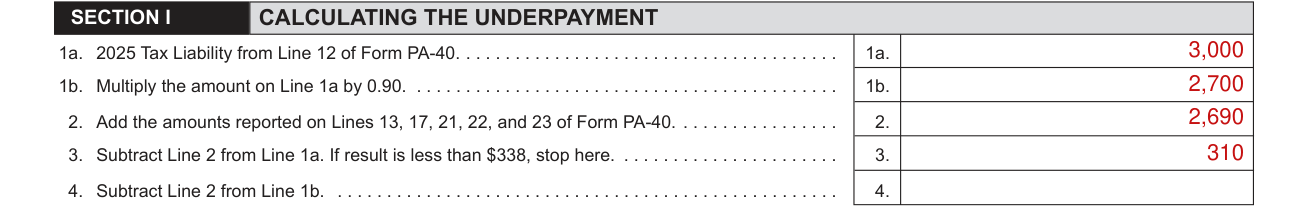
Insert the tax liability figure from Line 12 of your 2025 PA-40 tax return.
Calculate 90 percent of Line 1a by multiplying Line 1a by 0.90.
Add together the following lines from Form PA-40: Line 13 (Total PA Tax Withheld), Line 17 (Nonresident Tax Withheld), Line 21 (Tax Forgiveness Credit), Line 22 (Resident Credit), and Line 23 (Total Other Credits). If Line 2 is more than Line 1b, you do not owe a penalty and do not need to complete this form.
Subtract Line 2 from Line 1a. If the amount is $338 or more, complete Lines 4 through 10 (checked November 8, 2026). If less than $338, you did not owe estimated income tax and do not have to complete this form (checked November 8, 2026).
Subtract Line 2 from Line 1b. This amount is used to determine if you have an underpayment. If you have an underpayment, the penalty is calculated on this amount.
Calculating the underpayment, Lines 5 to 10
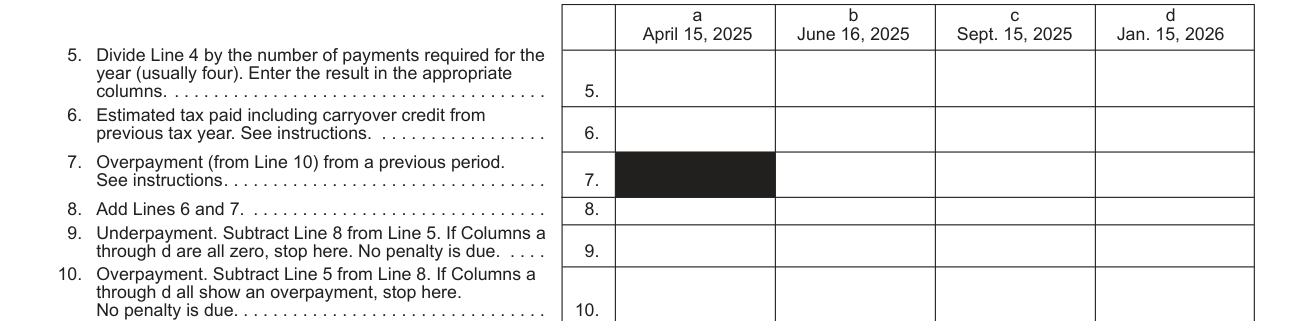
Divide Line 4 by 4 and enter the amount in each of the four Columns a through d.
Line 6 represents the timely payments credited to your account for each of the four payment due dates. If you made a payment after the due date, do not include that amount on Line 6.
In Column a, enter the amount of 2025 estimated tax payment(s) made on or before April 15 intended for the first estimated tax payment due date.
If you have an overpayment on Line 10 for the prior payment period, enter that amount. This does not apply to the April 17th payment period (Column a).
Add Lines 6 and 7 for each of the columns to determine the total payments applied to the payment period.
If Line 5 is greater than Line 8 for any column, calculate the amount of the underpayment for the payment period by subtracting Line 8 from Line 5. If all Columns 9a through 9d are zero, stop here. You do not owe the interest penalty.
If Line 8 is greater than Line 5 for any column, subtract Line 5 from Line 8 and enter it in the appropriate column and on Line 7 of the next payment period.
Exceptions to interest, Exception 1 Worksheet
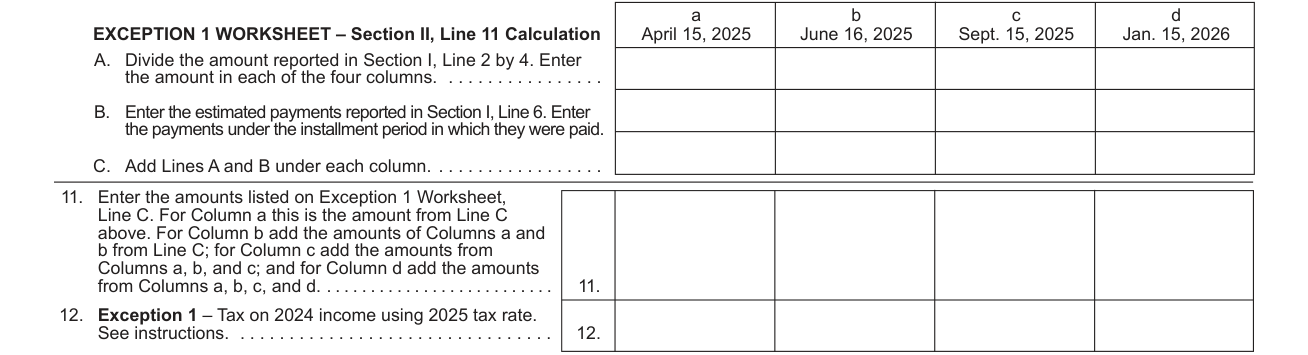
This exception does not apply if you did not file a return for the prior year or if the prior year's return was filed as a part-year resident.
Divide the amount reported in Section I, Line 2 by 4. Enter the amount in each of the four columns.
Enter the estimated payments reported in Section I, Line 6. Enter the payments under the installment period in which they were paid.
Add Lines A and B under each column.
11. Enter the amounts listed on Exception 1 Worksheet, Line C. For Column a this is the amount from Line C of the Exception 1 Worksheet. For Column b add the amounts of Columns a and b from Line C; for Column c add the amounts from Columns a, b, and c; and for Column d add the amounts from Columns a, b, c, and d.
For Line 12, Exception 1, tax on 2024 income using 2025 tax rate: to calculate, multiply Pennsylvania taxable income from your 2024 return by 3.07 percent (0.0307). From this amount, subtract the amount of the Tax Forgiveness Credit on Line 21 of your 2024 return and enter the amount in Column d. Enter 25 percent of the Column d amount in Column a, 50 percent of the Column d amount in Column b, and 75 percent of the Column d amount in Column c.
If the amount on Line 11 is equal to or greater than the amount on Line 12 in any of the columns, you do not owe interest for that payment period and you should place an X in the applicable line 14a or 14b for that payment period. If the amount on Line 11 is less than the amount on Line 12 for any payment period, continue on to exception 2 for those periods.
Exception 2 Worksheet, Line 13
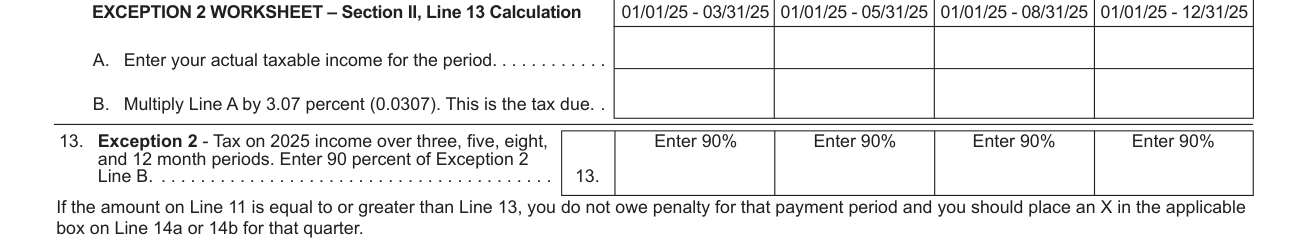
Use this worksheet if your income was earned unevenly throughout 2025 and your 2025 estimated tax payments, tax withholdings and credits equal at least 90 percent of the tax on your taxable income for the periods.
A. Enter your actual taxable income for the period.
B. Multiply Line A by 3.07 percent (0.0307). This is the tax due.
If the amount on Line 11 is equal to or greater than Line 13, you do not owe penalty for that payment period and you should place an X in the applicable box on Line 14a or 14b for that quarter.
Calculating interest, Section III
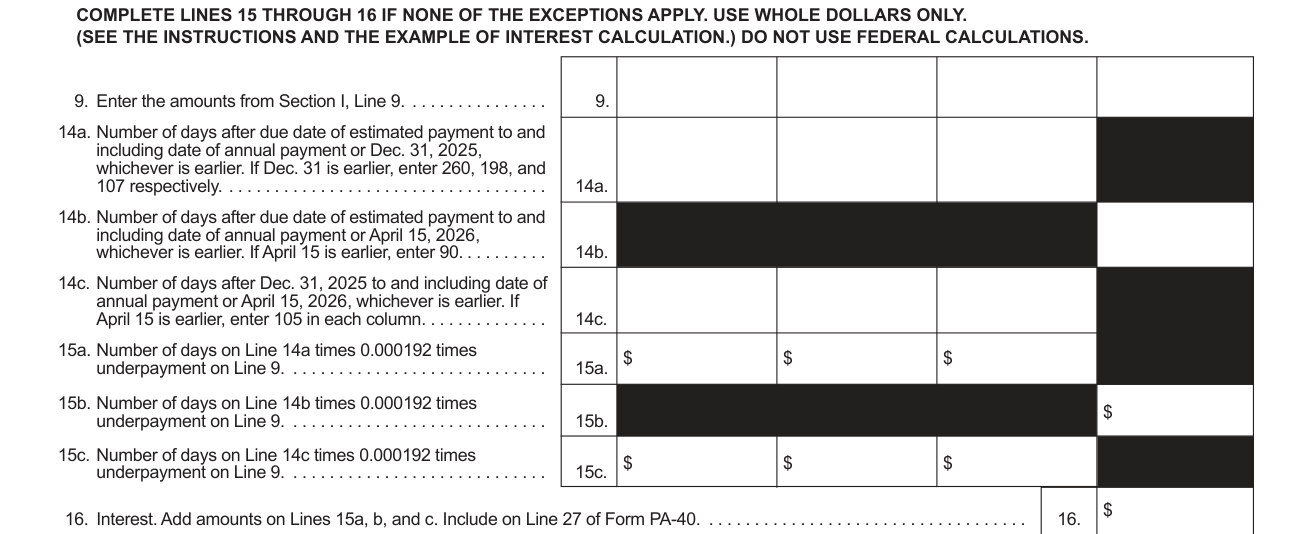
Complete Lines 15 through 16 if none of the exceptions apply. Use whole dollars only. Do not use federal calculations.
Enter the amounts from Section I, Line 9.
Number of days after due date of estimated payment to and including date of annual payment or Dec. 31, 2025, whichever is earlier. If Dec. 31 is earlier, enter 260, 198, and 107 respectively.
Number of days after due date of estimated payment to and including date of annual payment or April 15, 2026, whichever is earlier. If April 15 is earlier, enter 90.
Number of days on Line 14a times 0.000192 times underpayment on Line 9.
Interest. Add amounts on Lines 15a, b, and c. Include on Line 27 of Form PA-40.
Special exception, Lines A and B
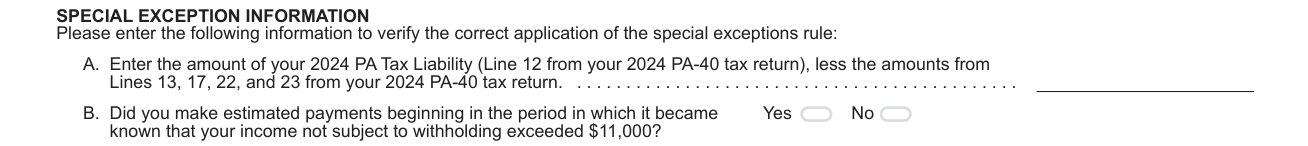
Enter the amount of your 2024 PA Tax Liability (Line 12 from your 2024 PA-40 tax return), less the amounts from Lines 13, 17, 22, and 23 from your 2024 PA-40 tax return.
Did you make estimated payments beginning in the period in which it became known that your income not subject to withholding exceeded $11,000 (checked November 8, 2026)?
If the amount for Line A is $338 or greater, or if you answer "No" to Line B, you do not qualify for the special exception (checked November 8, 2026).
More rules for Form REV-1630
A different exception may apply for each payment period.
Farmers
Farmers
If you meet both of the following tests, you do not owe interest for underpaying estimated tax: 1) Your gross income from farming for the taxable year is at least 2/3 of your gross income from all sources for the taxable year; and
2) You filed your tax return and paid the entire amount due by March 1 of the following year, or you paid all of your estimated tax by Jan. 15, 2026. If you meet these tests, please complete REV-1630A, Underpayment of Estimated Tax by Individual Farmers.
If you do not meet both tests, you are not considered a farmer for PA tax purposes. Please complete this form to see if you qualify for any other exceptions to the interest penalty.
Before you go
Did you qualify for 100 percent tax forgiveness in 2024? If yes, stop here. You do not owe an estimated underpayment penalty and are not required to complete this form or include it with your return. If no, continue to see if you qualify for any of the exceptions.
Common questions about Form REV-1630
Is there a penalty?
The estimated underpayment penalty is an interest penalty for the failure to make estimated tax payments or the failure to make estimated tax payments in the correct amount.
Sources
[1] Form REV-1630 (2025), Underpayment of Estimated Tax by Individuals, Pennsylvania Department of Revenue (the Official source link on this page).