
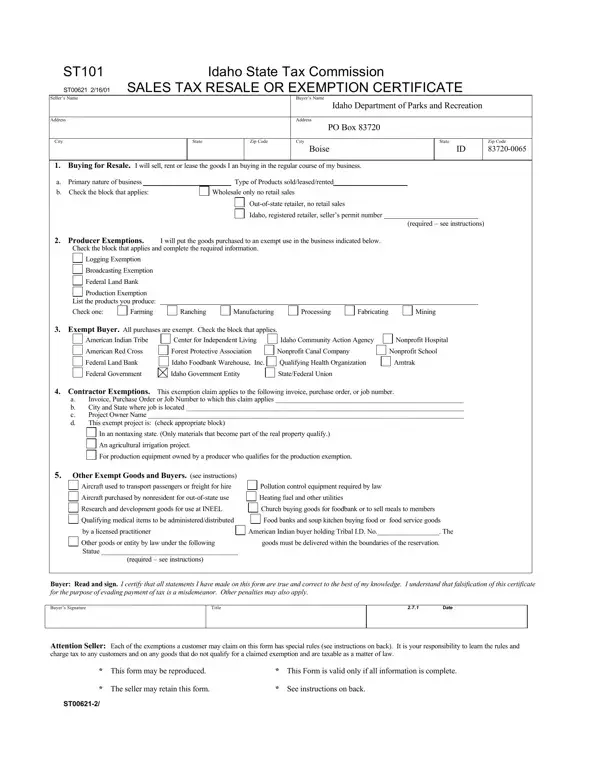

Form ST-101 at a glance
What it is: Form ST-101 is the Sales Tax Resale or Exemption Certificate; contractors improving real property use Form ST-103C.
Who signs: Buyer's signature, Buyer's name (please print), Title, Buyer's federal EIN or driver's license number and state of issue, and Date are each marked (required).
Buyer: Complete the exemption that applies to your purchase. If the goods you're buying don't qualify for the exemption you're claiming, you'll be responsible for the tax due.
A filled-in Form ST-101 example: a cafe buys goods for resale
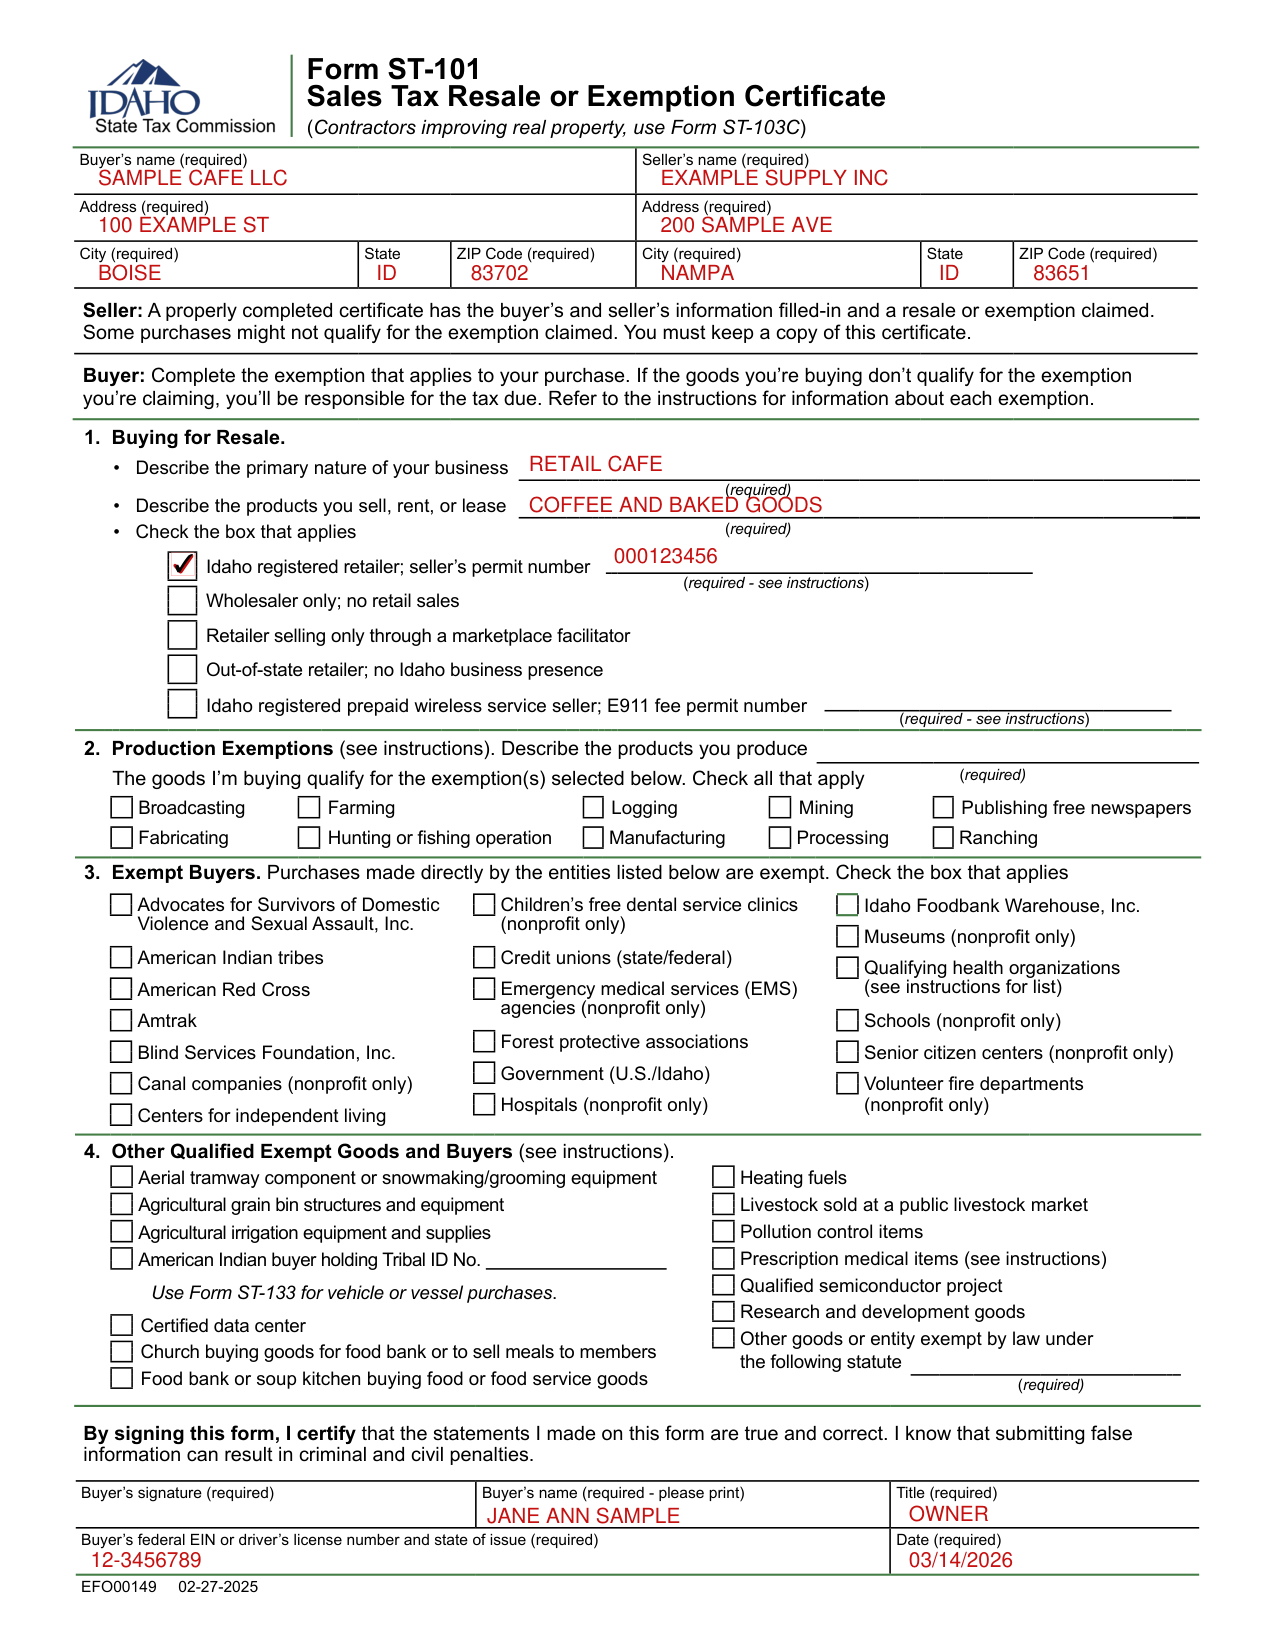
How to fill out Form ST-101, box by box
Buyer's and seller's information
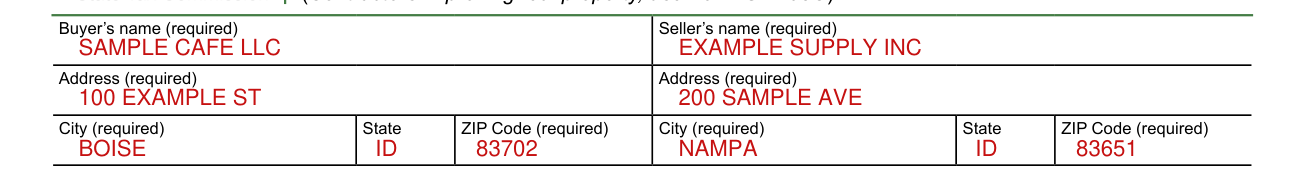
Seller: A properly completed certificate has the buyer's and seller's information filled-in and a resale or exemption claimed.
Buyer's name, Seller's name, Address, City, State and ZIP Code are each marked (required) for the buyer and the seller.
1. Buying for Resale
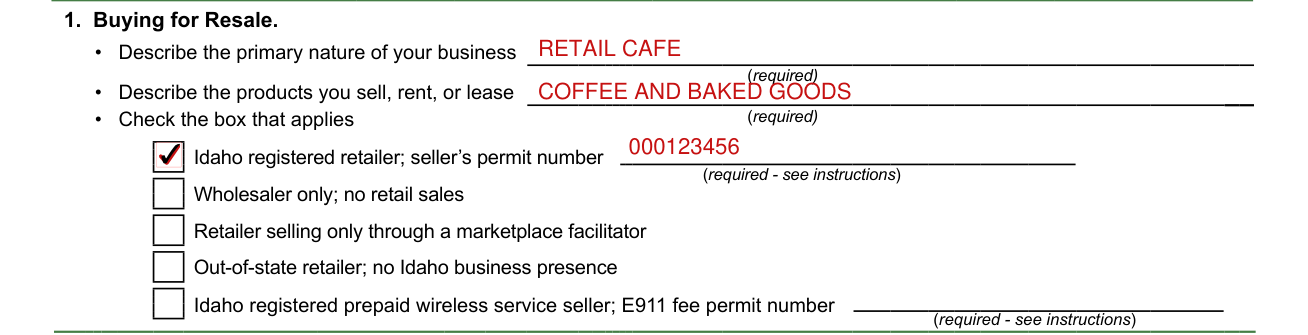
Describe the primary nature of your business.
Describe the products you sell, rent, or lease (required).
Check the box that applies (required): Idaho registered retailer with a seller's permit number (required), Wholesaler only with no retail sales, Retailer selling only through a marketplace facilitator, Out-of-state retailer with no Idaho business presence, or Idaho registered prepaid wireless service seller with an E911 fee permit number (required).
Buyers must have an Idaho seller's or E911 fee permit number unless they're: Wholesalers making no retail sales. Retailers selling only through marketplace facilitators. Out-of-state retailers with no Idaho business presence (e.g., physical location, representatives, employees, etc.).
A marketplace facilitator is a person who provides a marketplace for third-party sellers.
An Idaho seller's or E911 fee permit number has nine digits, such as 000123456.
You can validate a permit number by visiting tax.idaho.gov/validseller or contacting the Tax Commission.
2. Production Exemptions
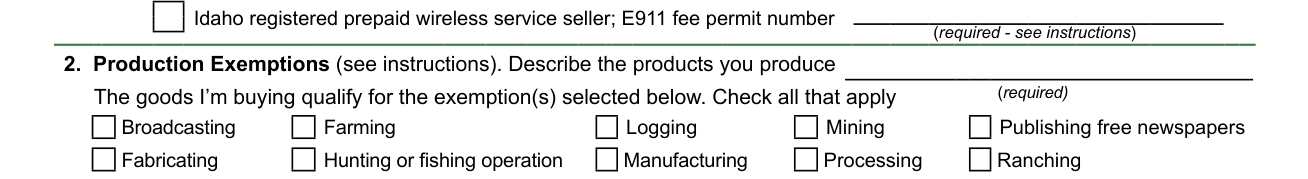
Describe the products you produce.
The goods I'm buying qualify for the exemption(s) selected. Check all that apply (required).
Section 2 - Production Exemptions: Businesses that primarily produce goods for resale don't need to pay tax on qualifying items they directly and primarily use in the production process.
Businesses offering the right to hunt or fish as a taxable activity don't need to pay tax on qualifying items they directly and primarily use in a hunting or fishing activity.
Loggers (63-3622JJ), broadcasters (63-3622S), and publishers of newspapers (63-3622T) that are free to the public and contain at least 10% informational content (not ads) have a similar exemption.
Qualifying businesses must pay sales tax on the following: Goods that become improvements to real property (e.g., fence posts); Goods used in selling or distribution; Janitorial or cleaning equipment and supplies; Maintenance or repair equipment and supplies; Office equipment and supplies; Transportation equipment and supplies; Any licensed motor vehicle, trailer, aircraft, or parts; Recreational vehicle (e.g., snowmobile, ATV, off-highway motorcycle, camper, travel trailer). Seller: For production exemptions, you can stamp or imprint an exemption statement on the front of the invoice.
3. Exempt Buyers
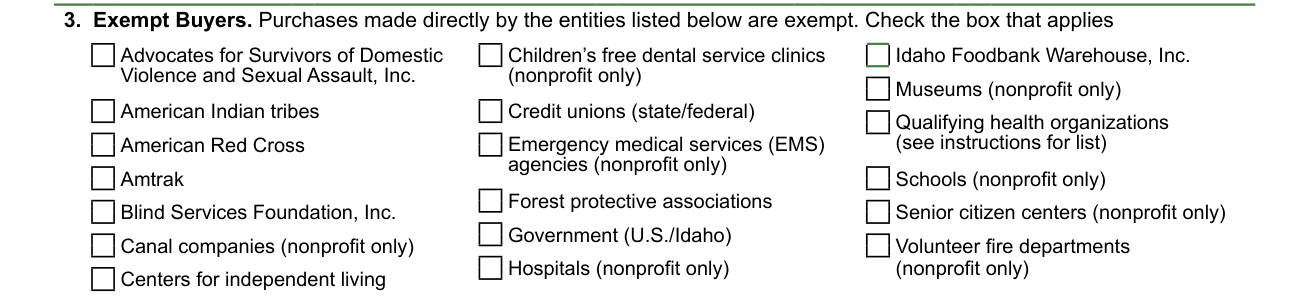
3. Exempt Buyers. Purchases made directly by the entities listed in Section 3 are exempt. Check the box that applies.
American Indian tribes: Only tribal entities qualify.
Government: Only the U.S. government and Idaho state, county, city, and other political subdivisions qualify. Sales to other states and their political subdivisions are taxable.
Hospitals: Only licensed nonprofit hospitals qualify. Nursing homes or similar institutions don't qualify for the hospital exemption.
Certain public or nonprofit schools qualify. These schools include: Colleges and universities; Primary, secondary, and charter schools. Auxiliary organizations such as parent-teacher associations, booster clubs, and alumni groups don't qualify. Schools primarily teaching subjects like business, dance, theater arts, music, cosmetology, writing, and gymnastics don't qualify.
Senior citizen centers: Only nonprofit community centers for senior citizens qualify.
4. Other Qualified Exempt Goods and Buyers
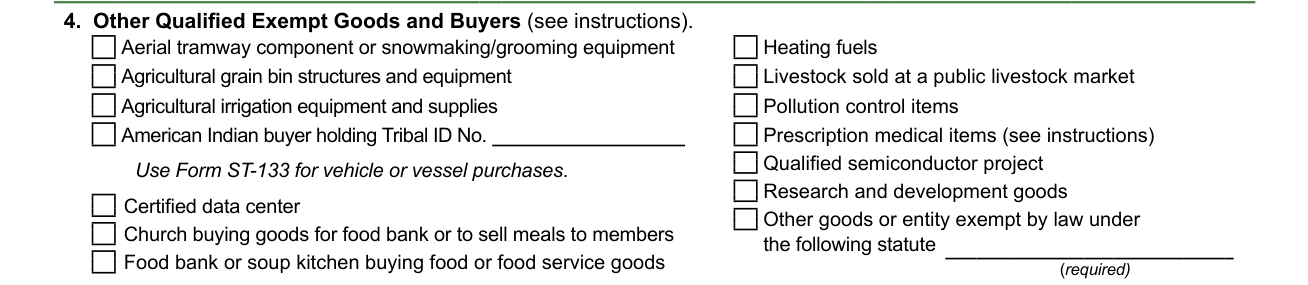
Section 4 - Other Qualified Exempt Goods and Buyers: If buyers claim an exemption that isn't listed on this form, they must mark the “Other” box and list the section of law that applies to the exemption. Otherwise, this certificate isn't valid.
Use Form ST-133 for vehicle or vessel purchases. For Other goods or entity exempt by law, the statute is required.
American Indians: Sales to an enrolled American Indian tribal member are exempt if the goods are delivered on the reservation. The buyer's Tribal Identification Number is required.
Churches: Churches can buy food for meals they sell to members or qualifying goods for their food bank without paying tax.
Food banks and soup kitchens: Food banks and soup kitchens can buy food or other goods used to grow, store, prepare, or serve food exempt from sales tax. The exemption doesn't include licensed motor vehicles or trailers.
Heating fuels: Heating fuels such as wood, coal, petroleum, propane, and natural gas are exempt when purchased to heat any building, or a building under construction, or for domestic home use such as cooking or water heating.
Sales of liquid propane in units of 15 gallons or less that are identified in the vendor's records as cylinder sales are exempt from tax. You don't need a Form ST-101.
Livestock: Sales of cattle, sheep, mules, horses, pigs, and goats are exempt when sold at a public livestock market. Sales of other animals don't qualify.
Prescription medical items: To qualify, the goods must be prescribed to an individual by a licensed practitioner and be included in Idaho Code section 63-3622N.
Signing the certificate
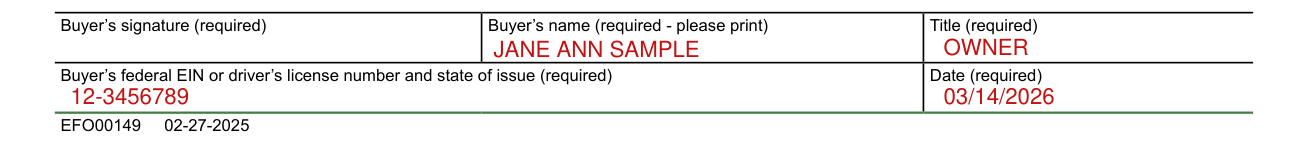
By signing this form, I certify that the statements I made on this form are true and correct. I know that submitting false information can result in criminal and civil penalties.
More rules for Form ST-101
To be valid, the certificate must be fully completed and signed.
The seller must keep the valid form on file.
Common questions about Form ST-101
What is a form ST-101?
Form ST-101 is the Sales Tax Resale or Exemption Certificate; contractors improving real property use Form ST-103C. The seller is responsible for collecting sales tax if the form isn't valid.
Is there a penalty?
A penalty may be imposed for the misuse of an exemption form. If false exempt purchases are repeatedly or intentionally made, a penalty may be assessed at 5% of the sales price or $200, whichever is greater (checked November 1, 2026).
Sources
[1] Form ST-101 (EFO00149 02-27-2025), Sales Tax Resale or Exemption Certificate, Idaho State Tax Commission (the Official source link on this page).