

Form ST-120.1 at a glance
What it is: Form ST-120.1, the New York State and Local Sales and Use Tax Contractor Exempt Purchase Certificate, is to be used only by contractors who are registered with the Tax Department for sales tax purposes.
Who signs: The owner, partner, or authorized person of the purchasing contractor signs and enters the date prepared.
Only a contractor who has a valid Certificate of Authority issued by the Tax Department may use this exempt purchase certificate.
What to bring and attach to Form ST-120.1
Unless otherwise stated, the customer must furnish the contractor a properly completed Form ST-121, Exempt Use Certificate.
A filled-in Form ST-120.1 example: a contractor buys production machinery
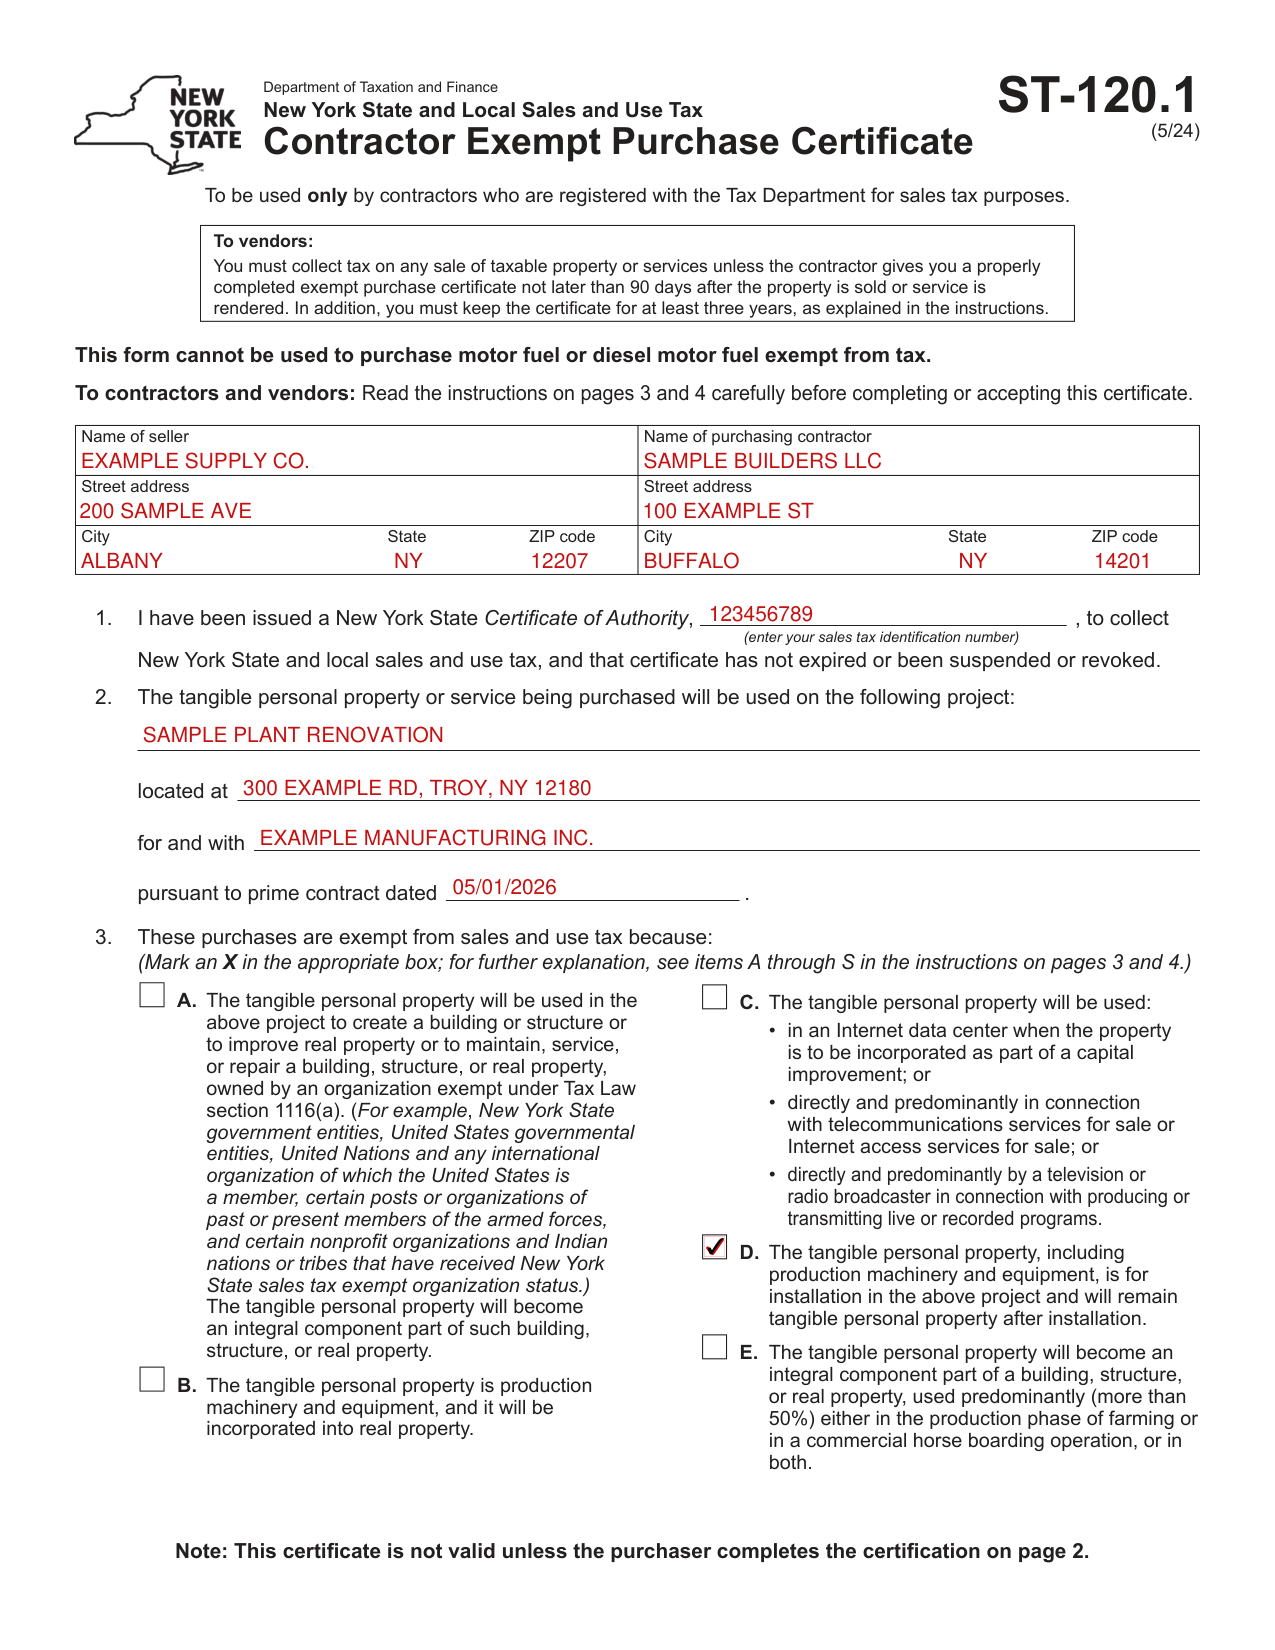
How to fill out Form ST-120.1, box by box
Name of seller and Name of purchasing contractor
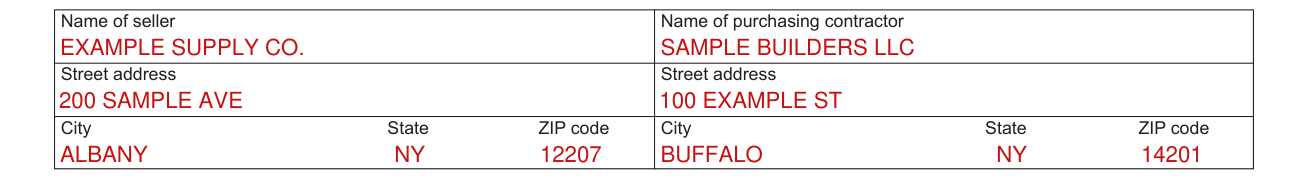
Enter the Name of seller and the Name of purchasing contractor, each with a Street address, City, State and ZIP code.
1. Certificate of Authority

Line 1: enter your sales tax identification number. It states that you have been issued a New York State Certificate of Authority to collect New York State and local sales and use tax, and that the certificate has not expired or been suspended or revoked.
2. The project
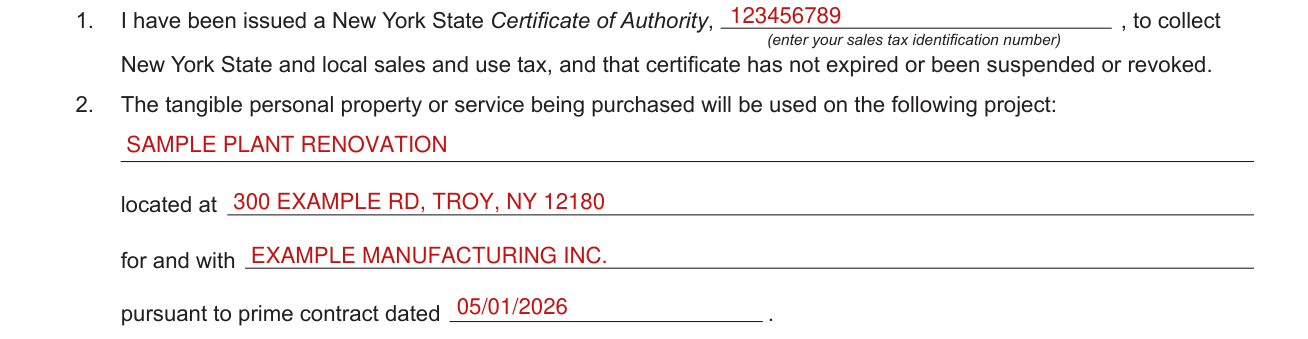
Line 2: fill in the project the tangible personal property or service being purchased will be used on, then fill in what follows "located at", "for and with" and "pursuant to prime contract dated".
3. These purchases are exempt because: page 1
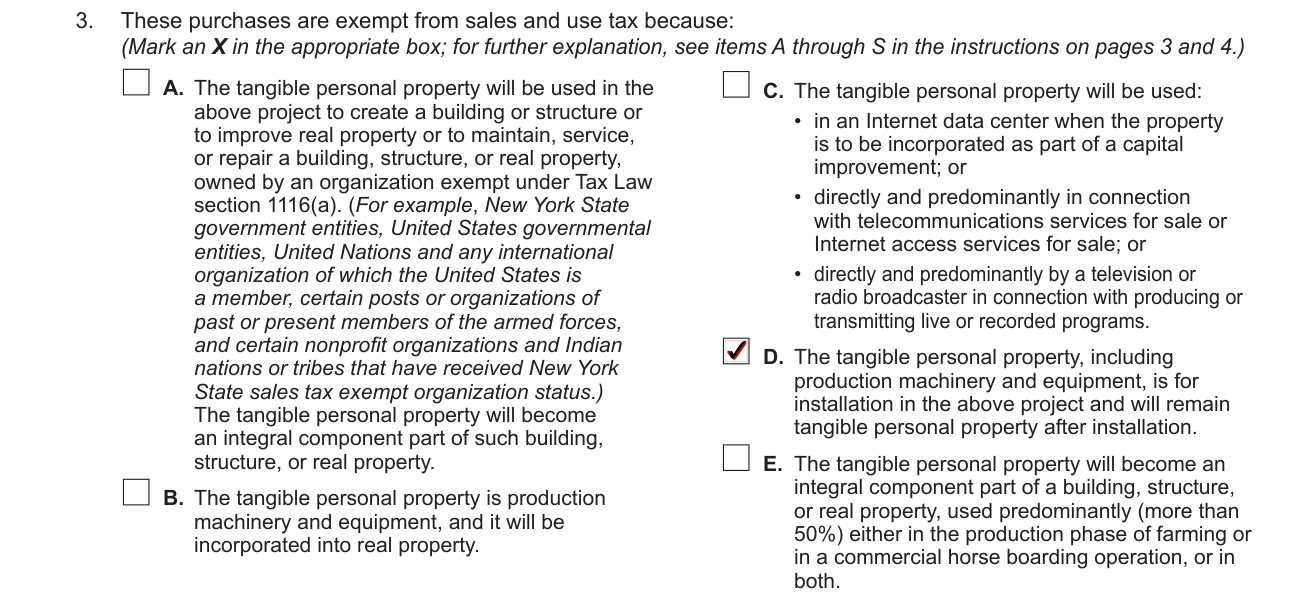
Line 3: these purchases are exempt from sales and use tax because of the box you mark with an X; for further explanation, see the instructions on pages 3 and 4.
A. The tangible personal property will be used in the project to create a building or structure or to improve real property or to maintain, service, or repair a building, structure, or real property, owned by an organization exempt under Tax Law section 1116(a). The tangible personal property will become an integral component part of such building, structure, or real property.
B. The tangible personal property is production machinery and equipment, and it will be incorporated into real property.
C. The tangible personal property will be used: in an Internet data center when the property is to be incorporated as part of a capital improvement; or directly and predominantly in connection with telecommunications services for sale or Internet access services for sale; or directly and predominantly by a television or radio broadcaster in connection with producing or transmitting live or recorded programs.
D. The tangible personal property, including production machinery and equipment, is for installation in the project and will remain tangible personal property after installation.
E. The tangible personal property will become an integral component part of a building, structure, or real property, used predominantly (more than 50%) either in the production phase of farming or in a commercial horse boarding operation, or in both.
3. The tangible personal property and the services: page 2
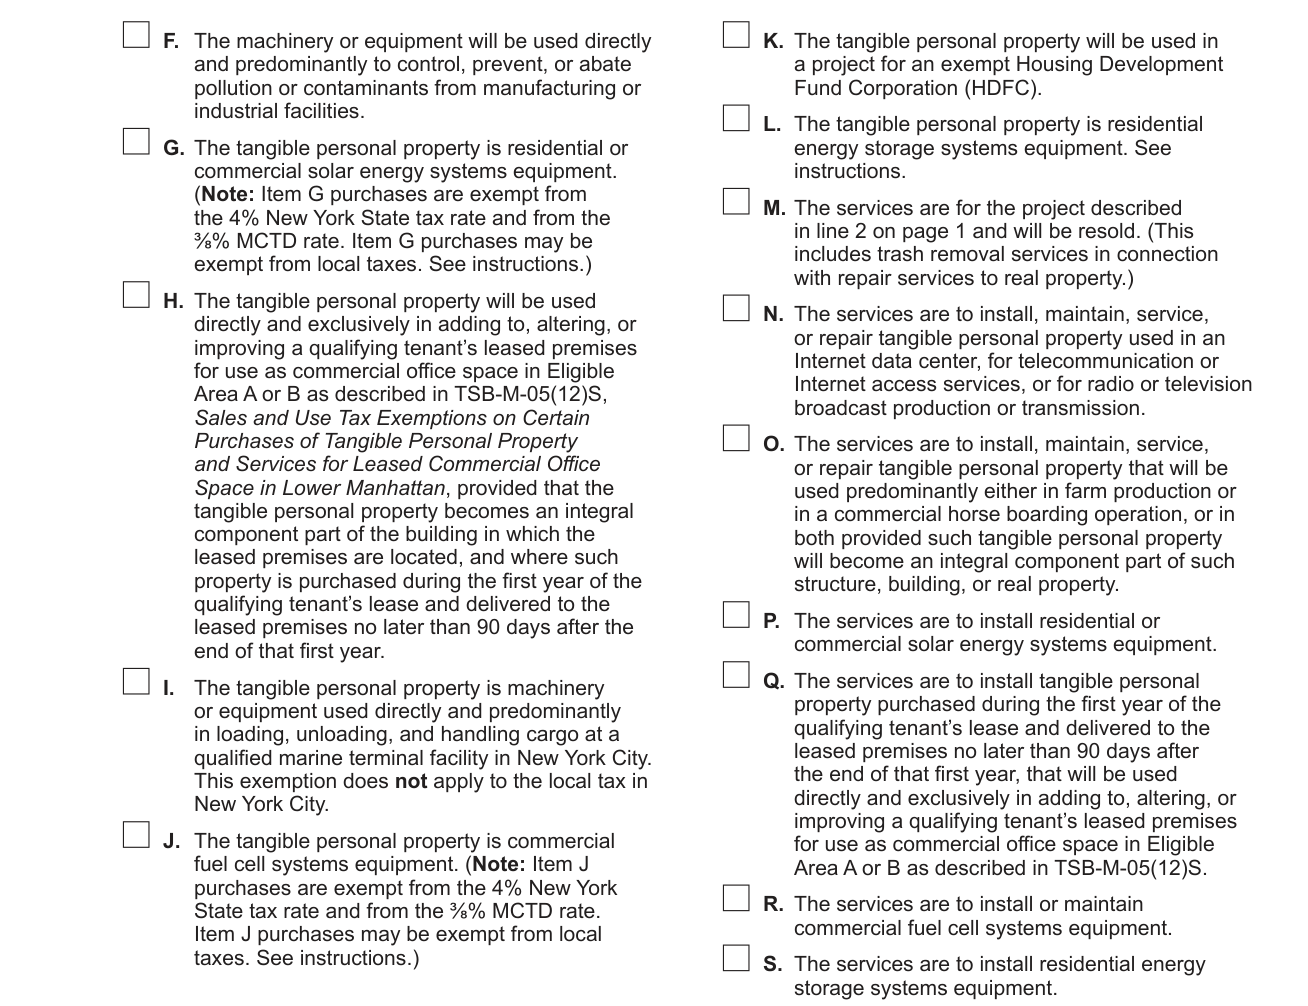
F. The machinery or equipment will be used directly and predominantly to control, prevent, or abate pollution or contaminants from manufacturing or industrial facilities.
G. The tangible personal property is residential or commercial solar energy systems equipment. (Note: Item G purchases are exempt from the 4% New York State tax rate and from the ⅜% MCTD rate. Item G purchases may be exempt from local taxes. See instructions.)
H. The tangible personal property will be used directly and exclusively in adding to, altering, or improving a qualifying tenant's leased premises for use as commercial office space in Eligible Area A or B as described in TSB‑M‑05(12)S, Sales and Use Tax Exemptions on Certain Purchases of Tangible Personal Property and Services for Leased Commercial Office Space in Lower Manhattan, provided that the tangible personal property becomes an integral component part of the building in which the leased premises are located, and where such property is purchased during the first year of the qualifying tenant's lease and delivered to the leased premises no later than 90 days after the end of that first year.
I. The tangible personal property is machinery or equipment used directly and predominantly in loading, unloading, and handling cargo at a qualified marine terminal facility in New York City. This exemption does not apply to the local tax in New York City.
J. The tangible personal property is commercial fuel cell systems equipment. (Note: Item J purchases are exempt from the 4% New York State tax rate and from the ⅜% MCTD rate. Item J purchases may be exempt from local taxes. See instructions.)
K. The tangible personal property will be used in a project for an exempt Housing Development Fund Corporation (HDFC).
L. The tangible personal property is residential energy storage systems equipment. See instructions.
M. The services are for the project described in line 2 on page 1 and will be resold.
N. The services are to install, maintain, service, or repair tangible personal property used in an Internet data center, for telecommunication or Internet access services, or for radio or television broadcast production or transmission.
O. The services are to install, maintain, service, or repair tangible personal property that will be used predominantly either in farm production or in a commercial horse boarding operation, or in both provided such tangible personal property will become an integral component part of such structure, building, or real property.
P. The services are to install residential or commercial solar energy systems equipment.
Q. The services are to install tangible personal property purchased during the first year of the qualifying tenant's lease and delivered to the leased premises no later than 90 days after the end of that first year, that will be used directly and exclusively in adding to, altering, or improving a qualifying tenant's leased premises for use as commercial office space in Eligible Area A or B as described in TSB‑M‑05(12)S.
R. The services are to install or maintain commercial fuel cell systems equipment.
S. The services are to install residential energy storage systems equipment.
Certification and signature
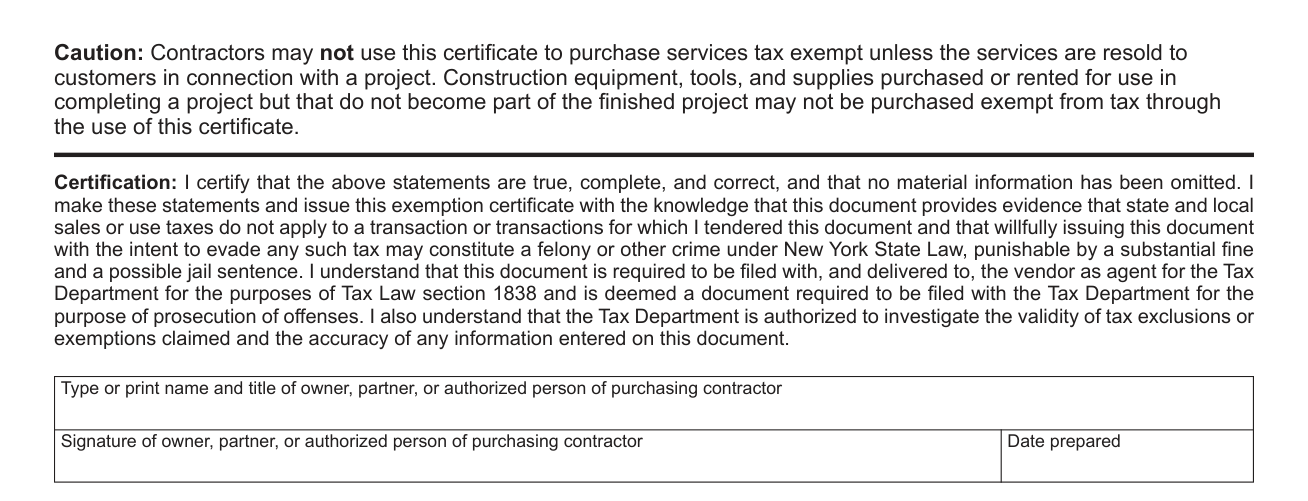
This certificate is not valid unless the purchaser completes the certification on page 2.
Certification: you certify that the statements are true, complete, and correct, and that no material information has been omitted.
Type or print the name and title of the owner, partner, or authorized person of the purchasing contractor.
The owner, partner, or authorized person of the purchasing contractor signs and enters the date prepared.
More rules for Form ST-120.1
This certificate is not valid unless all entries have been completed.
The contractor must use a separate Form ST‑120.1, Contractor Exempt Purchase Certificate, for each project.
Common questions about Form ST-120.1
Is there a deadline?
A vendor must collect tax on any sale of taxable property or services unless the contractor gives the vendor a properly completed exempt purchase certificate not later than 90 days after the property is sold or service is rendered. In addition, the vendor must keep the certificate for at least three years, as explained in the instructions.
Where do I file it?
The contractor must present a properly completed certificate to the vendor to purchase tangible personal property, or to a subcontractor to purchase services tax exempt.
Is there a penalty?
A penalty equal to 100% of the tax due. A $50 penalty for each fraudulent exemption certificate issued (checked October 22, 2026). Criminal felony prosecution, punishable by a substantial fine and a possible jail sentence, and revocation of your Certificate of Authority, if you are required to be registered as a vendor. Substantial penalties will result from misuse of this certificate.
When is this form not the right one?
This form cannot be used to purchase motor fuel or diesel motor fuel exempt from tax. Contractors may not use this certificate to purchase services tax exempt unless the services are resold to customers in connection with a project. Construction equipment, tools, and supplies purchased or rented for use in completing a project but that do not become part of the finished project may not be purchased exempt from tax through the use of this certificate. The contractor may not use this certificate to purchase tangible personal property or services tax exempt on the basis that Form ST-124, Certificate of Capital Improvement, has been furnished by the project owner to the contractor.
Where to get help with Form ST-120.1
Telephone assistance: 518-485-9863.
Sources
[1] Form ST-120.1 (5/24), Contractor Exempt Purchase Certificate, New York State Department of Taxation and Finance (the Official source link on this page).
