
Form T1032 at a glance
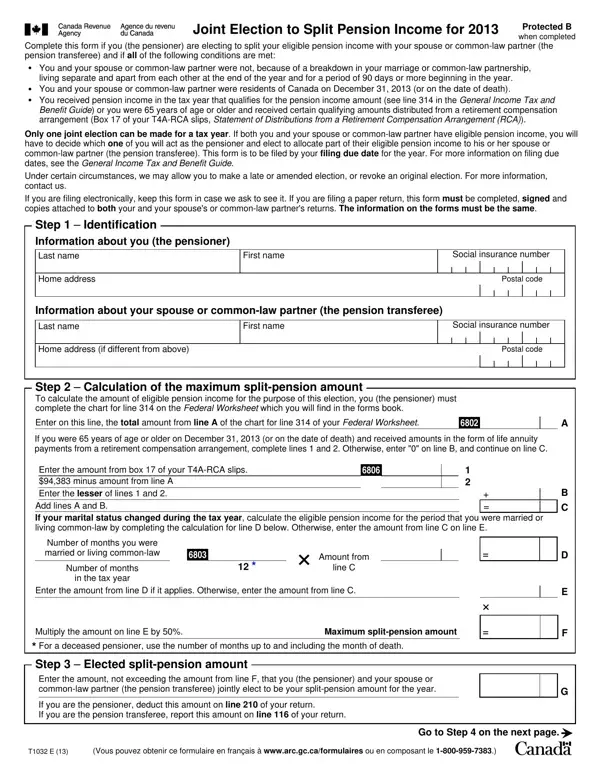
What it is: Form T1032 is the Joint Election to Split Pension Income.
Who signs: Signature of transferring spouse or common-law partner. Signature of receiving spouse or common-law partner.
Complete this form if you (the transferring spouse or common-law partner) are electing to split your eligible pension income with your spouse or common-law partner (the receiving spouse or common-law partner).
You must meet all of the following conditions: You and your spouse or common-law partner were not living separate and apart from each other, because of a breakdown in your marriage or common-law relationship, for a continuous period of 90 days or more which includes December 31, 2025. You and your spouse or common-law partner were residents of Canada on December 31, 2025 (or on the date of death).
You received any of the following amounts in the tax year:
pension income that qualifies for the pension income amount (see line 31400 of the Federal Worksheet), including eligible veterans benefits.
certain qualifying amounts distributed from a retirement compensation arrangement (box 17 of your T4A-RCA slips) and you reached 65 years of age before the end of the tax year.
Only one joint election can be made for a tax year. If both you and your spouse or common-law partner have eligible pension income, you need to decide who will be transferring and who will be receiving. The transferring spouse or common-law partner will be electing to allocate part of the eligible pension income to the receiving spouse or common-law partner.
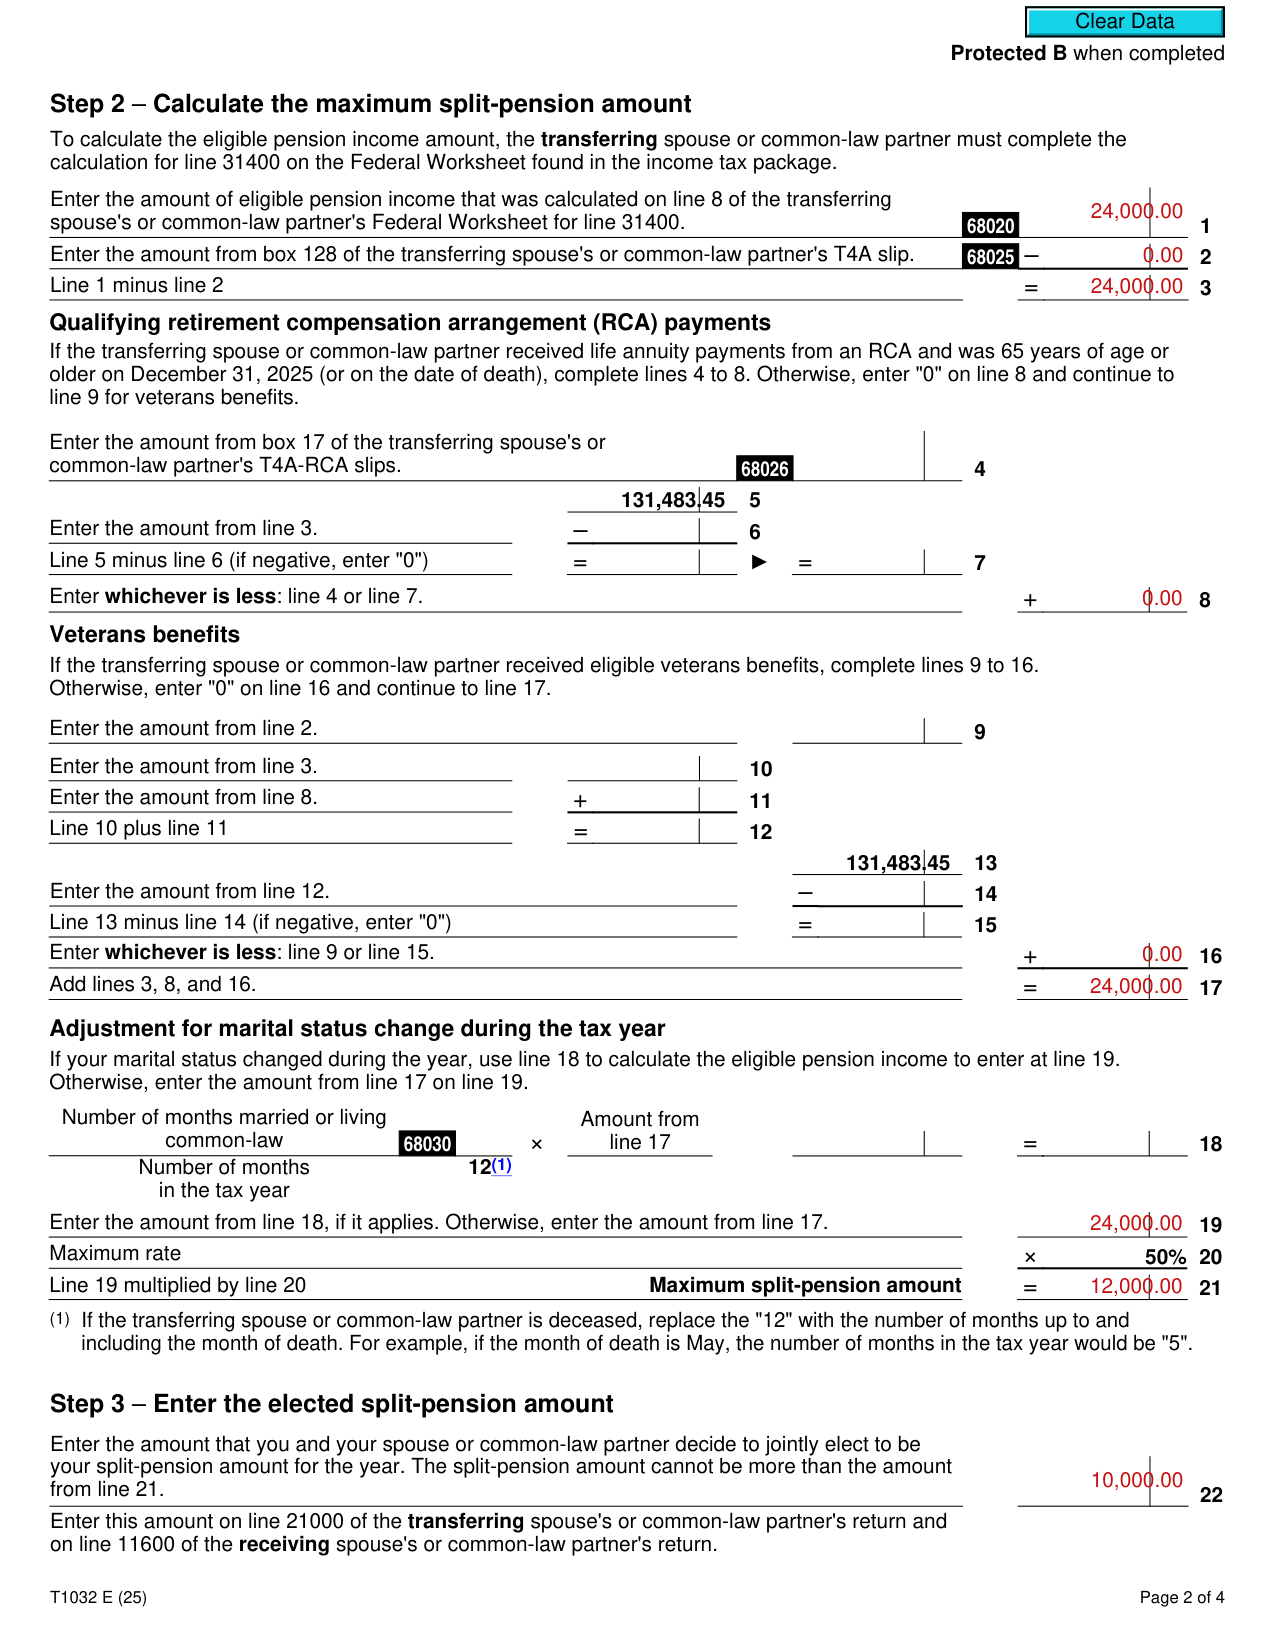
A filled-in Form T1032 example: spouses split a pension
How to fill out Form T1032, box by box
Step 1 - Identification
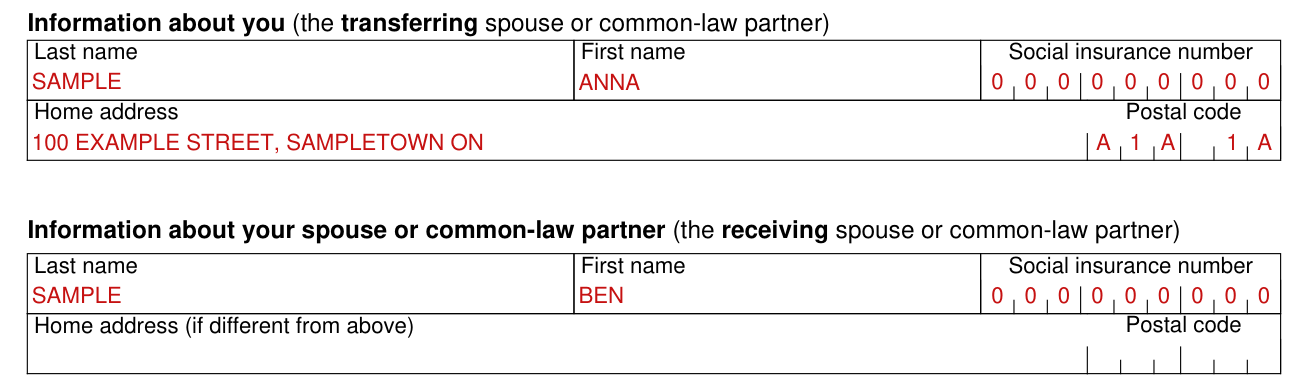
Under Step 1, Information about you (the transferring spouse or common-law partner), enter Last name, First name, Social insurance number, Home address and Postal code.
Under Information about your spouse or common-law partner (the receiving spouse or common-law partner), enter Last name, First name, Social insurance number, Home address (if different from the address in Information about you) and Postal code.
Step 2 - Calculate the maximum split-pension amount
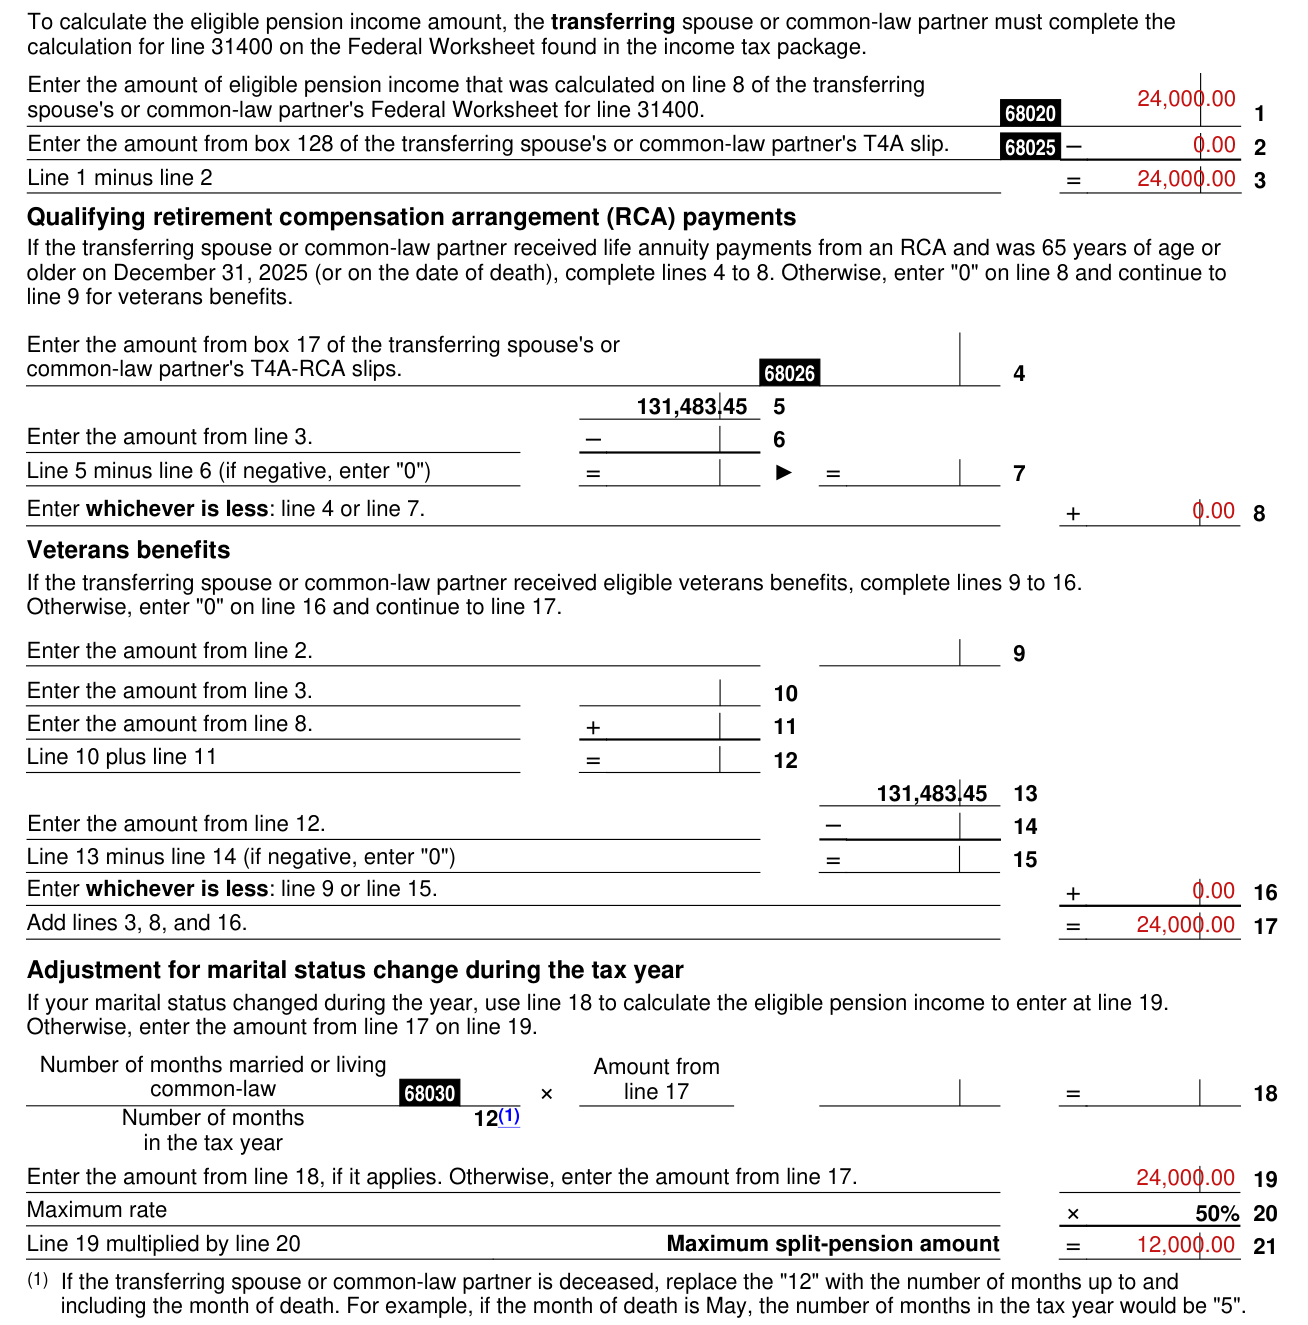
To calculate the eligible pension income amount, the transferring spouse or common-law partner must complete the calculation for line 31400 on the Federal Worksheet found in the income tax package.
Enter on line 1 the amount of eligible pension income that was calculated on line 8 of the transferring spouse's or common-law partner's Federal Worksheet for line 31400.
Enter on line 2 (68025) the amount from box 128 of the transferring spouse's or common-law partner's T4A slip.
Line 3 is line 1 minus line 2.
If the transferring spouse or common-law partner received life annuity payments from a retirement compensation arrangement (RCA) and was 65 years of age or older on December 31, 2025 (or on the date of death), complete lines 4 to 8. Otherwise, enter "0" on line 8 and continue to line 9 for veterans benefits.
If the transferring spouse or common-law partner received eligible veterans benefits, complete lines 9 to 16. Otherwise, enter "0" on line 16 and continue to line 17.
Add lines 3, 8, and 16 on line 17.
If your marital status changed during the year, use line 18 to calculate the eligible pension income to enter at line 19. Otherwise, enter the amount from line 17 on line 19.
Line 20 is the maximum rate, 50%. Line 21, the maximum split-pension amount, is line 19 multiplied by line 20.
Step 3 - Enter the elected split-pension amount
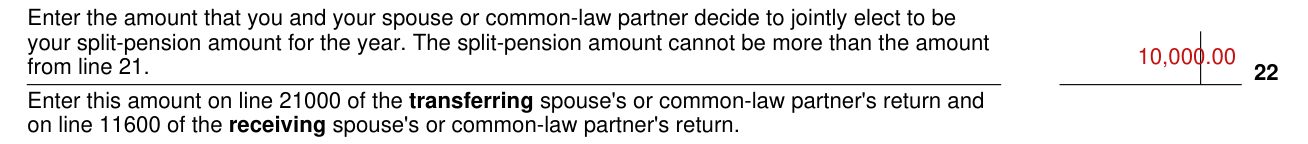
Enter the amount that you and your spouse or common-law partner decide to jointly elect to be your split-pension amount for the year. The split-pension amount cannot be more than the amount from line 21.
Enter this amount on line 21000 of the transferring spouse's or common-law partner's return and on line 11600 of the receiving spouse's or common-law partner's return.
Part A - Calculate the pension income amount of the transferring spouse or common-law partner
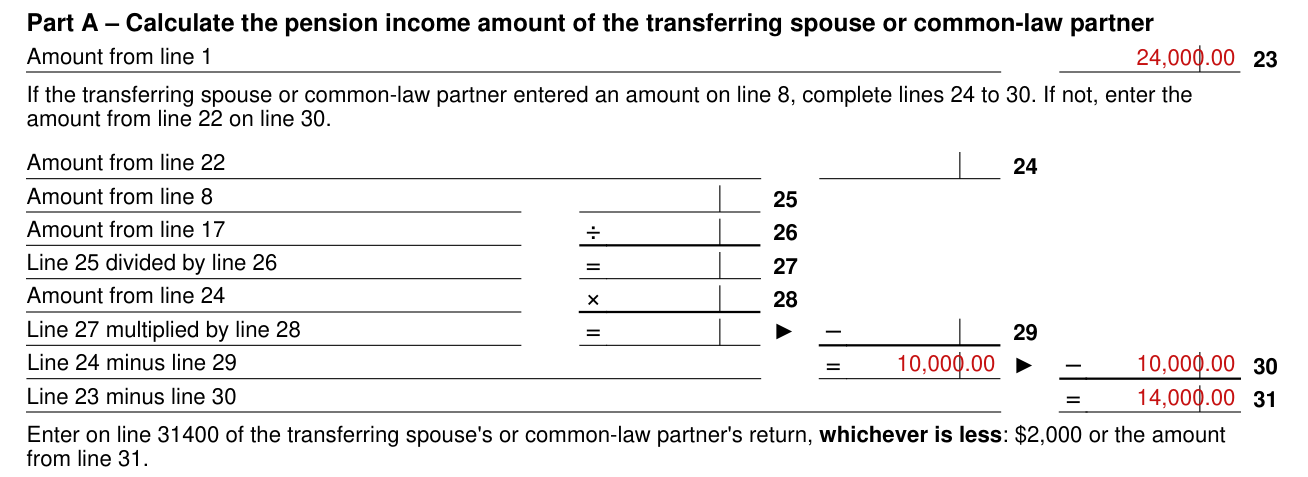
Enter on line 23 the amount from line 1.
If the transferring spouse or common-law partner entered an amount on line 8, complete lines 24 to 30. If not, enter the amount from line 22 on line 30.
Line 31 is line 23 minus line 30.
Enter on line 31400 of the transferring spouse's or common-law partner's return, whichever is less: $2,000 or the amount from line 31 (checked November 12, 2026).
Part B - Calculate the pension income amount of the receiving spouse or common-law partner
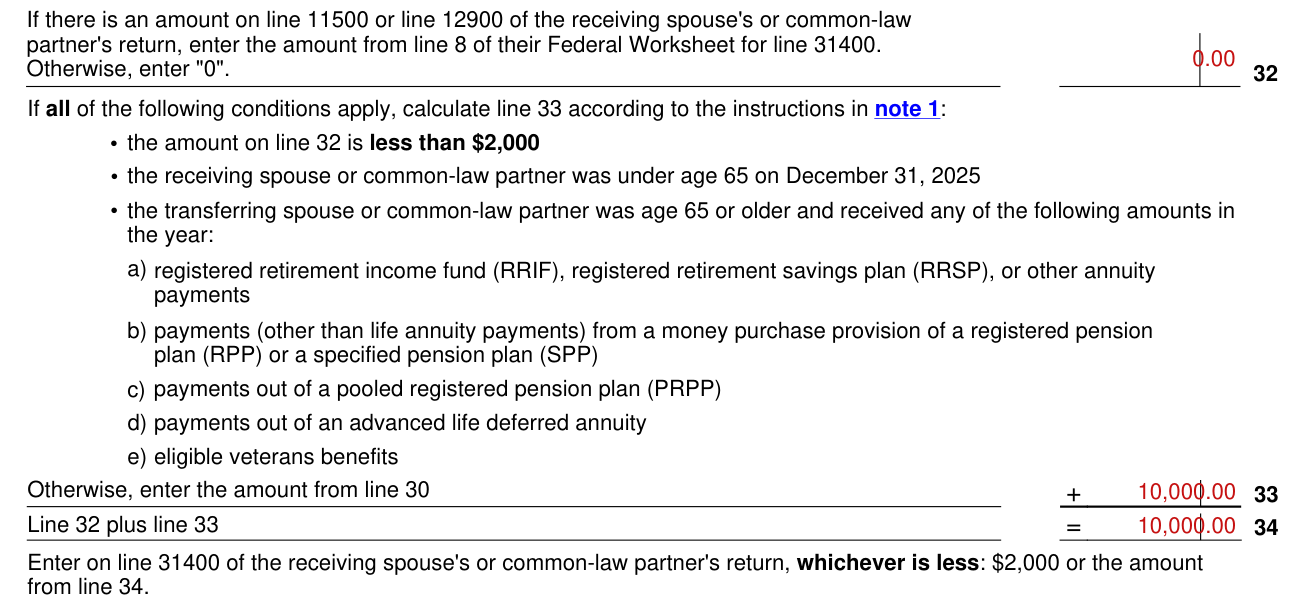
If there is an amount on line 11500 or line 12900 of the receiving spouse's or common-law partner's return, enter the amount from line 8 of their Federal Worksheet for line 31400. Otherwise, enter "0".
If all of the following conditions apply, calculate line 33 according to the instructions in note 1: the amount on line 32 is less than $2,000 (checked November 12, 2026); the receiving spouse or common-law partner was under age 65 on December 31, 2025; the transferring spouse or common-law partner was age 65 or older and received any of the following amounts in the year: a) registered retirement income fund (RRIF), registered retirement savings plan (RRSP), or other annuity payments; b) payments (other than life annuity payments) from a money purchase provision of a registered pension plan (RPP) or a specified pension plan (SPP); c) payments out of a pooled registered pension plan (PRPP); d) payments out of an advanced life deferred annuity; e) eligible veterans benefits.
Otherwise, enter the amount from line 30 on line 33.
Line 34 is line 32 plus line 33.
Enter on line 31400 of the receiving spouse's or common-law partner's return, whichever is less: $2,000 or the amount from line 34 (checked November 12, 2026).
Step 5 - Calculate the income tax deducted
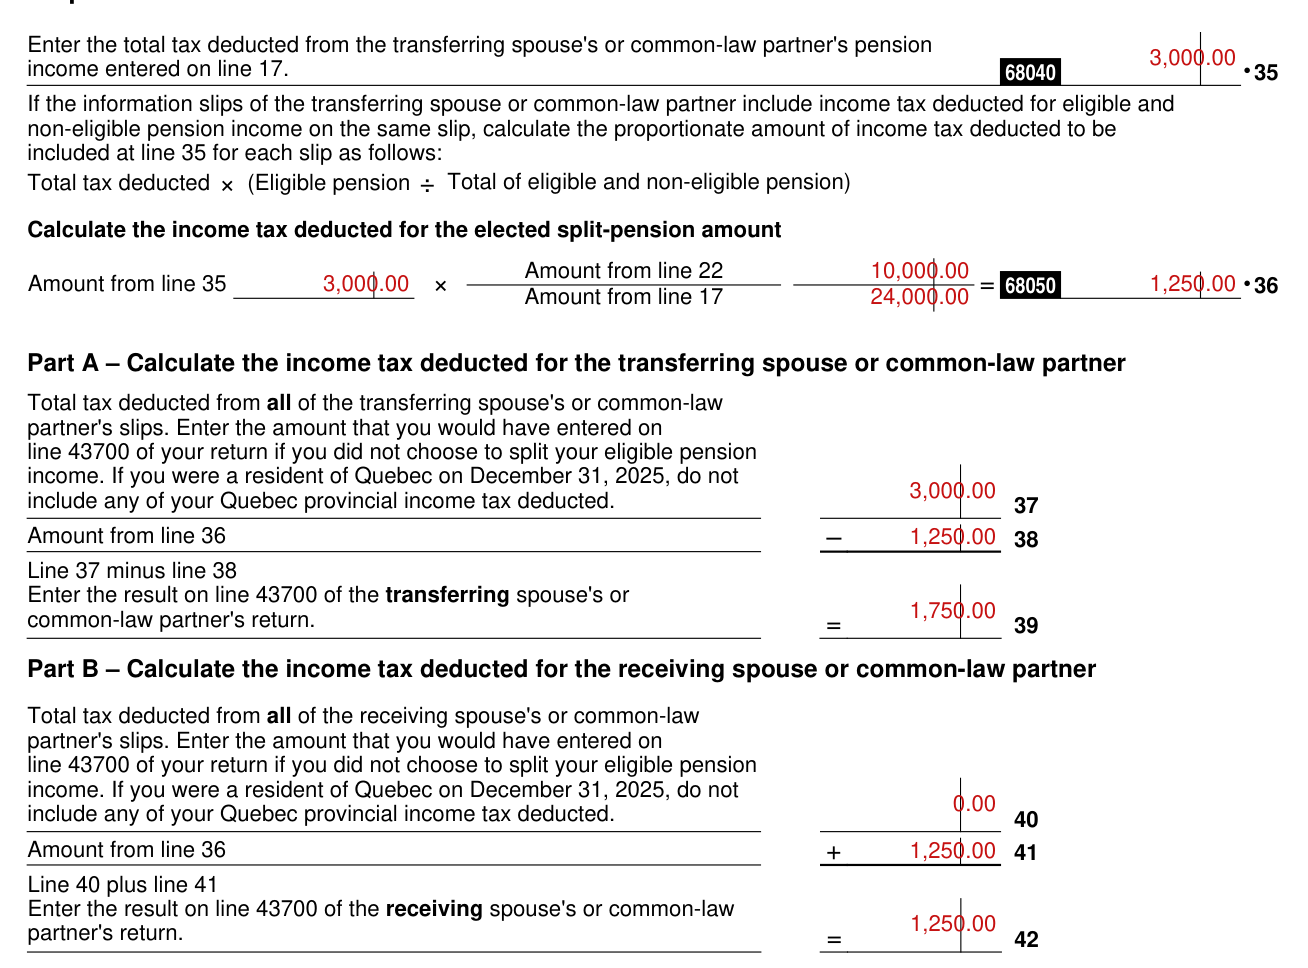
Enter on line 35 (68040) the total tax deducted from the transferring spouse's or common-law partner's pension income entered on line 17.
Calculate the income tax deducted for the elected split-pension amount on line 36 (68050) from the amount from line 35, the amount from line 22 and the amount from line 17.
On line 37, enter the total tax deducted from all of the transferring spouse's or common-law partner's slips: the amount that you would have entered on line 43700 of your return if you did not choose to split your eligible pension income.
Enter on line 38 the amount from line 36. Line 39 is line 37 minus line 38: enter the result on line 43700 of the transferring spouse's or common-law partner's return.
On line 40, enter the total tax deducted from all of the receiving spouse's or common-law partner's slips: the amount that you would have entered on line 43700 of your return if you did not choose to split your eligible pension income.
Enter on line 41 the amount from line 36. Line 42 is line 40 plus line 41: enter the result on line 43700 of the receiving spouse's or common-law partner's return.
If you were a resident of Quebec on December 31, 2025, do not include any of your Quebec provincial income tax deducted.
Step 6 - Complete the joint certification
By completing this form and signing it, you and your spouse or common-law partner jointly elect and certify that the split-pension amount entered on line 22 of Step 3 will be deducted in calculating the net income of the transferring spouse or common-law partner and reported as income by the receiving spouse or common-law partner on your income tax and benefit returns for 2025.
You will be jointly and severally liable for any amounts of tax, interest and penalties that may be owing as a result of this election.
It is a serious offence to make a false statement.
Signature of transferring spouse or common-law partner. Signature of receiving spouse or common-law partner.
Enter the Date.
Filing
Filing instructions
If you are filing electronically, keep this form in case the Canada Revenue Agency (CRA) asks to see it later. If you are filing a paper return, you must complete, sign, and attach copies of this form to both your return and your spouse's or common-law partner's return. The information on the forms must be the same. This form needs to be filed by your filing due date for the year. For more information on filing due dates, go to canada.ca/taxes-dates-individuals.
Sources
[1] Form T1032 (2025), Joint Election to Split Pension Income, Canada Revenue Agency (the Official source link on this page).