

Form N-289 at a glance
What it is: Form N-289 (REV. 2019) is the State of Hawaii Department of Taxation Certification for Exemption from the Withholding of Tax on the Disposition of Hawaii Real Property.
Who signs: Form N-289 must be signed by an individual, a responsible corporate officer, a member or general partner of a partnership, or a trustee, executor, or other fiduciary of a trust or estate.
Use Form N-289 to inform the transferee/buyer that the withholding of tax is not required upon the disposition of Hawaii real property if (1) the transferor/seller is a resident person, (2) by reason of a nonrecognition provision of the Internal Revenue Code as operative under chapter 235, HRS, or the provisions of any United States treaty, the transferor/seller is not required to recognize any gain or loss with respect to the transfer, or (3) for the year preceding the date of the transfer the property has been used by the transferor/seller as a principal residence, and that the amount realized for the property does not exceed $300,000. (checked November 3, 2026)
The transferor/seller can complete Form N-289.
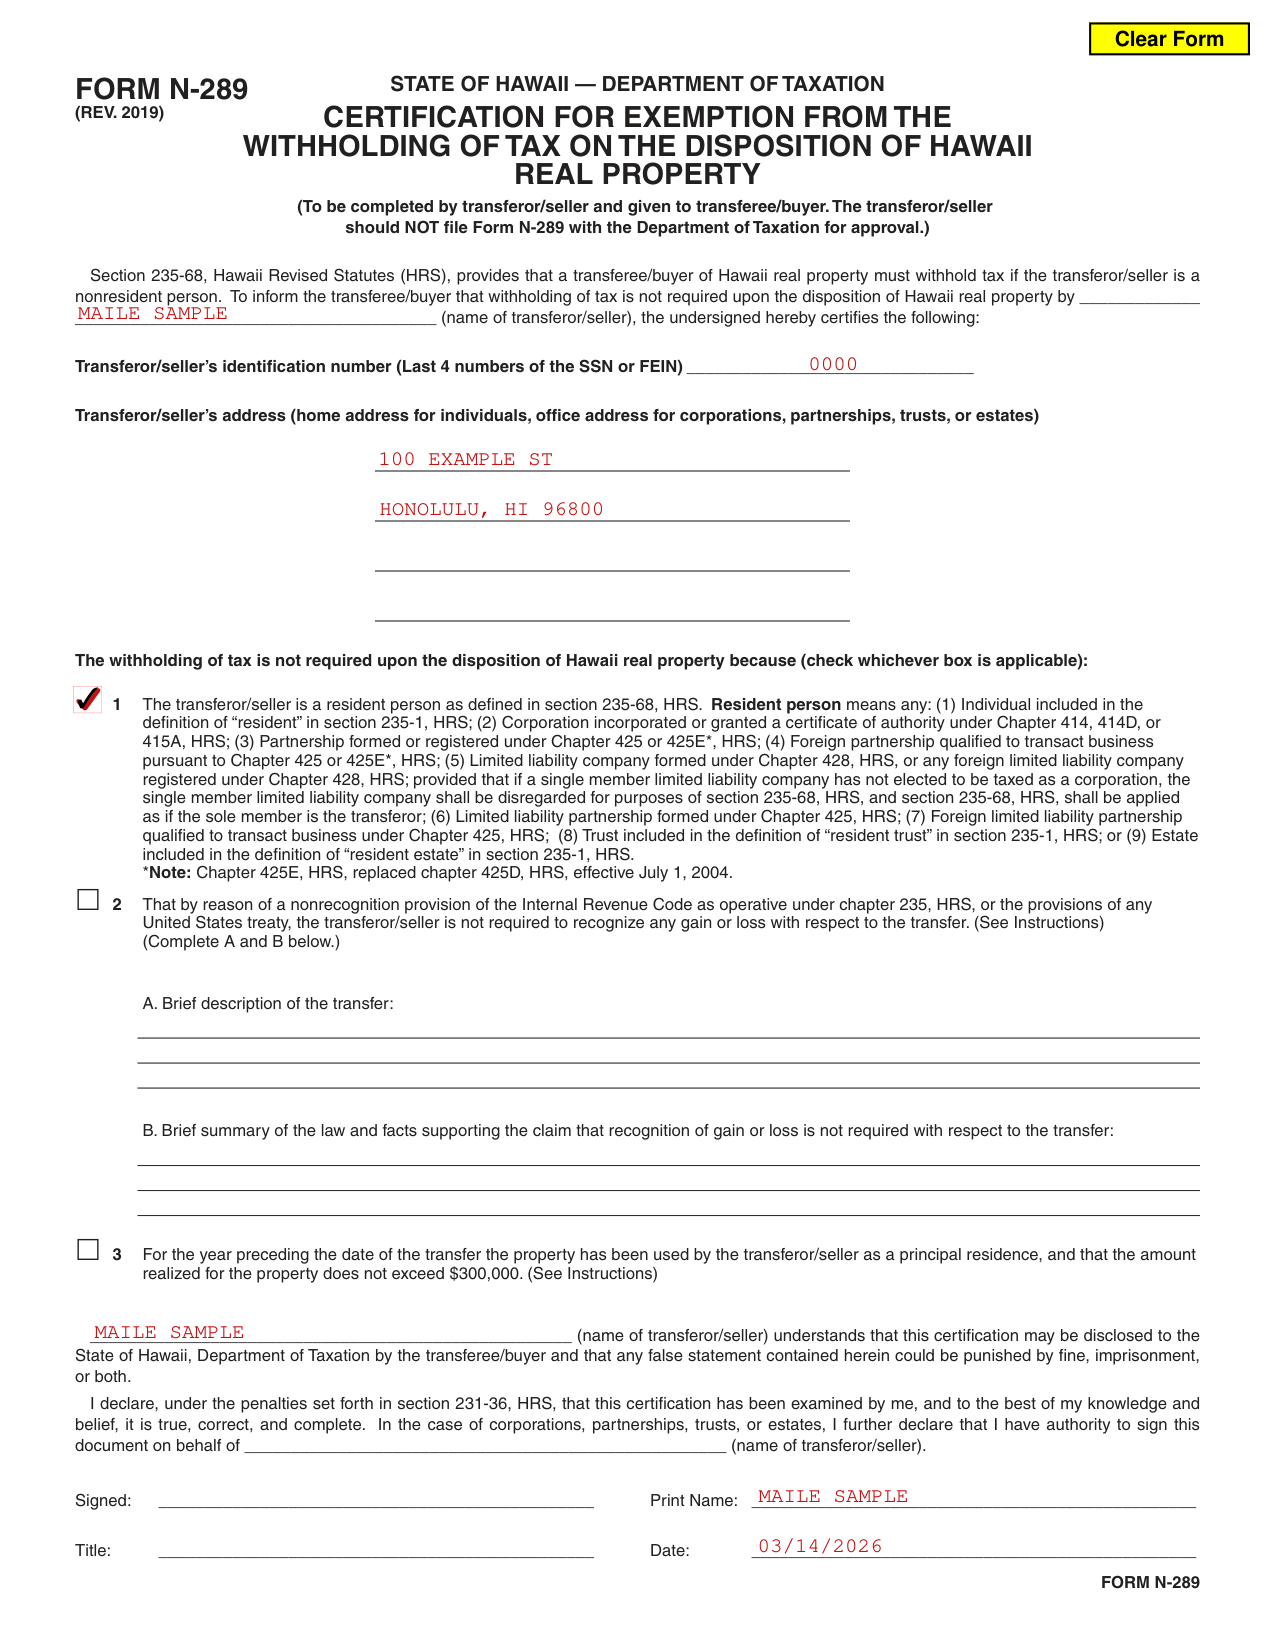
A filled-in Form N-289 example: a Hawaii resident gives the buyer Form N-289
How to fill out Form N-289, box by box
Transferor/seller's name, identification number and address
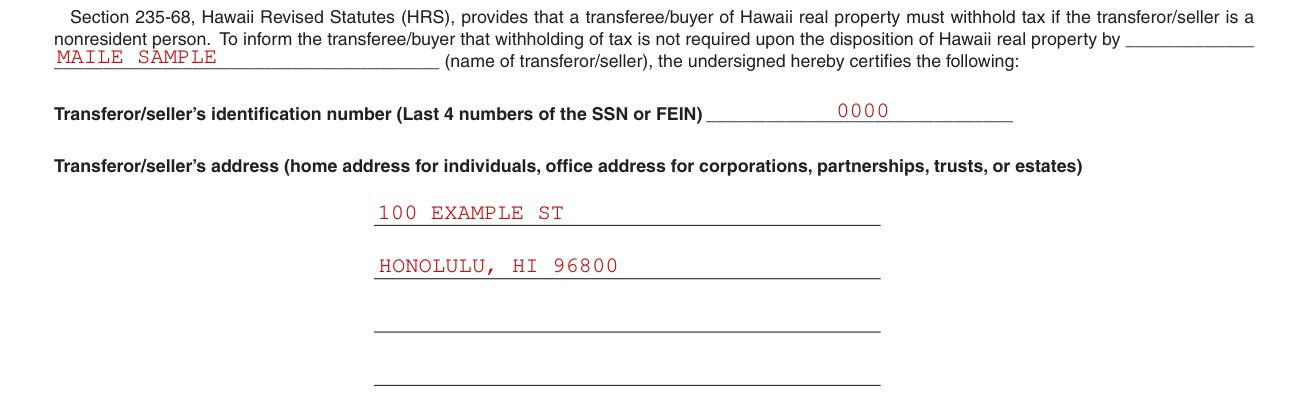
At the top of Form N-289, enter the transferor/seller's name, identification number (last 4 numbers of the social security number, individual identification number or federal I.D. number), and address.
Transferor/seller's address (home address for individuals, office address for corporations, partnerships, trusts, or estates).
The ITIN issued by the IRS must be used as the individual's identification number. If the individual has applied for an ITIN but the IRS has not yet issued the ITIN, write “Applied For.”
Check the applicable box
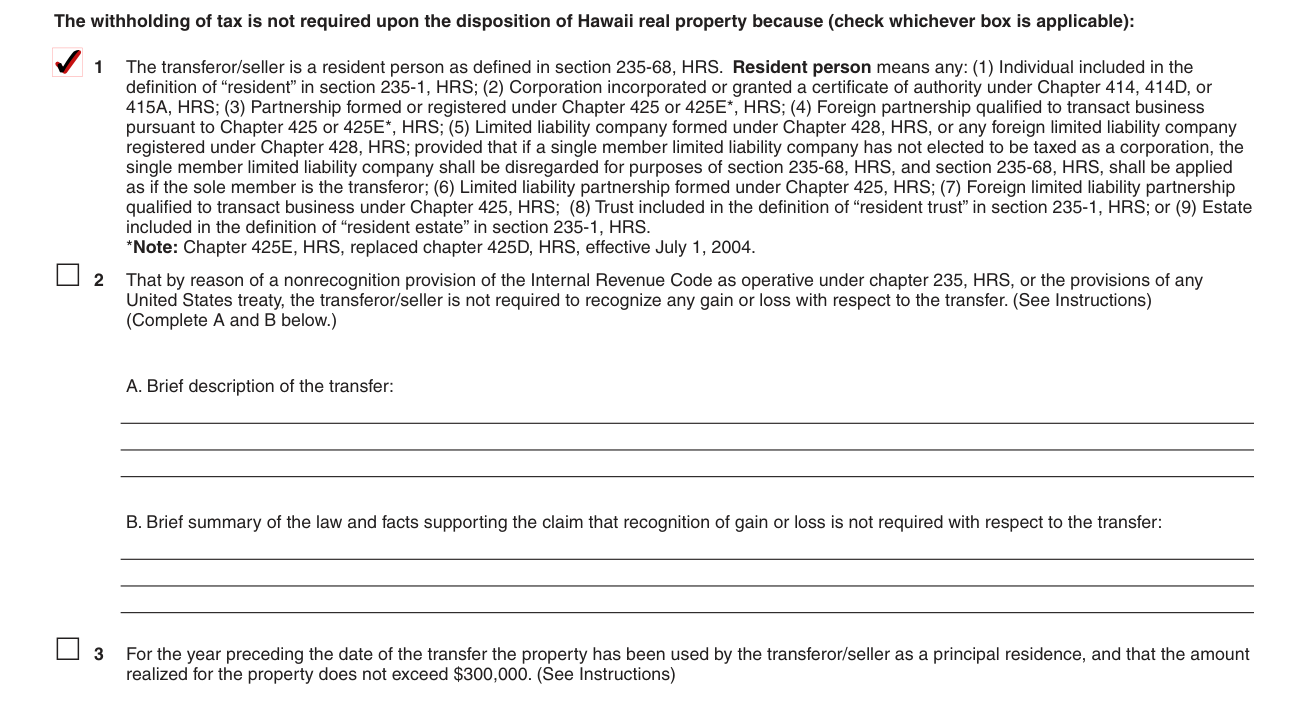
Check the applicable box to indicate the reason the withholding of tax is not required upon the disposition of Hawaii real property.
Check box number 1 if the transferor/seller is a resident person as defined in section 235-68, HRS.
Check box number 2 if by reason of a nonrecognition provision of the Internal Revenue Code as operative under chapter 235, HRS, or the provisions of any United States treaty, the transferor/seller is not required to recognize any gain or loss with respect to the transfer. Complete sections A and B requesting a brief description of the transfer and a brief summary of the law and facts supporting the claim that recognition of gain or loss is not required with respect to the transfer.
Check box number 3 if for the year preceding the date of the transfer the property has been used by the transferor/seller as a principal residence, and the amount realized for the property does not exceed $300,000. (checked November 3, 2026)
The “amount realized” means the sum of the cash paid, or to be paid (not including interest or original issue discount), the fair market value of other property transferred or to be transferred, and the amount of any liability assumed by the transferee/buyer or to which the Hawaii real property interest is subject to immediately before and after the transfer. Generally, the amount realized, for purposes of this withholding, is the sales or contract price.
Signed by an authorized agent and declaration
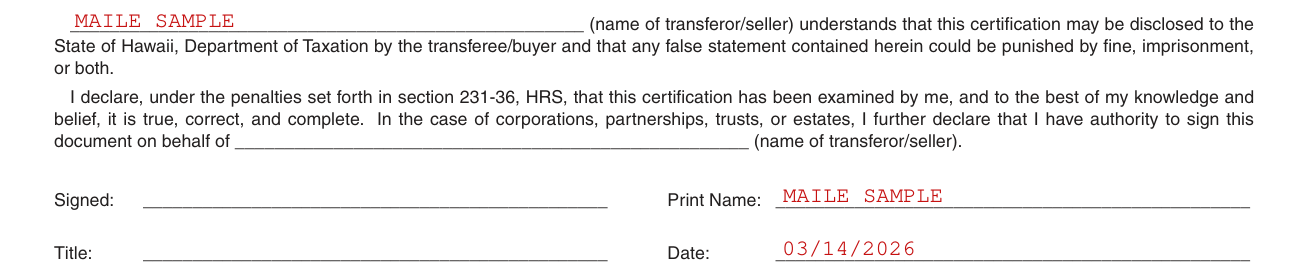
In addition, Form N-289 may be signed by an authorized agent with a power of attorney.
“I declare, under the penalties set forth in section 231-36, HRS, that this certification has been examined by me, and to the best of my knowledge and belief, it is true, correct, and complete. In the case of corporations, partnerships, trusts, or estates, I further declare that I have authority to sign this document on behalf of the transferor/seller.”
More rules for Form N-289
NOTE: Although the withholding of tax may not be required upon the disposition of Hawaii real property, the transferor/seller is required under section 235-92, HRS, to file an income tax return to report the sale or other disposition.
Form N-289 given to the transferee/buyer
The transferor/seller gives Form N-289 to the transferee/buyer
Form N-289 must be completed by the transferor/seller and given to the transferee/buyer. The transferor/seller should NOT file Form N-289 with the Department of Taxation for approval.
The transferee/buyer is to retain Form N-289 and NOT forward it to the Department of Taxation if ALL the transferor/sellers have provided a certification of exemption on Form N-289 to the transferee/buyer.
Not all of the transferor/sellers have provided Form N-289
If one or more, but not all of the transferor/sellers has provided a certification of exemption on Form N-289 to the transferee/buyer, the transferee/buyer shall attach a copy of the Form N-289 to Forms N-288 and N-288A, which must still be filed with the Department of Taxation.
Common questions about Form N-289
Is there a penalty?
The transferor/seller understands that this certification may be disclosed to the State of Hawaii, Department of Taxation by the transferee/buyer and that any false statement contained herein could be punished by fine, imprisonment, or both.
Sources
[1] Form N-289 (Rev. 2019), Certification for Exemption from the Withholding of Tax on the Disposition of Hawaii Real Property, State of Hawaii Department of Taxation (the Official source link on this page).