

HMDA/Data Collection Form at a glance
What it is: HMDA/Data Collection Form: this form must be fully completed by the loan officer and retained in the loan file.
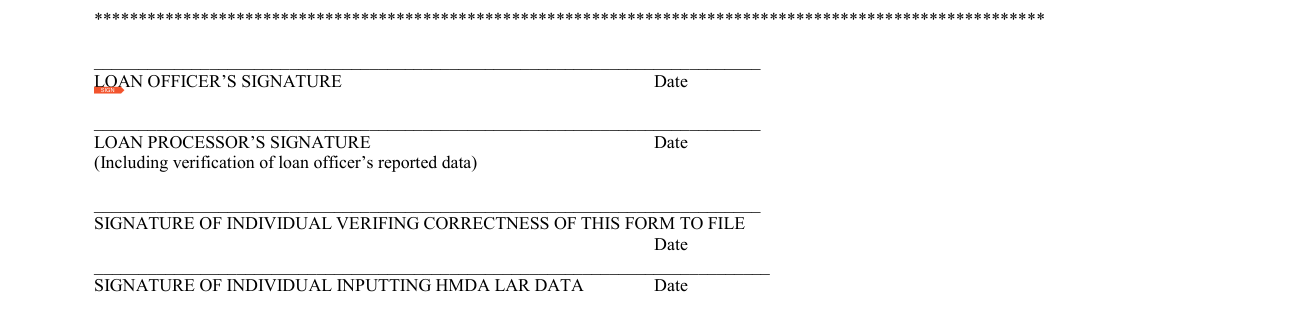
Who signs: LOAN OFFICER'S SIGNATURE Date LOAN PROCESSOR'S SIGNATURE Date SIGNATURE OF INDIVIDUAL VERIFING CORRECTNESS OF THIS FORM TO FILE Date SIGNATURE OF INDIVIDUAL INPUTTING HMDA LAR DATA Date.
A filled-in HMDA/Data Collection Form example: a loan officer completes page 1
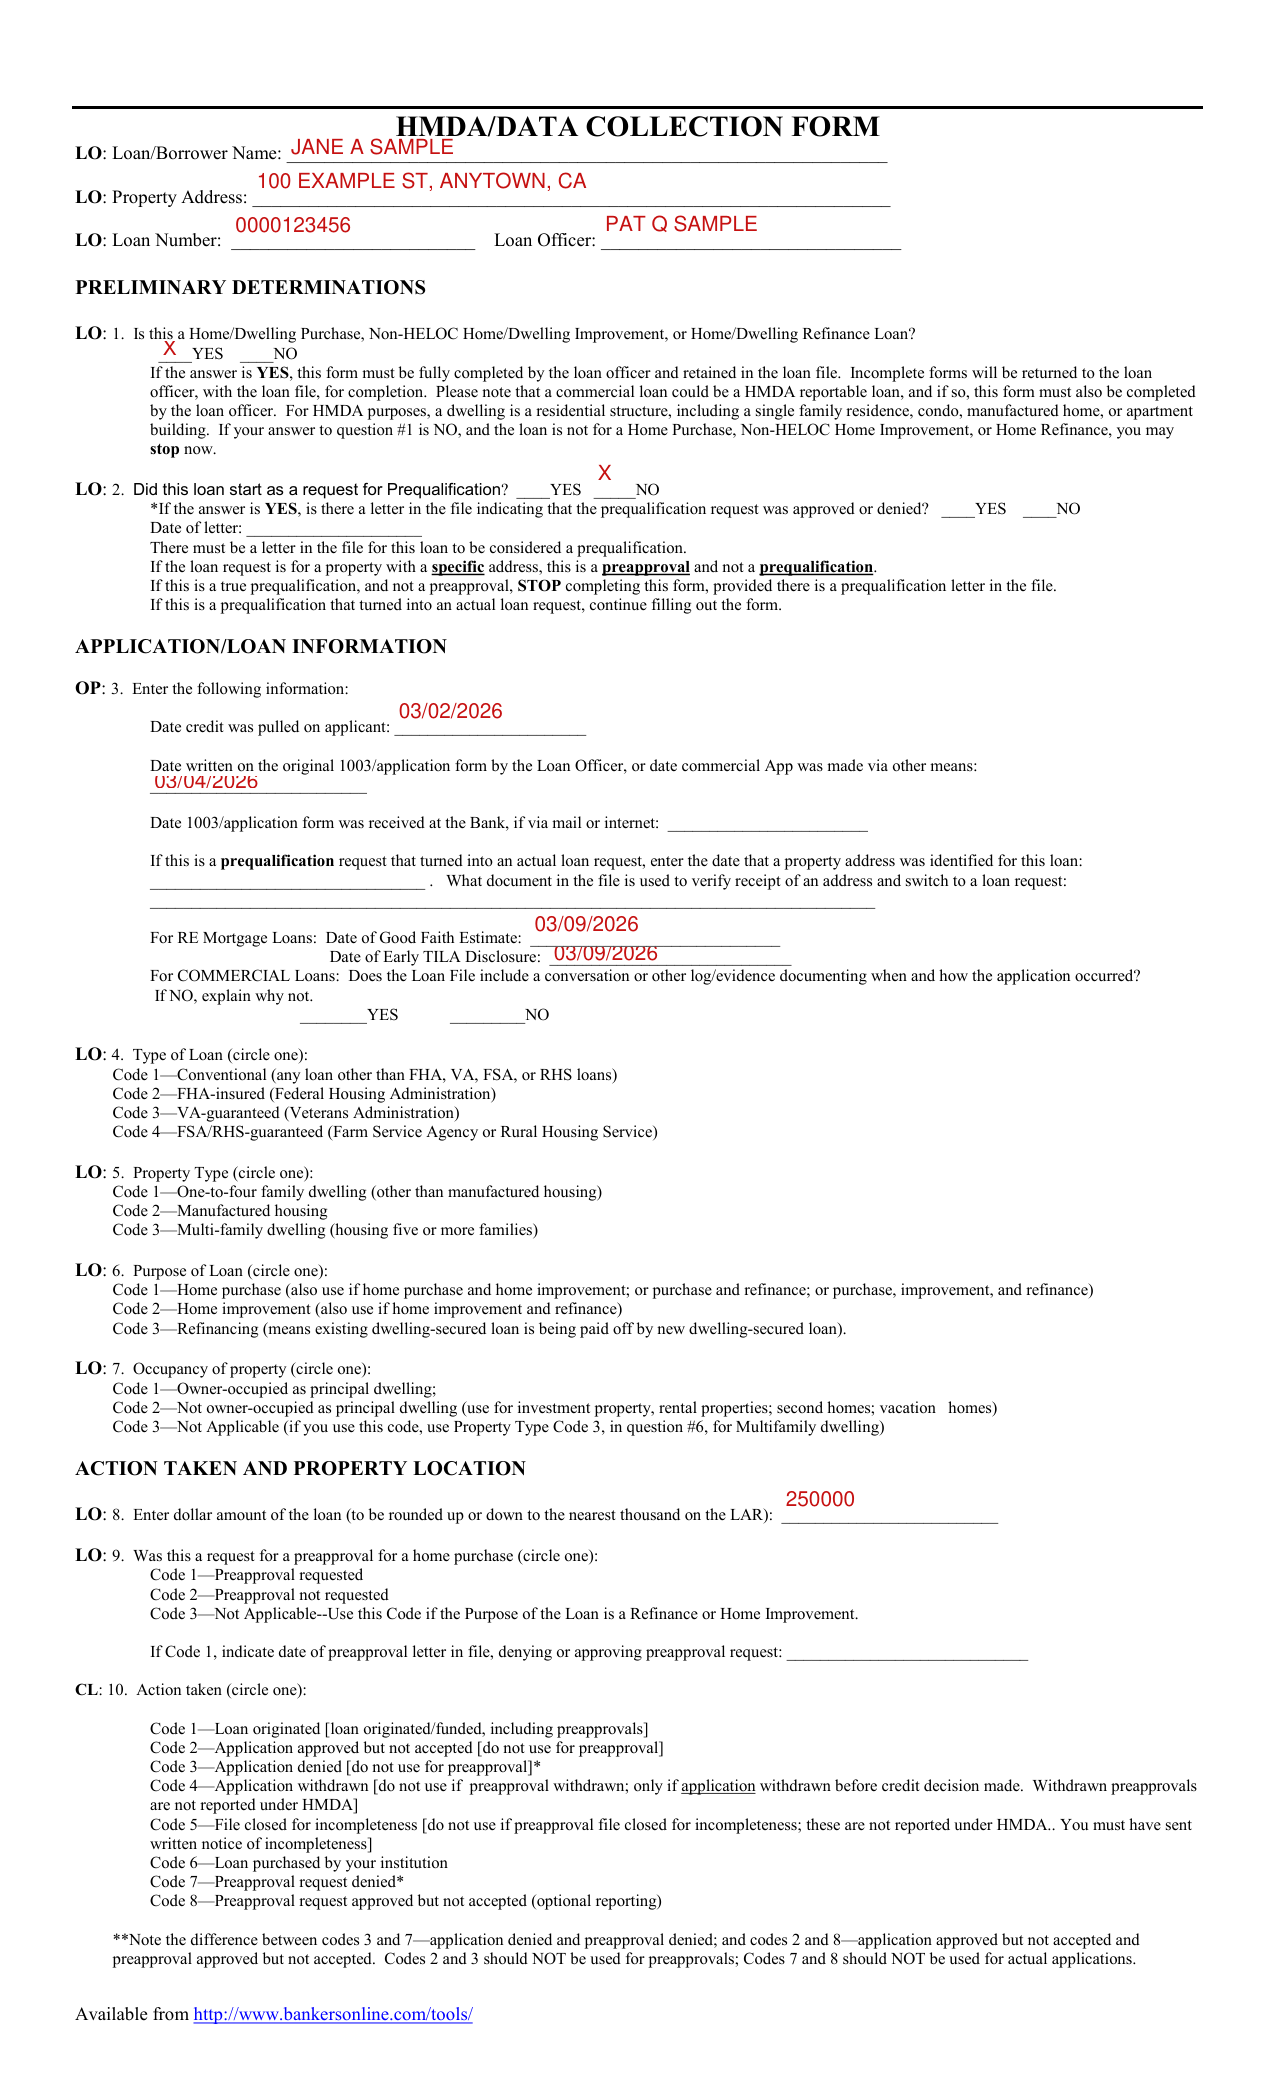
How to fill out HMDA/Data Collection Form, box by box
Loan, borrower, property and loan officer
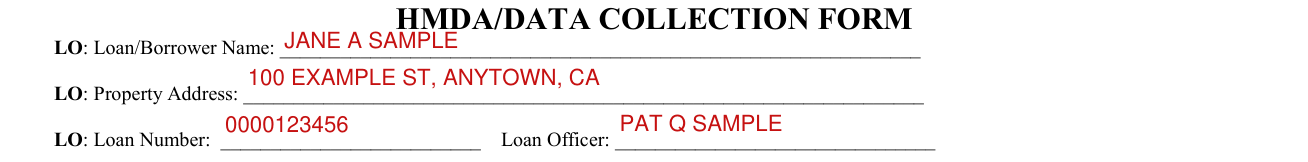
Enter the Loan/Borrower Name, the Property Address, the Loan Number and the Loan Officer.
Incomplete forms will be returned to the loan officer, with the loan file, for completion.
A commercial loan could be a HMDA reportable loan, and if so, this form must also be completed by the loan officer.
Preliminary determinations
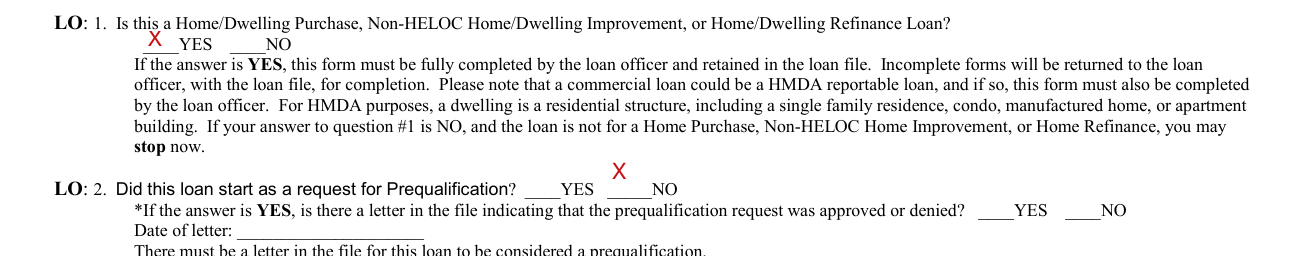
If the answer to question 1 is YES, this form must be fully completed by the loan officer and retained in the loan file.
Answer YES or NO to question 1: is this a Home/Dwelling Purchase, Non-HELOC Home/Dwelling Improvement, or Home/Dwelling Refinance Loan?
If your answer to question #1 is NO, and the loan is not for a Home Purchase, Non-HELOC Home Improvement, or Home Refinance, you may stop now.
For HMDA purposes, a dwelling is a residential structure, including a single family residence, condo, manufactured home, or apartment building.
Answer YES or NO to question 2: did this loan start as a request for Prequalification?
If the answer is YES, is there a letter in the file indicating that the prequalification request was approved or denied? Date of letter:
There must be a letter in the file for this loan to be considered a prequalification.
If the loan request is for a property with a specific address, this is a preapproval and not a prequalification.
If this is a true prequalification, and not a preapproval, STOP completing this form, provided there is a prequalification letter in the file.
If this is a prequalification that turned into an actual loan request, continue filling out the form.
Application and loan information
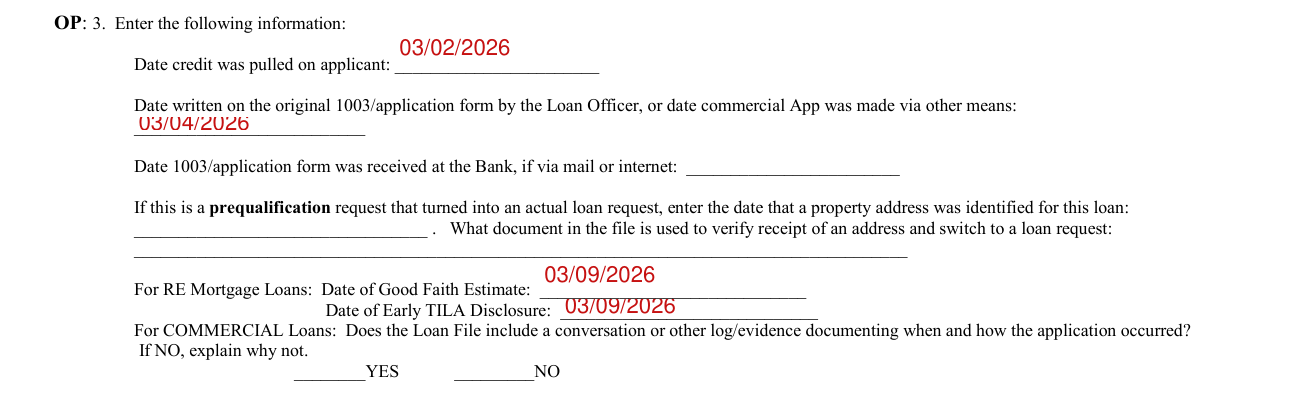
Enter the date credit was pulled on the applicant, the date written on the original 1003/application form by the Loan Officer, or the date a commercial App was made via other means, and the date the 1003/application form was received at the Bank, if via mail or internet.
If this is a prequalification request that turned into an actual loan request, enter the date that a property address was identified for this loan.
Enter what document in the file is used to verify receipt of an address and switch to a loan request.
For RE Mortgage Loans, enter the Date of Good Faith Estimate and the Date of Early TILA Disclosure.
For COMMERCIAL Loans: Does the Loan File include a conversation or other log/evidence documenting when and how the application occurred. If NO, explain why not.
For Type of Loan, circle one: Code 1-Conventional (any loan other than FHA, VA, FSA, or RHS loans), Code 2-FHA-insured, Code 3-VA-guaranteed or Code 4-FSA/RHS-guaranteed.
For Property Type, circle one: Code 1-One-to-four family dwelling (other than manufactured housing), Code 2-Manufactured housing or Code 3-Multi-family dwelling (housing five or more families).
For Purpose of Loan, circle one: Code 1-Home purchase (also use if home purchase and home improvement; or purchase and refinance; or purchase, improvement, and refinance), Code 2-Home improvement (also use if home improvement and refinance) or Code 3-Refinancing.
Refinancing means existing dwelling-secured loan is being paid off by new dwelling-secured loan.
For Occupancy of property, circle one: Code 1-Owner-occupied as principal dwelling, Code 2-Not owner-occupied as principal dwelling or Code 3-Not Applicable.
If you use Code 3-Not Applicable, use Property Type Code 3 for a Multifamily dwelling.
Loan amount and preapproval date
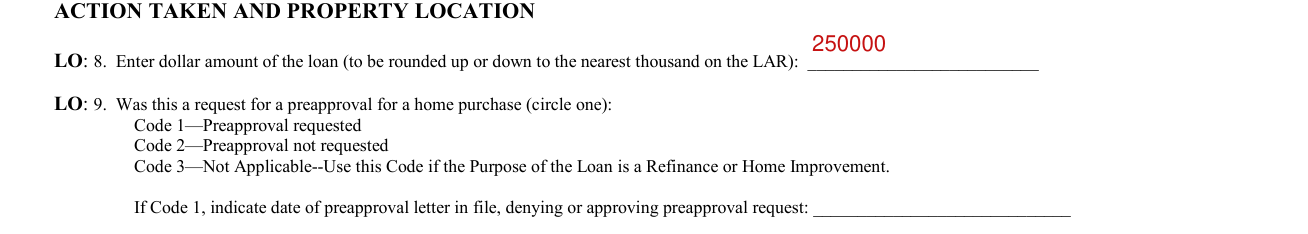
Enter the dollar amount of the loan, to be rounded up or down to the nearest thousand on the LAR.
For a home purchase preapproval, circle one: Code 1-Preapproval requested, Code 2-Preapproval not requested or Code 3-Not Applicable. Use Code 3 if the Purpose of the Loan is a Refinance or Home Improvement.
If Code 1, indicate date of preapproval letter in file, denying or approving preapproval request.
10. Action taken (circle one): Code 1-Loan originated [loan originated/funded, including preapprovals] Code 2-Application approved but not accepted [do not use for preapproval] Code 3-Application denied [do not use for preapproval] Code 4-Application withdrawn [do not use if preapproval withdrawn; only if application withdrawn before credit decision made. Withdrawn preapprovals are not reported under HMDA] Code 5-File closed for incompleteness [do not use if preapproval file closed for incompleteness; these are not reported under HMDA. You must have sent written notice of incompleteness] Code 6-Loan purchased by your institution Code 7-Preapproval request denied Code 8-Preapproval request approved but not accepted (optional reporting)
Codes 2 and 3 should NOT be used for preapprovals; Codes 7 and 8 should NOT be used for actual applications.
Action taken and property location
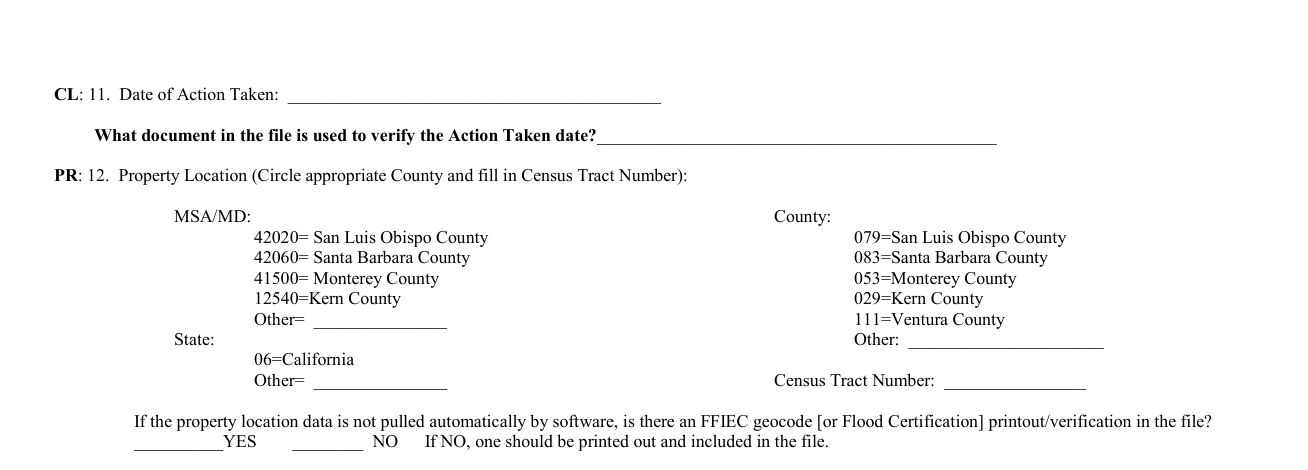
11. Date of Action Taken: What document in the file is used to verify the Action Taken date? 12. Property Location (Circle appropriate County and fill in Census Tract Number): MSA/MD: 42020= San Luis Obispo County 42060= Santa Barbara County 41500= Monterey County 12540=Kern County Other= State: 06=California Other= County: 079=San Luis Obispo County 083=Santa Barbara County 053=Monterey County 029=Kern County 111=Ventura County Other: Census Tract Number:
If the property location data is not pulled automatically by software, is there an FFIEC geocode [or Flood Certification] printout/verification in the file? If NO, one should be printed out and included in the file.
Government monitoring information
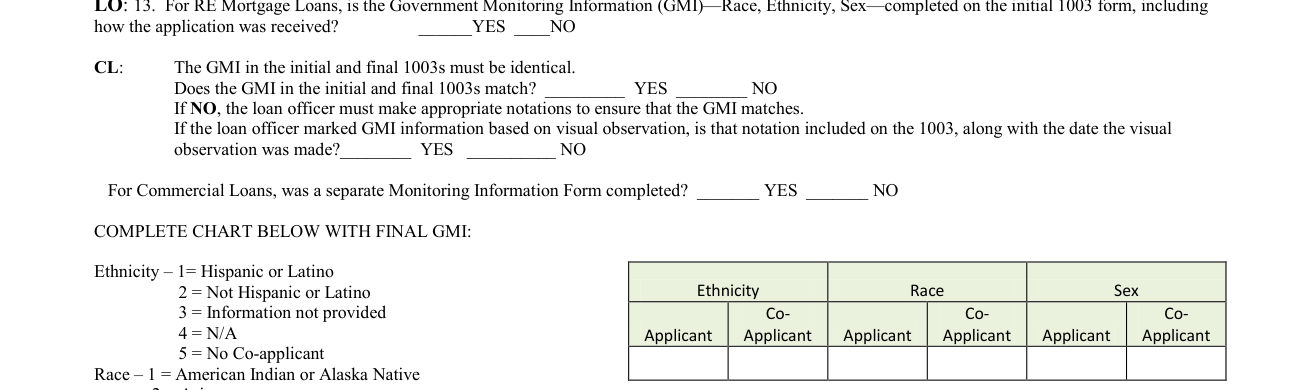
For RE Mortgage Loans, is the Government Monitoring Information (GMI)-Race, Ethnicity, Sex-completed on the initial 1003 form, including how the application was received?
The GMI in the initial and final 1003s must be identical.
If the GMI in the initial and final 1003s does not match, the loan officer must make appropriate notations to ensure that the GMI matches.
If the loan officer marked GMI information based on visual observation, is that notation included on the 1003, along with the date the visual observation was made? YES NO For Commercial Loans, was a separate Monitoring Information Form completed? YES NO Complete chart with final GMI: Ethnicity - 1= Hispanic or Latino 2 = Not Hispanic or Latino 3 = Information not provided 4 = N/A 5 = No Co-applicant. Race - 1 = American Indian or Alaska Native 2 = Asian 3= African American 4 = Native Hawaiian or Pacific Islander 5 = White 6 = Information not Provided 7 = N/A 8 = No Co-applicant. Sex - 1 = Male 2 = Female 3 = Information Not Provided 4 = N/A 5 = No Co-applicant. 14.
Income, purchaser and rate
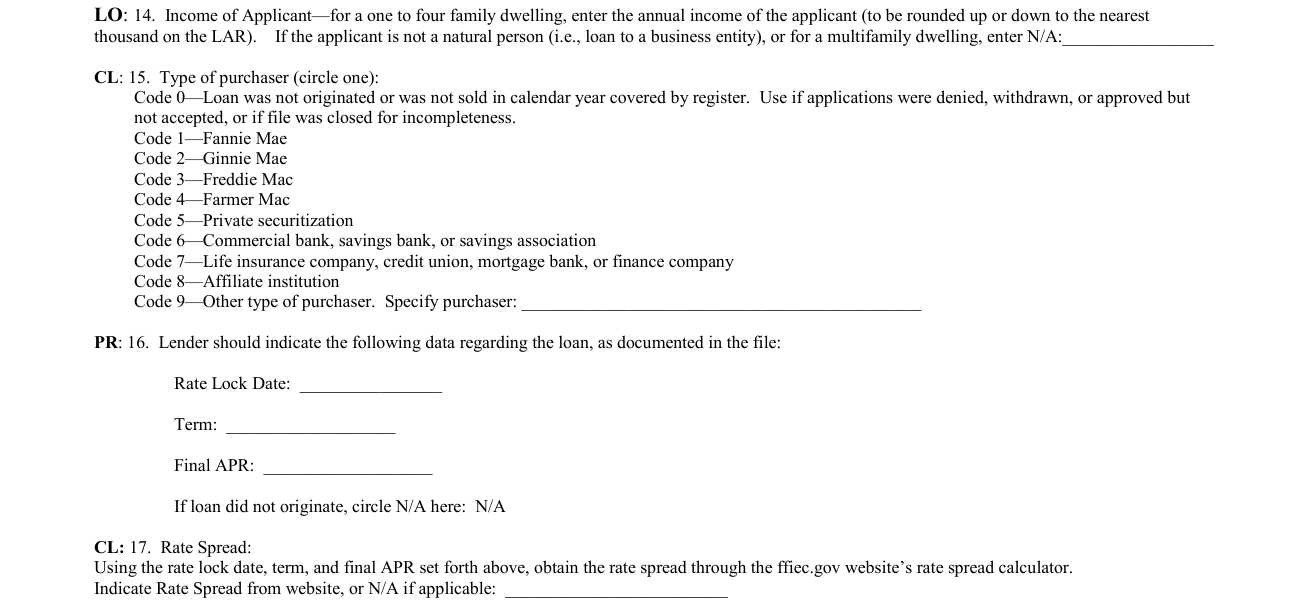
Income of Applicant-for a one to four family dwelling, enter the annual income of the applicant (to be rounded up or down to the nearest thousand on the LAR). If the applicant is not a natural person (i.e., loan to a business entity), or for a multifamily dwelling, enter N/A. 15.
Type of purchaser (circle one): Code 0-Loan was not originated or was not sold in calendar year covered by register. Use if applications were denied, withdrawn, or approved but not accepted, or if file was closed for incompleteness.
Code 1-Fannie Mae Code 2-Ginnie Mae Code 3-Freddie Mac Code 4-Farmer Mac Code 5-Private securitization Code 6-Commercial bank, savings bank, or savings association Code 7-Life insurance company, credit union, mortgage bank, or finance company Code 8-Affiliate institution Code 9-Other type of purchaser. Specify purchaser. 16.
Lender should indicate the following data regarding the loan, as documented in the file: Rate Lock Date, Term and Final APR. If loan did not originate, circle N/A here. 17.
Using the rate lock date, term, and final APR, obtain the rate spread through the ffiec.gov website's rate spread calculator.
Indicate Rate Spread from website, or N/A if applicable.
Lien status and signatures
For Lien Status, circle one. Also, for loans that do not originate, circle the code that would have been appropriate.
LOAN OFFICER'S SIGNATURE Date LOAN PROCESSOR'S SIGNATURE Date (Including verification of loan officer's reported data) SIGNATURE OF INDIVIDUAL VERIFING CORRECTNESS OF THIS FORM TO FILE Date SIGNATURE OF INDIVIDUAL INPUTTING HMDA LAR DATA Date
After verification of Loan Officer Data, information should be input into the HMDA LAR, and this form should be retained in the Loan File for future compliance oversight reviews and FDIC examination and external audit purposes.
Sources
[1] HMDA/Data Collection Form, bankersonline.com tools (the Official source link on this page).
