
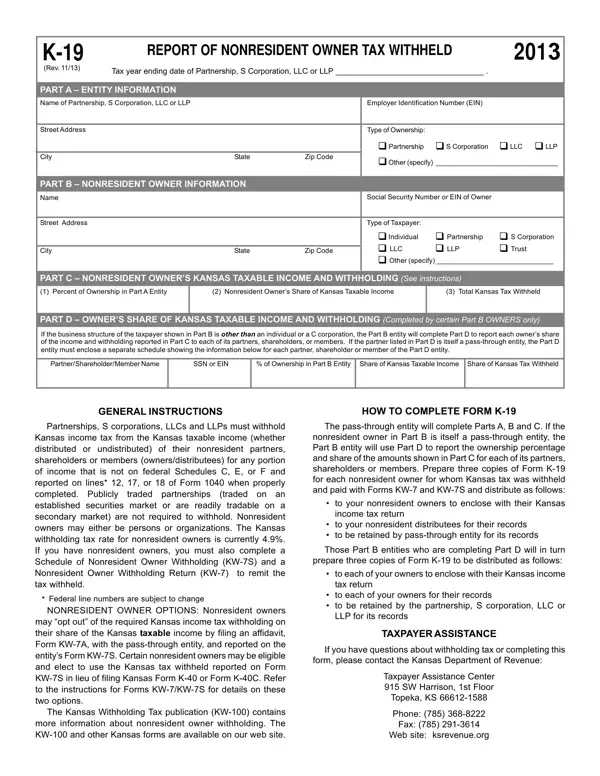

Form K-19 at a glance
What it is: Report of Nonresident Owner Tax Withheld, Form K-19.
A filled-in Form K-19 example: a partnership reports one individual owner
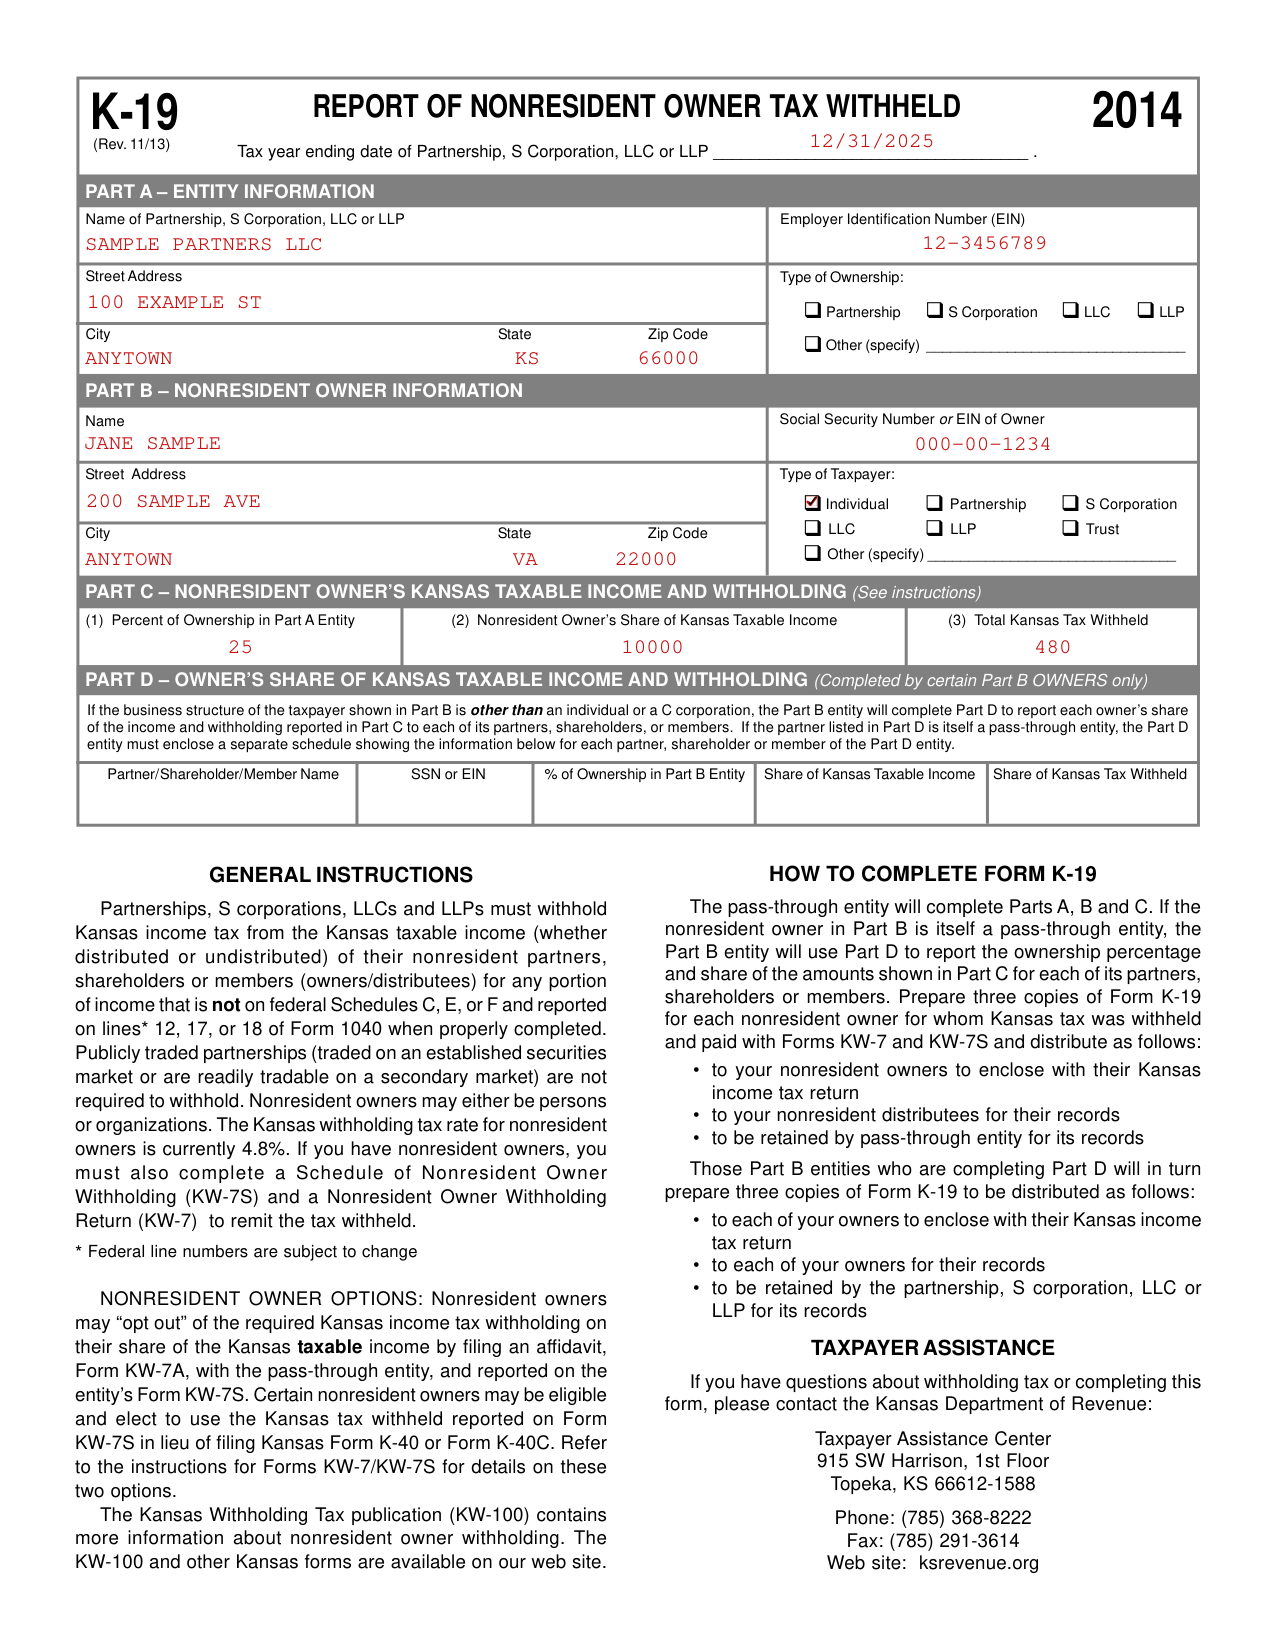
How to fill out Form K-19, box by box
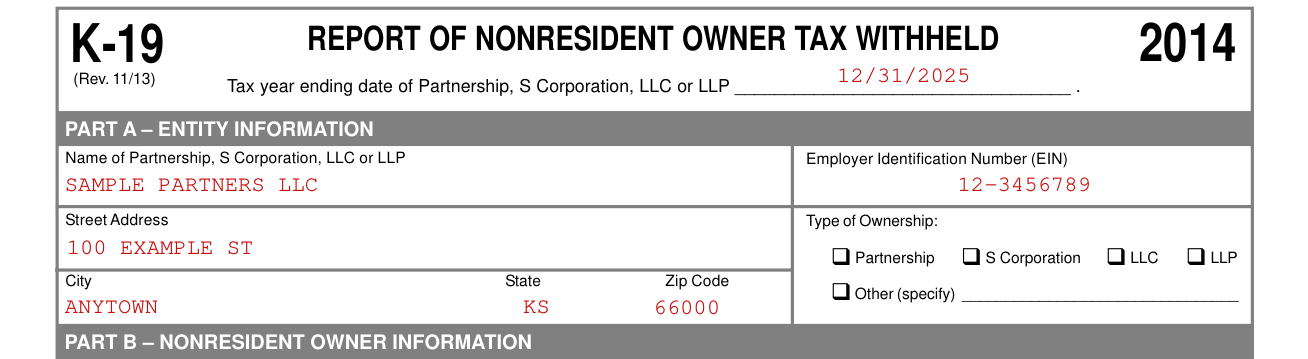
Part A: entity information
Partnerships, S corporations, LLCs and LLPs must withhold Kansas income tax from the Kansas taxable income (whether distributed or undistributed) of their nonresident partners, shareholders or members (owners/distributees) for any portion of income that is not on federal Schedules C, E, orF and reported on lines* 12, 17, or 18 of Form 1040 when properly completed. Publicly traded partnerships (traded on an established securities market or are readily tradable on a secondary market) are not required to withhold. Nonresident owners may either be persons or organizations. The Kansas withholding tax rate for nonresident owners is currently 4.8%. If you have nonresident owners, you must also complete a Schedule of Nonresident Owner Withholding (KW-7S) and a Nonresident Owner Withholding Return (KW-7) to remit the tax withheld.
Enter the Tax year ending date of Partnership, S Corporation, LLC or LLP.
In Part A, enter the Name of Partnership, S Corporation, LLC or LLP, the Employer Identification Number (EIN), the Street Address, the City, State and Zip Code, and the Type of Ownership: Partnership, S Corporation, LLC, LLP or Other (specify).
Part B: nonresident owner information
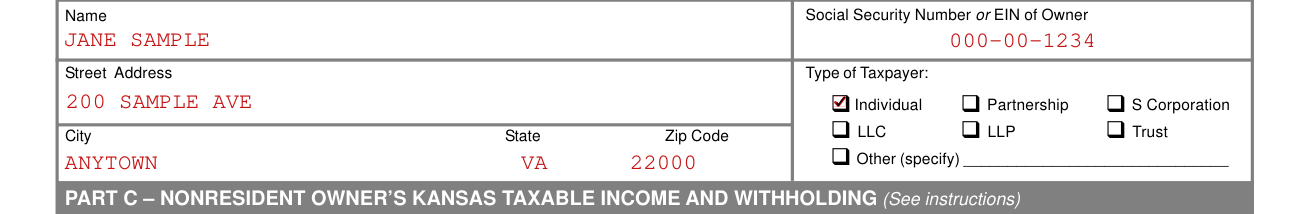
In Part B, enter the Name of the nonresident owner, the nonresident Street Address, the City of nonresident, the State of nonresident, the Zip Code of nonresident, the Social Security Number or EIN of Owner and the Type of Taxpayer: Individual, Partnership, S Corporation, LLC, LLP, Trust or Other (specify).
Part C: nonresident owner's Kansas taxable income and withholding

In Part C, enter (1) Percent of Ownership in Part A Entity, (2) Nonresident Owner's Share of Kansas Taxable Income and (3) Total Kansas Tax Withheld.
Part D: owner's share of Kansas taxable income and withholding
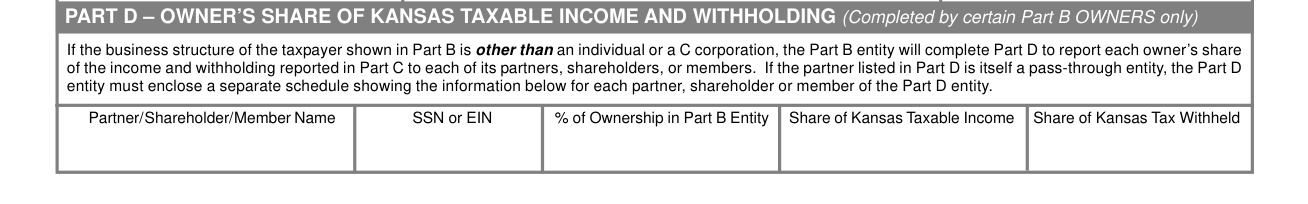
If the business structure of the taxpayer shown in Part Bis other than an individual or aCcorporation, the Part B entity will complete Part D to report each owner's share of the income and withholding reported in Part C to each of its partners, shareholders, or members. If the partner listed in Part Dis itself a pass-through entity, the Part D entity must enclose a separate schedule showing the information in Part D for each partner, shareholder or member of the Part D entity.
In Part D, enter the Partner/Shareholder/Member Name, the SSN or EIN, the % of Ownership in Part B Entity, the Share of Kansas Taxable Income and the Share of Kansas Tax Withheld.
More rules for Form K-19
The pass-through entity will complete Parts A, B and C. If the nonresident owner in Part B is itself a pass-through entity, the Part B entity will use Part D to report the ownership percentage and share of the amounts shown in Part C for each of its partners, shareholders or members. Prepare three copies of Form K-19 for each nonresident owner for whom Kansas tax was withheld and paid with Forms KW-7 and KW-7S and distribute as follows: to your nonresident owners to enclose with their Kansas income tax return; to your nonresident distributees for their records; to be retained by pass-through entity for its records.
Those Part B entities who are completing Part D will in turn prepare three copies of Form K-19 to be distributed as follows: to each of your owners to enclose with their Kansas income tax return; to each of your owners for their records; to be retained by the partnership, S corporation, LLC or LLP for its records.
NONRESIDENT OWNER OPTIONS: Nonresident owners may “opt out” of the required Kansas income tax withholding on their share of the Kansas taxable income by filing an affidavit, Form KW-7A, with the pass-through entity, and reported on the entity's Form KW-7S. Certain nonresident owners may be eligible and elect to use the Kansas tax withheld reported on Form KW-7S in lieu of filing Kansas Form K-40 or Form K-40C. Refer to the instructions for Forms KW-7/KW-7S for details on these two options.
The Kansas Withholding Tax publication (KW-100) contains more information about nonresident owner withholding.
If you have questions about withholding tax or completing this form, please contact the Kansas Department of Revenue: Taxpayer Assistance Center 915 SW Harrison, 1st Floor Topeka, KS 66612-1588, Phone: (785) 368-8222.
Sources
[1] Form K-19 (Rev. 11/13), Report of Nonresident Owner Tax Withheld, Kansas Department of Revenue (the Official source link on this page).