
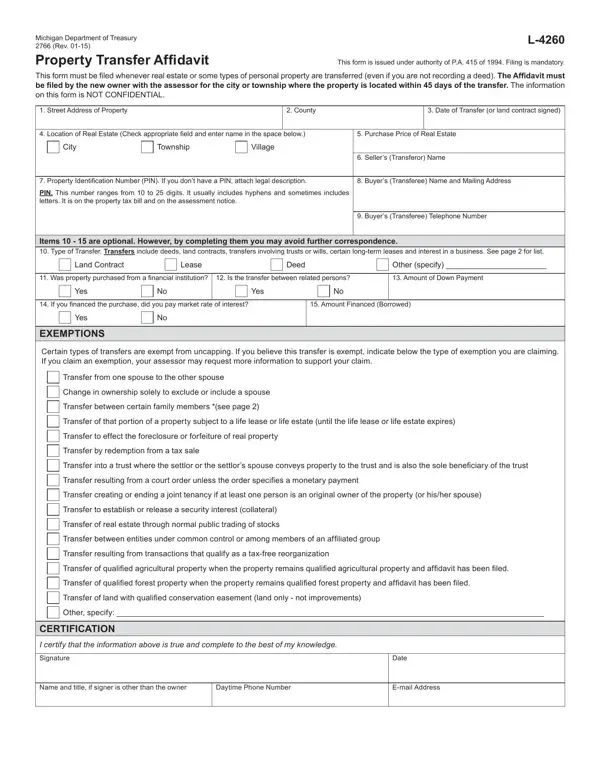

Form 2766 at a glance
What it is: Form 2766 (Rev. 03-25), L-4260, is the Michigan Department of Treasury Property Transfer Affidavit, issued under P.A. 415 of 1994, and filing is mandatory.
Where and when to file: The new owner must file the completed Affidavit with the assessor for the city or township where the property is located within 45 days of the transfer, whenever real estate or some types of personal property are transferred, even if you are not recording a deed. The information on this form is not confidential.
A filled-in Form 2766 example: a buyer files after a house purchase
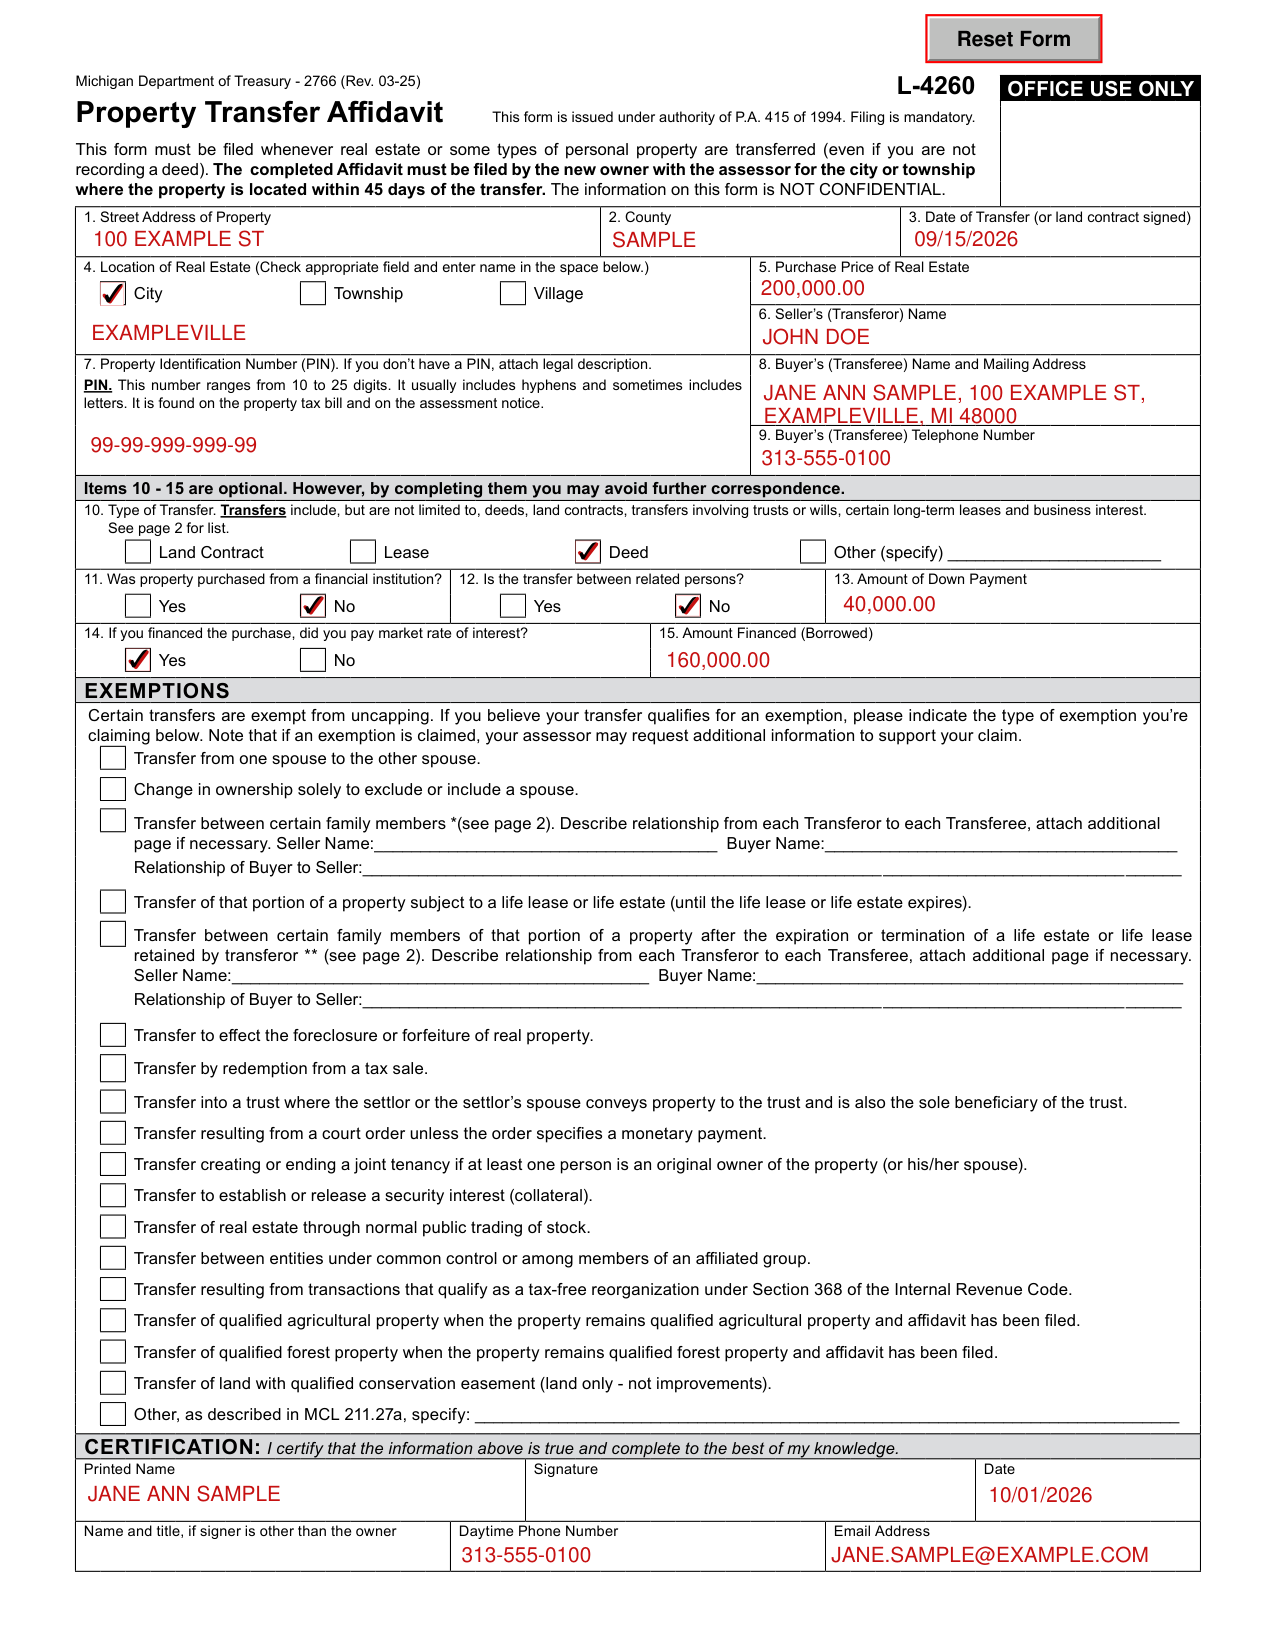
How to fill out Form 2766, box by box
Street Address of Property, County and Date of Transfer
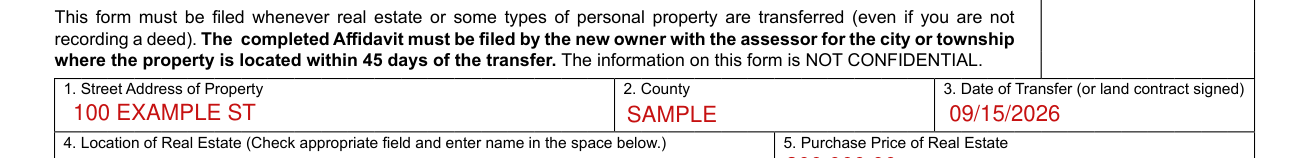
Enter the Street Address of Property, the County and the Date of Transfer (or land contract signed).
Location of Real Estate
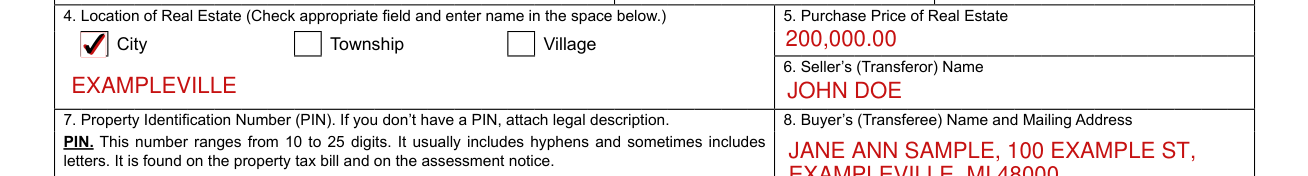
Check City, Township or Village and enter the name in the location of real estate field.
Purchase Price of Real Estate and Seller's (Transferor) Name
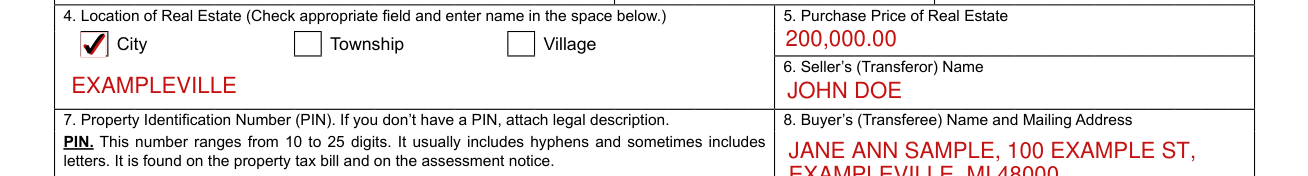
Enter the Purchase Price of Real Estate.
Enter the Seller's (Transferor) Name.
Property Identification Number (PIN)
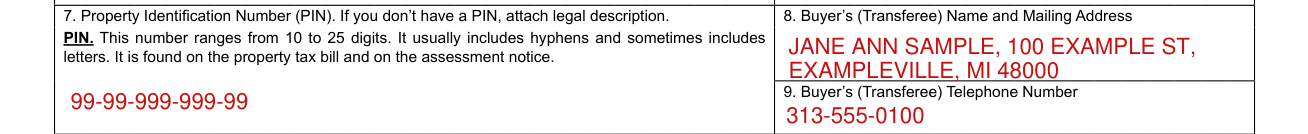
Enter the Property Identification Number (PIN). If you don't have a PIN, attach legal description. The PIN ranges from 10 to 25 digits, usually includes hyphens, sometimes includes letters, and is found on the property tax bill and on the assessment notice.
Buyer's (Transferee) Name, Mailing Address and Telephone Number
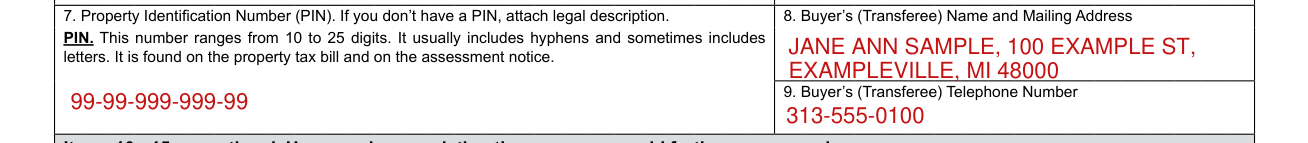
Enter the Buyer's (Transferee) Name and Mailing Address.
Enter the Buyer's (Transferee) Telephone Number.
Type of Transfer

Items 10 - 15 are optional. However, by completing them you may avoid further correspondence. For Type of Transfer, transfers include, but are not limited to, deeds, land contracts, transfers involving trusts or wills, certain long-term leases and business interest.
Check Land Contract, Lease, Deed or Other (specify).
Financial institution, related persons, down payment and financing
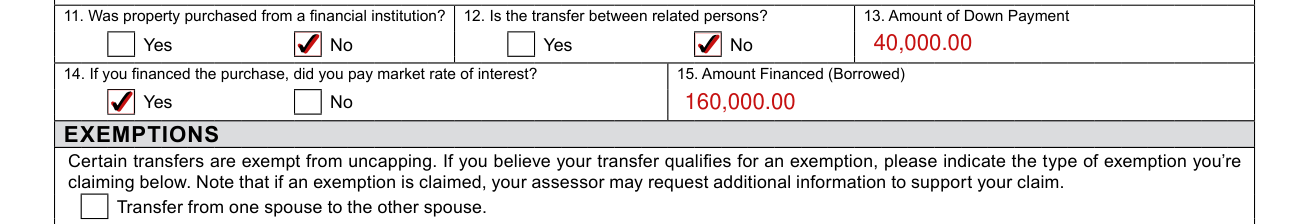
Check Yes or No for Was property purchased from a financial institution?
Check Yes or No for Is the transfer between related persons?
Enter the Amount of Down Payment.
Check Yes or No for If you financed the purchase, did you pay market rate of interest?
Enter the Amount Financed (Borrowed).
Exemptions
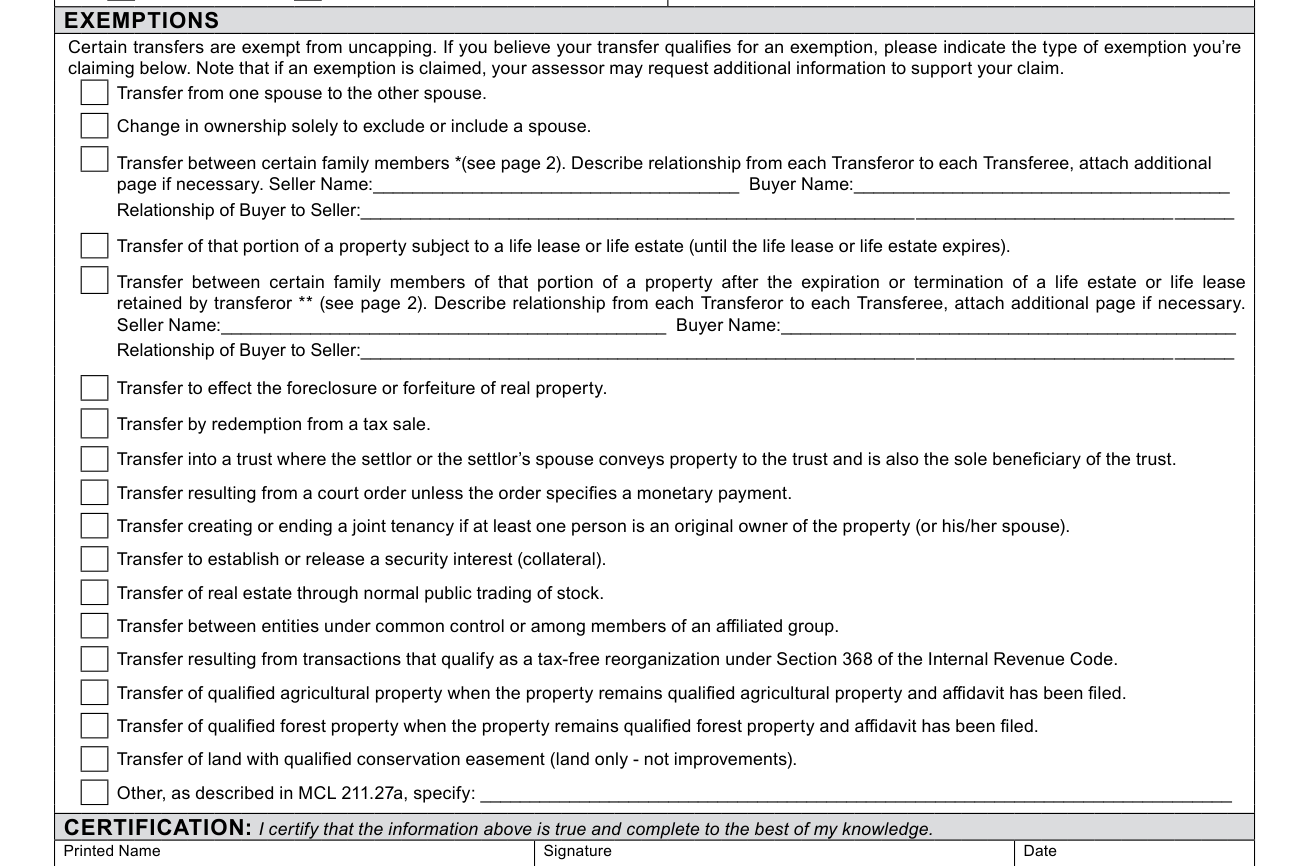
Certain transfers are exempt from uncapping. If you believe your transfer qualifies for an exemption, indicate the type of exemption you're claiming. Note that if an exemption is claimed, your assessor may request additional information to support your claim.
Check Transfer from one spouse to the other spouse.
Check Change in ownership solely to exclude or include a spouse.
Check Transfer between certain family members (see page 2) and describe the relationship from each Transferor to each Transferee, attaching an additional page if necessary: enter the Seller Name, the Buyer Name and the Relationship of Buyer to Seller.
Check Transfer of that portion of a property subject to a life lease or life estate (until the life lease or life estate expires).
Check Transfer between certain family members of that portion of a property after the expiration or termination of a life estate or life lease retained by transferor (see page 2) and describe the relationship from each Transferor to each Transferee, attaching an additional page if necessary: enter the Seller Name, the Buyer Name and the Relationship of Buyer to Seller.
Check Transfer to effect the foreclosure or forfeiture of real property.
Check Transfer by redemption from a tax sale.
Check Transfer into a trust where the settlor or the settlor's spouse conveys property to the trust and is also the sole beneficiary of the trust.
Check Transfer resulting from a court order unless the order specifies a monetary payment.
Check Transfer creating or ending a joint tenancy if at least one person is an original owner of the property (or his/her spouse).
Check Transfer to establish or release a security interest (collateral).
Check Transfer of real estate through normal public trading of stock.
Check Transfer between entities under common control or among members of an affiliated group.
Check Transfer resulting from transactions that qualify as a tax-free reorganization under Section 368 of the Internal Revenue Code.
Check Transfer of qualified agricultural property when the property remains qualified agricultural property and affidavit has been filed.
Check Transfer of qualified forest property when the property remains qualified forest property and affidavit has been filed.
Check Transfer of land with qualified conservation easement (land only - not improvements).
Check Other, as described in MCL 211.27a, and write the exemption in Other exemptions, the line after "specify".
Section 211.27a(7)(d): Beginning December 31, 2014, a transfer of that portion of residential real property that had been subject to a life estate or life lease retained by the transferor resulting from expiration or termination of that life estate or life lease, if the transferee is the transferor's or transferor's spouse's mother, father, brother, sister, son, daughter, adopted son, adopted daughter, grandson, or granddaughter and the residential real property is not used for any commercial purpose following the transfer. Upon request by the department of treasury or the assessor, the transferee shall furnish proof within 30 days that the transferee meets the requirements of this subdivision. If a transferee fails to comply with a request by the department of treasury or assessor under this subdivision, that transferee is subject to a fine of $200.00 (checked November 7, 2026). Section 211.27a(7)(u): Beginning December 31, 2014, a transfer of residential real property if the transferee is the transferor's or the transferor's spouse's mother, father, brother, sister, son, daughter, adopted son, adopted daughter, grandson, or granddaughter and the residential real property is not used for any commercial purpose following the conveyance.
Upon request by the department of treasury or the assessor, the transferee shall furnish proof within 30 days that the transferee meets the requirements of this subparagraph. If a transferee fails to comply with a request by the department of treasury or assessor under this subparagraph, that transferee is subject to a fine of $200.00 (checked November 7, 2026).
Certification
Enter your Printed Name, sign and enter the Date of signature. You certify that the information on the form is true and complete to the best of your knowledge.
Enter the Name and title, if signer is other than the owner, the Daytime Phone Number and the Email Address.
More rules for Form 2766
2766, Page 2 Instructions: This form must be filed when there is a transfer of real property or one of the following types of personal property: buildings on leased land, leasehold improvements, as defined in MCL Section 211.8(h), and leasehold estates, as defined in MCL Section 211.8(i) and (j).
Transfer of ownership means the conveyance of title to or a present interest in property, including the beneficial use of the property.
For complete descriptions of qualifying transfers, refer to MCL Section 211.27a(6)(a-j).
If your situation is different
You are the new owner
Section 211.27a(10): The buyer, grantee, or other transferee of the property shall notify the appropriate assessing office in the local unit of government in which the property is located of the transfer of ownership of the property within 45 days of the transfer of ownership, on a form prescribed by the state tax commission that states the parties to the transfer, the date of the transfer, the actual consideration for the transfer, and the property's parcel identification number or legal description.
Common questions about Form 2766
Is there a penalty?
Penalties, Section 211.27b(1): If the buyer, grantee, or other transferee does not notify the appropriate assessing office as required by section 27a(10), the property's taxable value shall be adjusted under section 27a(3) and, subject to subsection (9), any additional taxes that would have been levied if the transfer of ownership had been recorded from the date of transfer must be levied. Interest and penalty from the date the tax would have been originally levied must also be levied. For property classified under section 34c as either industrial real property or commercial real property: except as otherwise provided in subparagraph (ii), if the sale price of the property transferred is $100,000,000.00 or less, the penalty is $20.00 per day for each separate failure beginning after the 45 days have elapsed, up to a maximum of $1,000.00. If the sale price of the property transferred is more than $100,000,000.00, the penalty is $20,000.00 after the 45 days have elapsed (checked November 7, 2026). For real property other than real property classified under section 34c as industrial real property or commercial real property, the penalty is $5.00 per day for each separate failure beginning after the 45 days have elapsed, up to a maximum of $200.00 for property owned and occupied as a principal residence and $4000.00 for all other property (checked November 7, 2026).
Sources
[1] Form 2766 (Rev. 03-25), Property Transfer Affidavit, Michigan Department of Treasury (the Official source link on this page).