


Form 807 at a glance
What it is: Form 807 is the 2025 Michigan Composite Individual Income Tax Return, a collective individual income tax filing for two or more nonresident members filed by the FTE.
Who signs: By signing Form 807, the signing partner or officer declares that the filer has power of attorney from each participant to file a composite return on the participant's behalf.
Where and when to file: Mail completed returns to: Michigan Department of Treasury P.O. Box 30058 Lansing, MI 48909
Tax deadline: The composite return for any tax period ending in 2025 is due April 15, 2026.
Where to get it: Michigan tax forms are available at www.michigan.gov/taxes.
This form is used to report and pay individual income tax under Part 1 of Public Act 281 of 1967, as amended.
An FTE is not required to file Form 807, but may choose to file it on behalf of its nonresident members who elect to participate. Two or more participating nonresident members are required for an FTE to file a composite return.
The 2025 composite return is for filers whose tax year ends in 2025.
For participation in a composite return, all of these conditions must apply to the nonresident ultimate owner. The owner is subject to Michigan individual income tax and was not a Michigan resident (full-year or part-year). The owner agrees to claim only one Michigan exemption, does not have a federal excess business loss limitation, and is not a C corporation or has not elected to file federally as a C corporation.
What to bring and attach to Form 807
Include only the following items, as applicable, with the composite return.
A copy of U.S. Form 1065 (5 pages) or U.S. Form 1120S (5 pages); Michigan Schedule of Apportionment (Form MI-1040H); completed Schedule A, Schedule of Participants; Tiered Structure Schedule; completed Schedule B, Schedule of Nonparticipants; completed Schedule C, Schedule of Michigan Residents; a statement signed by an authorized officer or general partner certifying that each participant has been informed of the terms and conditions of this program of participation; supporting documentation to support the flow-through entity tax credit, if applicable; and a copy of Form 4.
A filled-in Form 807 example: an entity files a composite return for two members
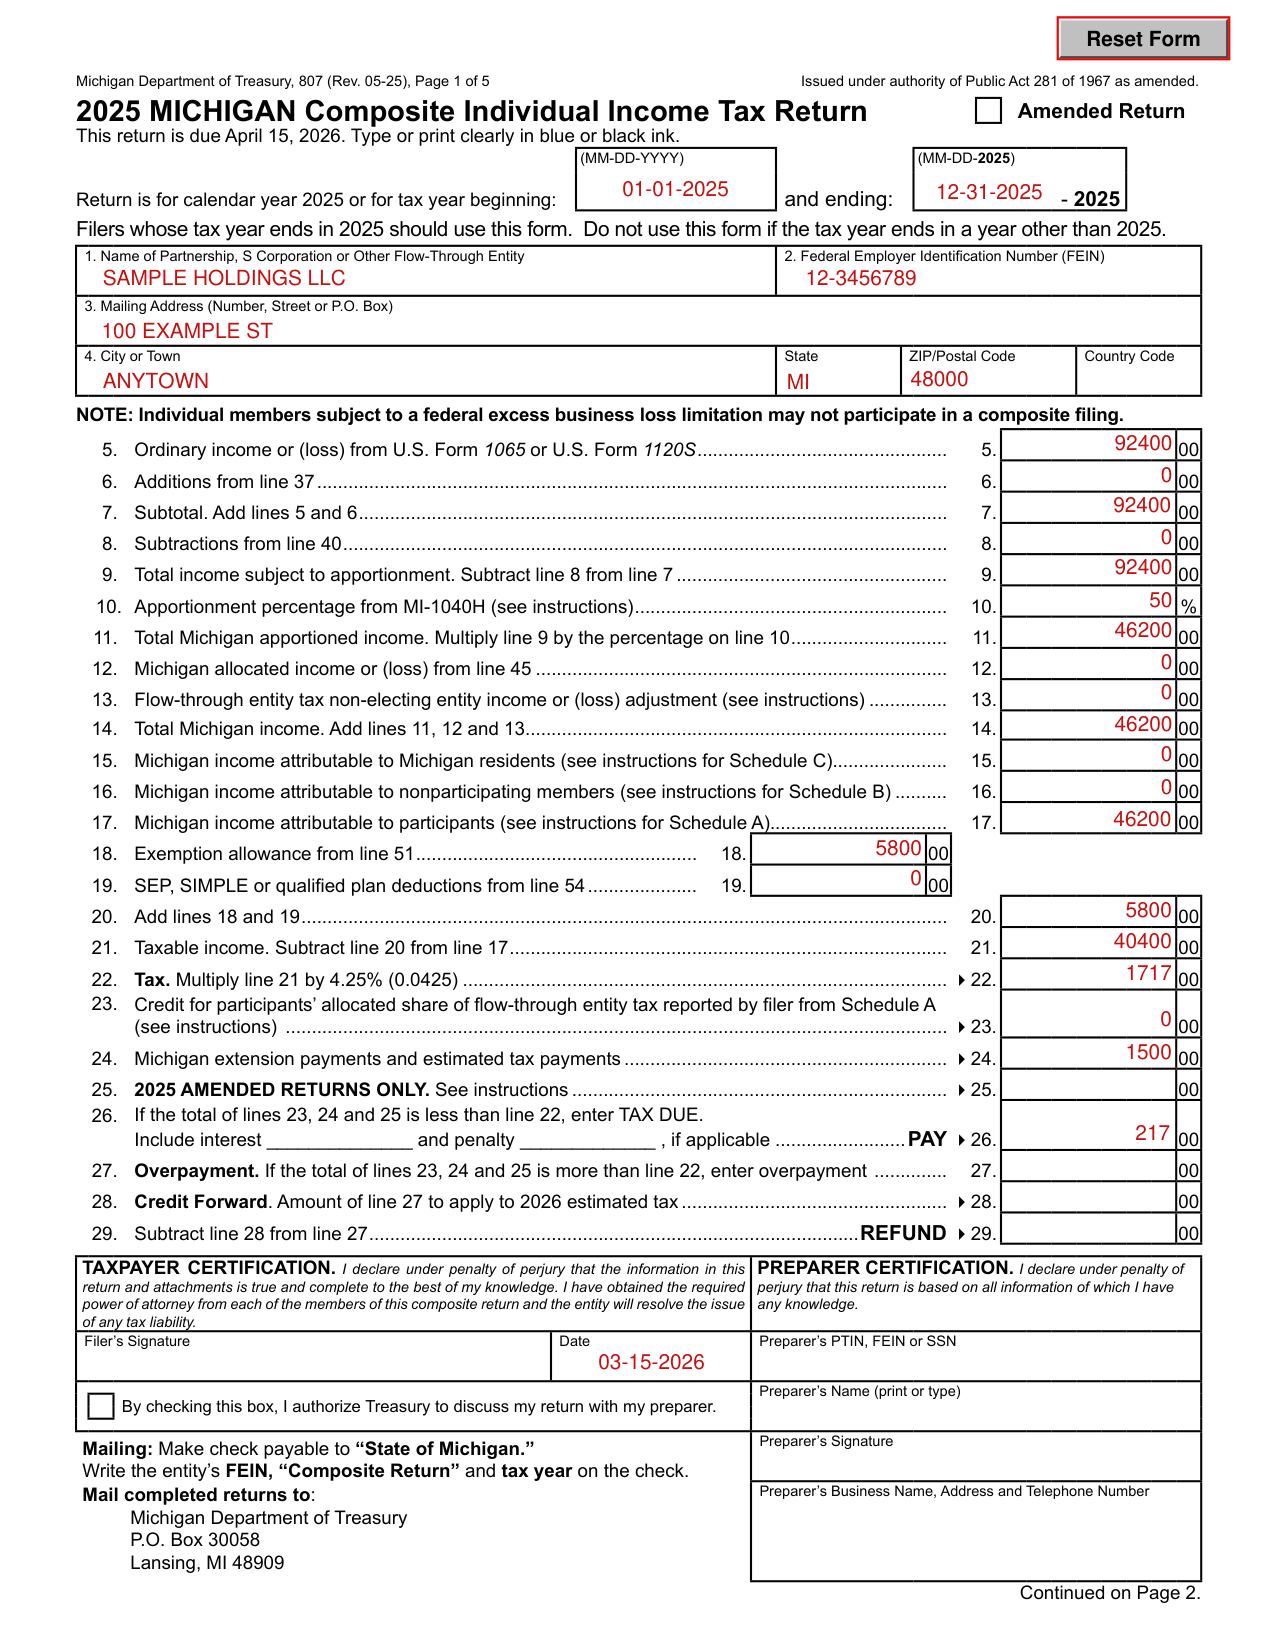
How to fill out Form 807, box by box
Boxes 1 to 4, the entity and the tax year
Return is for calendar year 2025 or for tax year beginning and ending, entered as MM-DD-YYYY and MM-DD-2025.
Enter the Name of Partnership, S Corporation or Other Flow-Through Entity in box 1 and the Federal Employer Identification Number (FEIN) in box 2.
Enter the Mailing Address (Number, Street or P.O. Box) in box 3, and the City or Town, State, ZIP/Postal Code and Country Code in box 4.
Lines 5 to 14, the income
On line 5, enter ordinary income or (loss) from U.S. Form 1065, line 23 or U.S. Form 1120S, line 22.
Line 6 is Additions from line 37, and line 8 is Subtractions from line 40. For line 7, the Subtotal, add lines 5 and 6. For line 9, the Total income subject to apportionment, subtract line 8 from line 7.
On line 10, enter the apportionment percentage from Form MI-1040H. For line 11, the Total Michigan apportioned income, multiply line 9 by the percentage on line 10.
Line 12 is the Michigan allocated income or (loss) from line 45, and line 13 is the Flow-through entity tax non-electing entity income or (loss) adjustment (see instructions). The amount on line 14 should equal the total of lines 15, 16 and 17.
Schedule A: Schedule of Participants
Complete Schedule A, Schedule of Participants for all participants; it must have at least two participants.
Carry the grand total of Column 2 to line 17. The grand total of Column 3 should reconcile to line 22. Carry the grand total of Column 4 to line 23.
Schedule B: Schedule of Nonparticipants
Complete Schedule B, Schedule of Nonparticipants for all nonparticipants that are not Michigan residents. Carry the grand total of Column 2 to line 16.
Schedule C: Schedule of Michigan Residents
Complete Schedule C, Schedule of Michigan Residents for Michigan residents. A Michigan resident may not participate on a composite return. Carry the grand total of Column 2 to line 15.
Lines 18 to 21 and 49 to 51, the exemption allowance and taxable income
Line 18 is the Exemption allowance from line 51, and line 19 is the SEP, SIMPLE or qualified plan deductions from line 54. For line 20, add lines 18 and 19. For line 21, the Taxable income, subtract line 20 from line 17.
For line 49, the Prorated exemption allowance per participant, multiply line 48 by $5,800 (exemption allowance) (checked November 8, 2026). Line 50 is the Number of participants included in this return, and line 51 is the Total prorated exemption.
Lines 22 to 29, the tax, payments and refund
For line 22, Tax, multiply line 21 by 4.25% (0.0425). The tax should reconcile to the grand total from Column 3 of the Schedule A, Schedule of Participants.
On line 23, enter the total of participants' allocated share of flow-through entity tax reported on Schedule A, Schedule of Participants, Column 4. On line 24, enter the Michigan extension payments and estimated tax payments.
Box 25 is 2025 AMENDED RETURNS ONLY (425. 00). Line 26 is PAY (426. 00): if the total of lines 23, 24 and 25 is less than line 22, enter the balance of the tax due. Enter any applicable penalties and interest in the spaces provided. Add tax, penalty and interest together and enter the total on this line.
Make the check payable to “State of Michigan.” Write the filing company's FEIN, “Composite Return” and the tax year on the front of the check.
On line 27, Overpayment, if the total of lines 23, 24 and 25 is more than line 22, enter overpayment. On line 28, Credit Forward, enter the amount of line 27 to apply to 2026 estimated tax. For line 29, REFUND, subtract line 28 from line 27.
Signing the return and the preparer
TAXPAYER CERTIFICATION: “I declare under penalty of perjury that the information in this return and attachments is true and complete to the best of my knowledge. I have obtained the required power of attorney from each of the members of this composite return and the entity will resolve the issue of any tax liability.”
Check the box to indicate if Treasury may discuss your return with your preparer. The Taxpayer Protection Act requires paid preparers to sign the return and provide his or her preparer tax identification number.
If your situation is different
You are amending the return
To amend, file Form 807 and check the Amended Return box at the top of page 1 of the form. Provide a statement to explain the reason(s) for amending. Include all applicable schedules and supporting documentation. It is not necessary to include a copy of the original return.
Line 25 is for amended returns only. Enter the refund and/or credit forward amount received on the original return as a negative number. Enter the amount paid with the original return as a positive number. Do not include any interest or penalty paid with the original return.
You request an extension of time to file
The filer may request an extension of time to file by filing an Application for Extension of Time to File Michigan Tax Returns (Form 4) on or before the original due date of the composite return. A Michigan extension, Form 4, must be filed even if the FTE files a federal extension. An extension of time to file is NOT an extension of time to pay.
The FTE's tax year does not end in 2025
If the FTE's tax year does not end in 2025, do not use this form.
Common questions about Form 807
Is there a deadline?
The composite return for any tax period ending in 2025 is due April 15, 2026.
Where do I file it?
Mail completed returns to: Michigan Department of Treasury P.O. Box 30058 Lansing, MI 48909
Are there fees?
In Michigan Treasury eServices you can file your return (no fee).
Is there a penalty?
The filer must agree to be responsible for the payment of any additional tax, interest and penalties as finally determined.
Sources
[1] Form 807 (Rev. 05-25), 2025 Michigan Composite Individual Income Tax Return, Michigan Department of Treasury (the Official source link on this page).