

Form IT-2659 at a glance
What it is: IT-2659 is the Estimated Tax Penalties for Partnerships and New York S Corporations (for underpayment or nonpayment of estimated tax).
Where and when to file: Mail this form and payment to: NYS TAX DEPARTMENT - IT-2659, PO BOX 15179, ALBANY NY 12212-5179.
For Partnerships and New York S Corporations: underpayment or nonpayment of estimated tax including metropolitan commuter transportation mobility tax (MCTMT) required to be paid on behalf of partners and shareholders who are corporations or nonresident individuals.
A filled-in Form IT-2659 example: a partnership with a penalty of 250.00
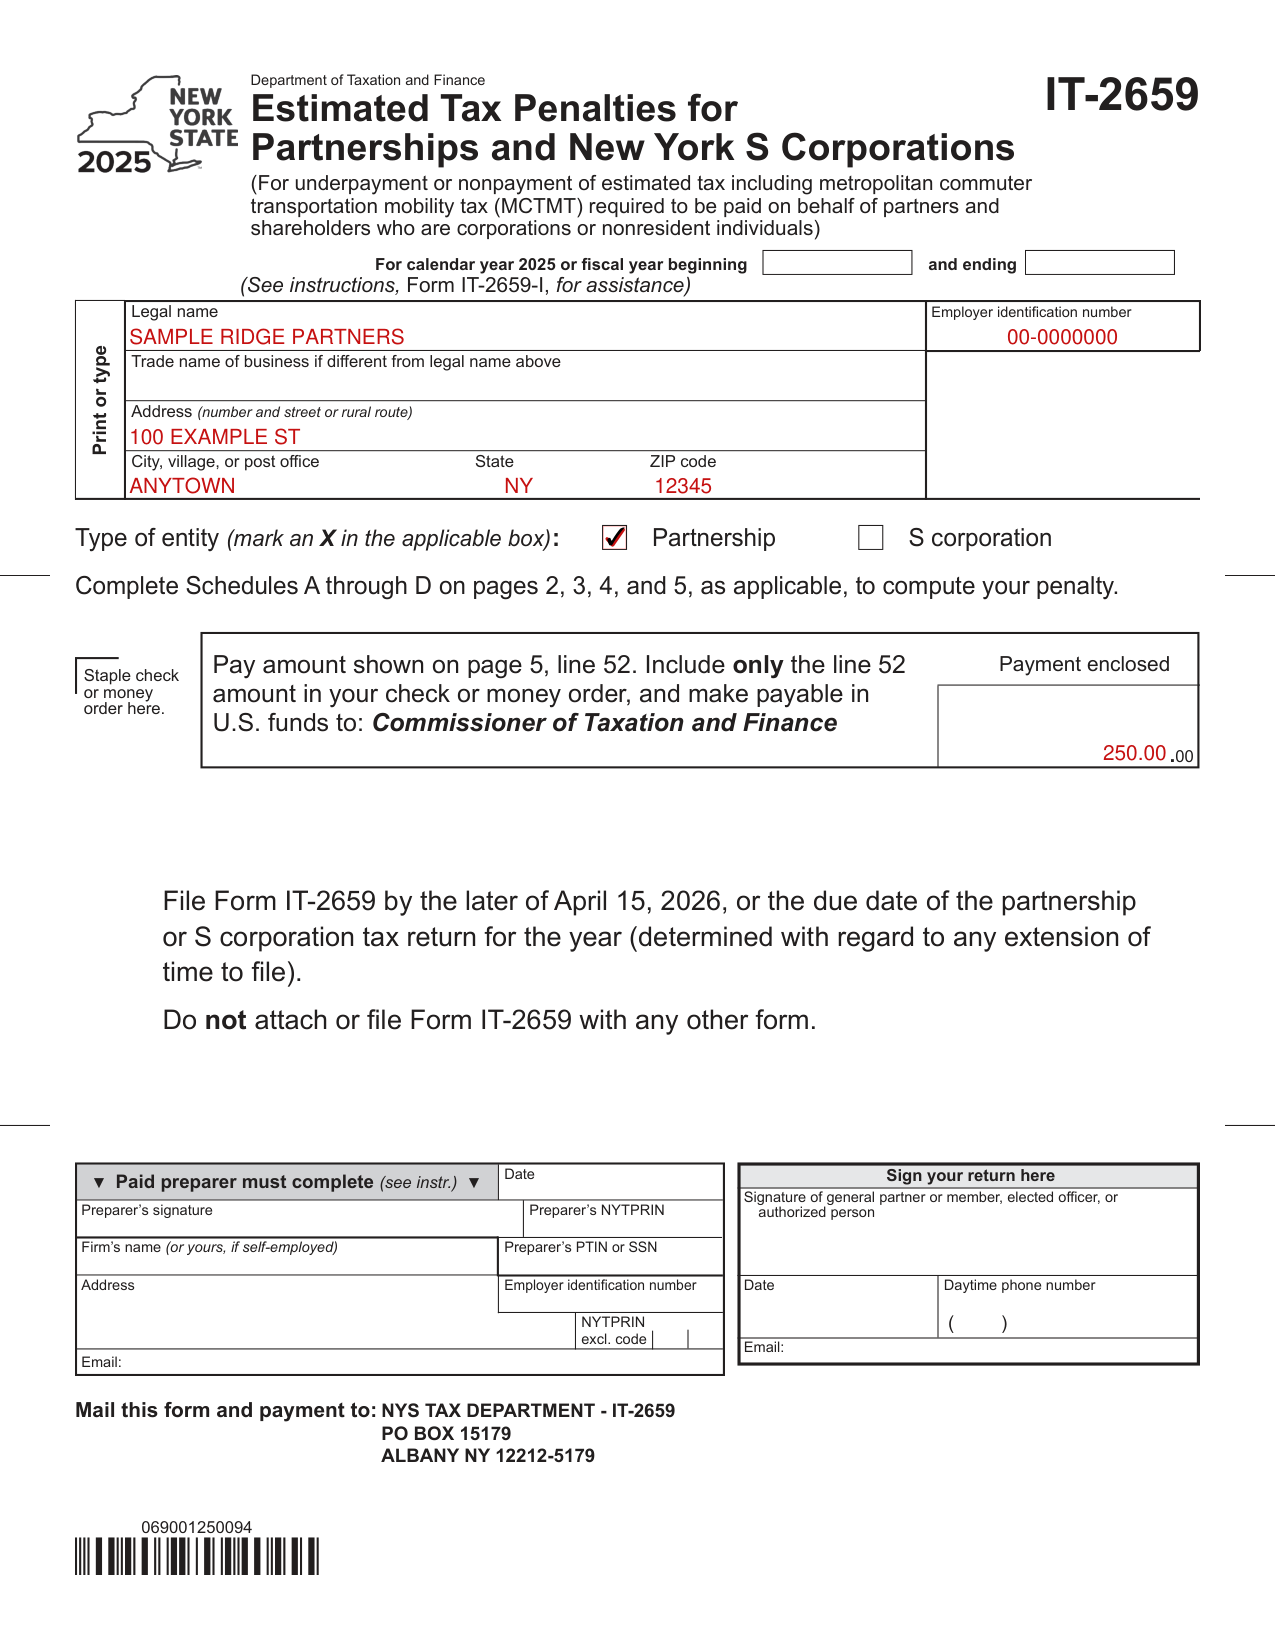
How to fill out Form IT-2659, box by box
For calendar year 2025 or fiscal year beginning and ending

For calendar year 2025 or fiscal year beginning and ending.
Legal name, Employer identification number, trade name and address
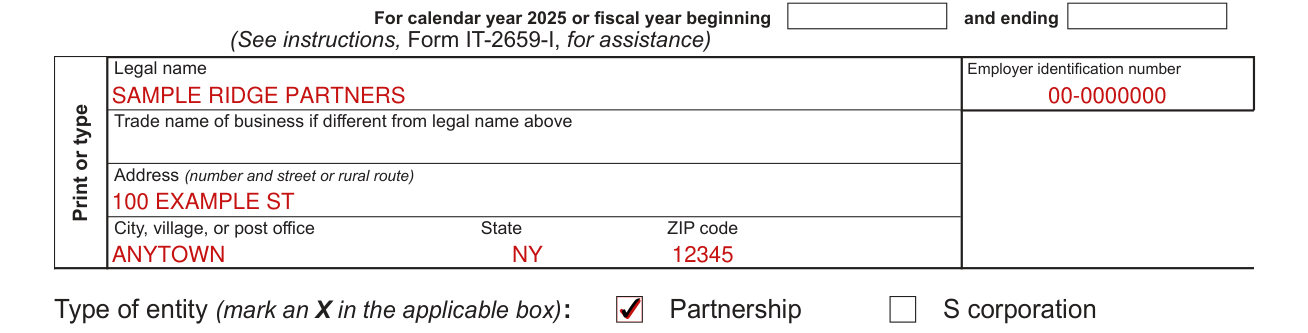
Enter the Legal name and the Employer identification number.
Enter the Trade name of business if different from legal name.
Enter the Address (number and street or rural route), the City, village, or post office, the State and the ZIP code.
Type of entity

Type of entity: mark an X in the applicable box, Partnership or S corporation.
Payment enclosed
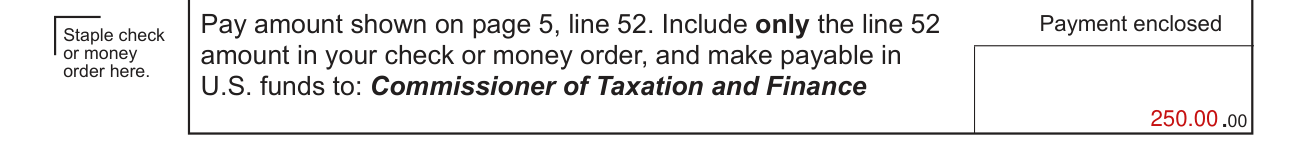
Pay amount shown on page 5, line 52. Include only the line 52 amount in your check or money order, and make payable in U.S. funds to: Commissioner of Taxation and Finance.
Payment enclosed: staple check or money order here.
Sign your return here

Sign your return here: Signature of general partner or member, elected officer, or authorized person, with the Date, Daytime phone number and Email.
Paid preparer must complete
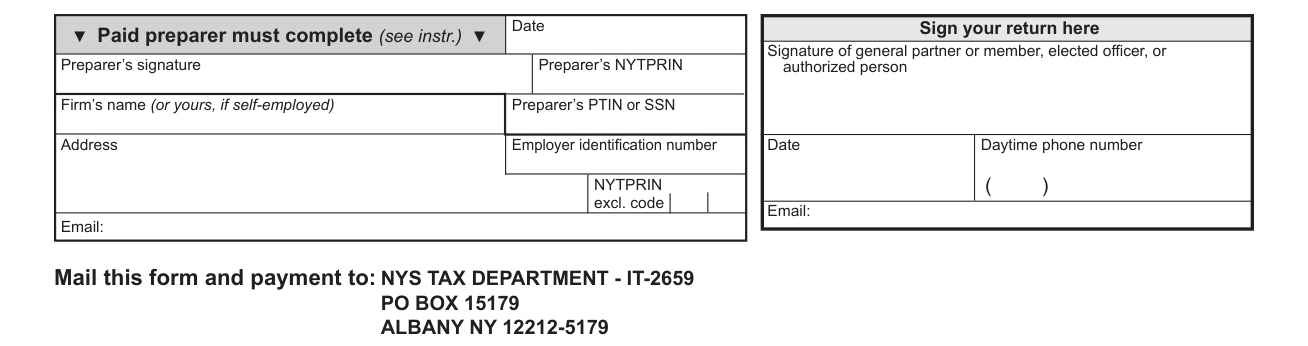
Paid preparer must complete (see instr.): Date, Preparer's signature, Preparer's NYTPRIN, Firm's name (or yours, if self-employed), Preparer's PTIN or SSN, Address, Employer identification number, NYTPRIN excl. code and Email.
Schedule A - Computation of estimated tax underpayment
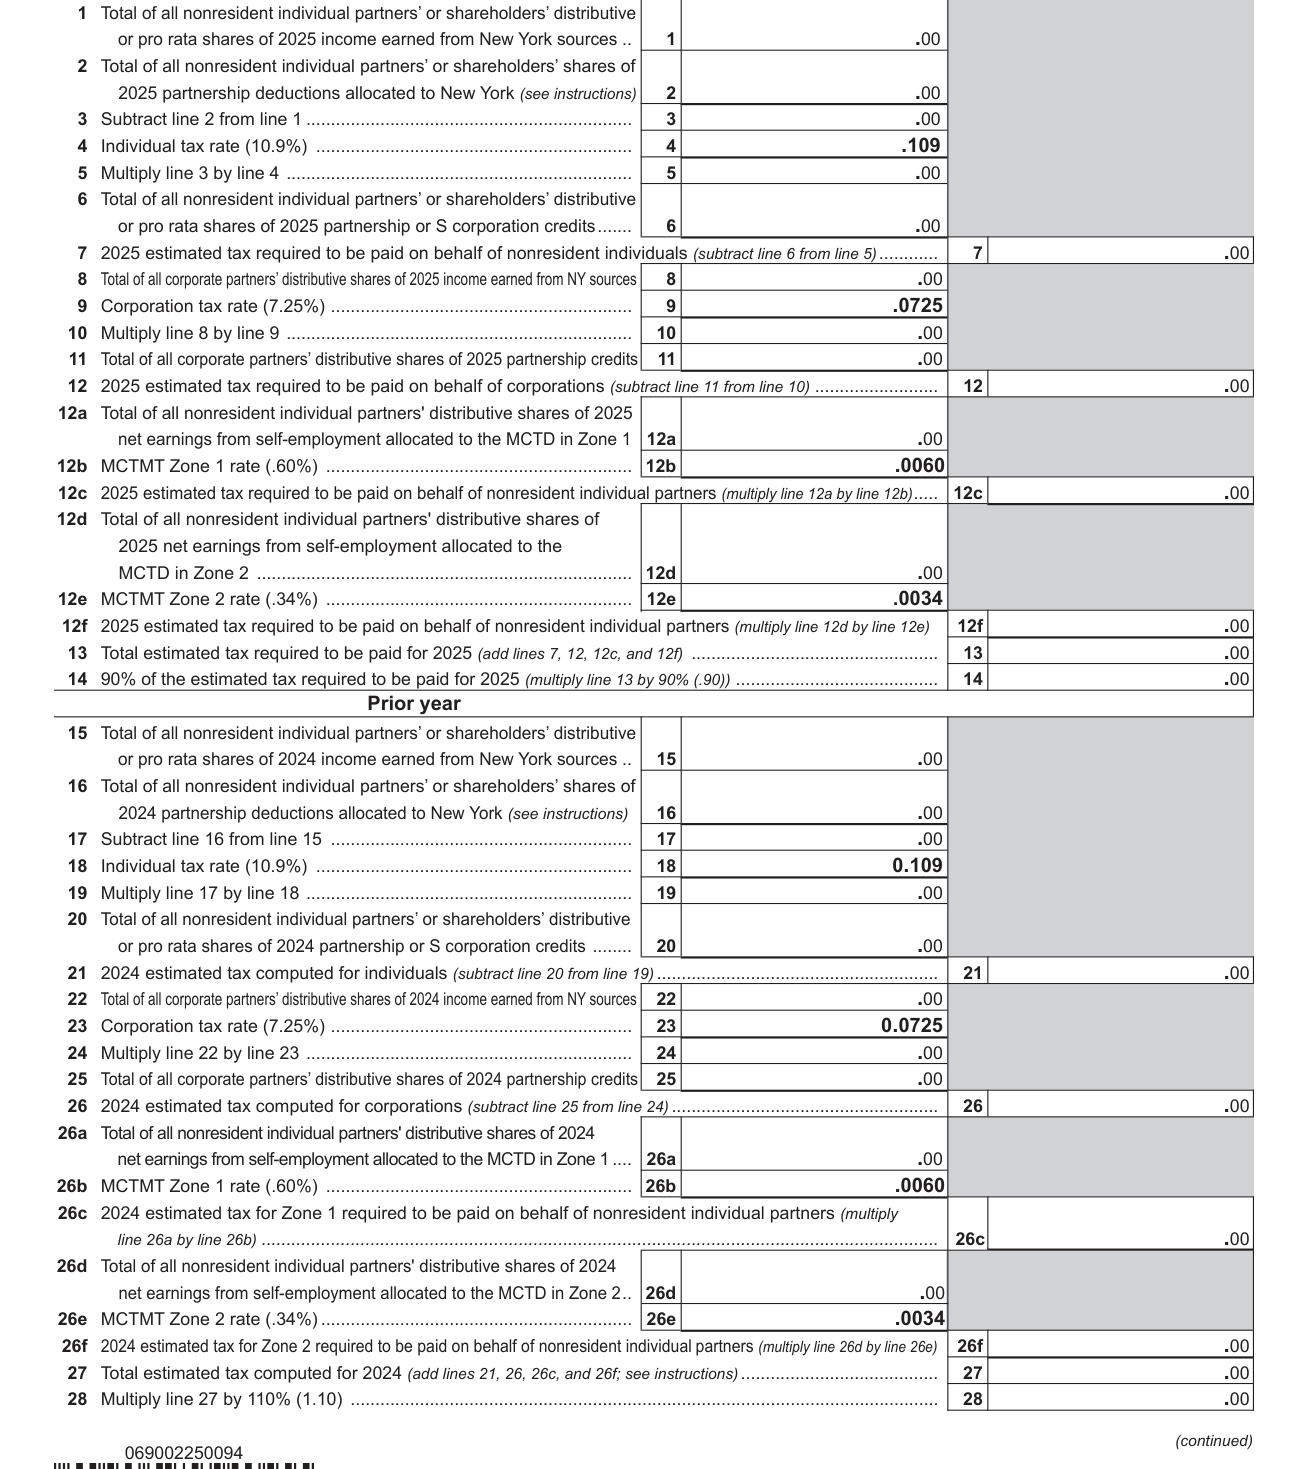
Schedule A - Computation of estimated tax underpayment (if any). All filers must complete this part. Only include partners and shareholders who are subject to estimated tax paid on their behalf by the partnership or New York S corporation (see instructions).
Line 3: subtract line 2 from line 1. Line 4: Individual tax rate (10.9%). Line 5: multiply line 3 by line 4.
Line 7: 2025 estimated tax required to be paid on behalf of nonresident individuals (subtract line 6 from line 5). Line 12: 2025 estimated tax required to be paid on behalf of corporations (subtract line 11 from line 10).
Line 13: Total estimated tax required to be paid for 2025 (add lines 7, 12, 12c, and 12f). Line 14: 90% of the estimated tax required to be paid for 2025 (multiply line 13 by 90% (.90)).
Line 27: Total estimated tax computed for 2024 (add lines 21, 26, 26c, and 26f; see instructions). Line 28: multiply line 27 by 110% (1.10).
Schedule B - Short method for computing the penalty
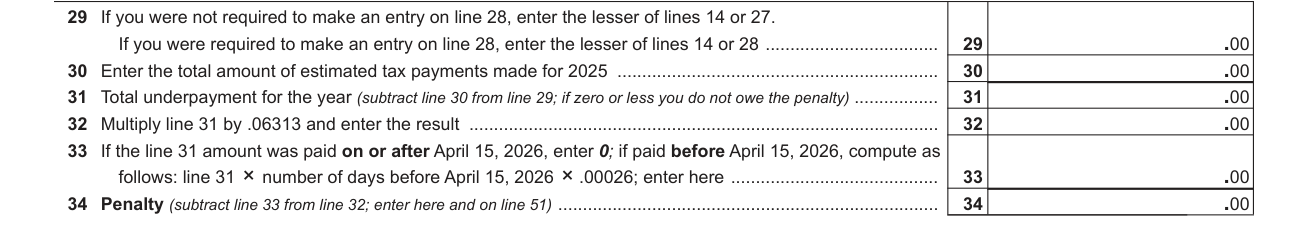
Schedule B - Short method for computing the penalty. Complete lines 29 through 34 if you paid four equal estimated tax installments (on the due dates), or if you made no payments of estimated tax. Otherwise, you must complete Schedule C.
Line 29: if you were not required to make an entry on line 28, enter the lesser of lines 14 or 27. If you were required to make an entry on line 28, enter the lesser of lines 14 or 28.
Line 31: Total underpayment for the year (subtract line 30 from line 29; if zero or less you do not owe the penalty). Line 34: Penalty (subtract line 33 from line 32; enter here and on line 51).
Schedule C - Part 1 - Computing the underpayment
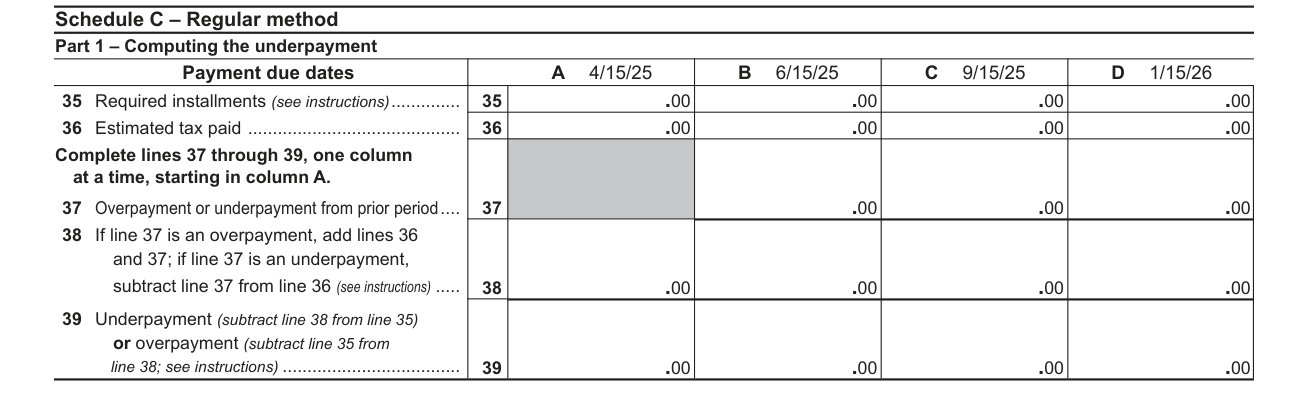
Schedule C - Regular method. Part 1 - Computing the underpayment: the payment due dates are A 4/15/25, B 6/15/25, C 9/15/25 and D 1/15/26. Line 35: Required installments (see instructions). Line 36: Estimated tax paid. Complete lines 37 through 39, one column at a time, starting in column A.
Line 38: If line 37 is an overpayment, add lines 36 and 37; if line 37 is an underpayment, subtract line 37 from line 36 (see instructions). Line 39: Underpayment (subtract line 38 from line 35) or overpayment (subtract line 35 from line 38; see instructions).
Part 2 - Computing the penalty
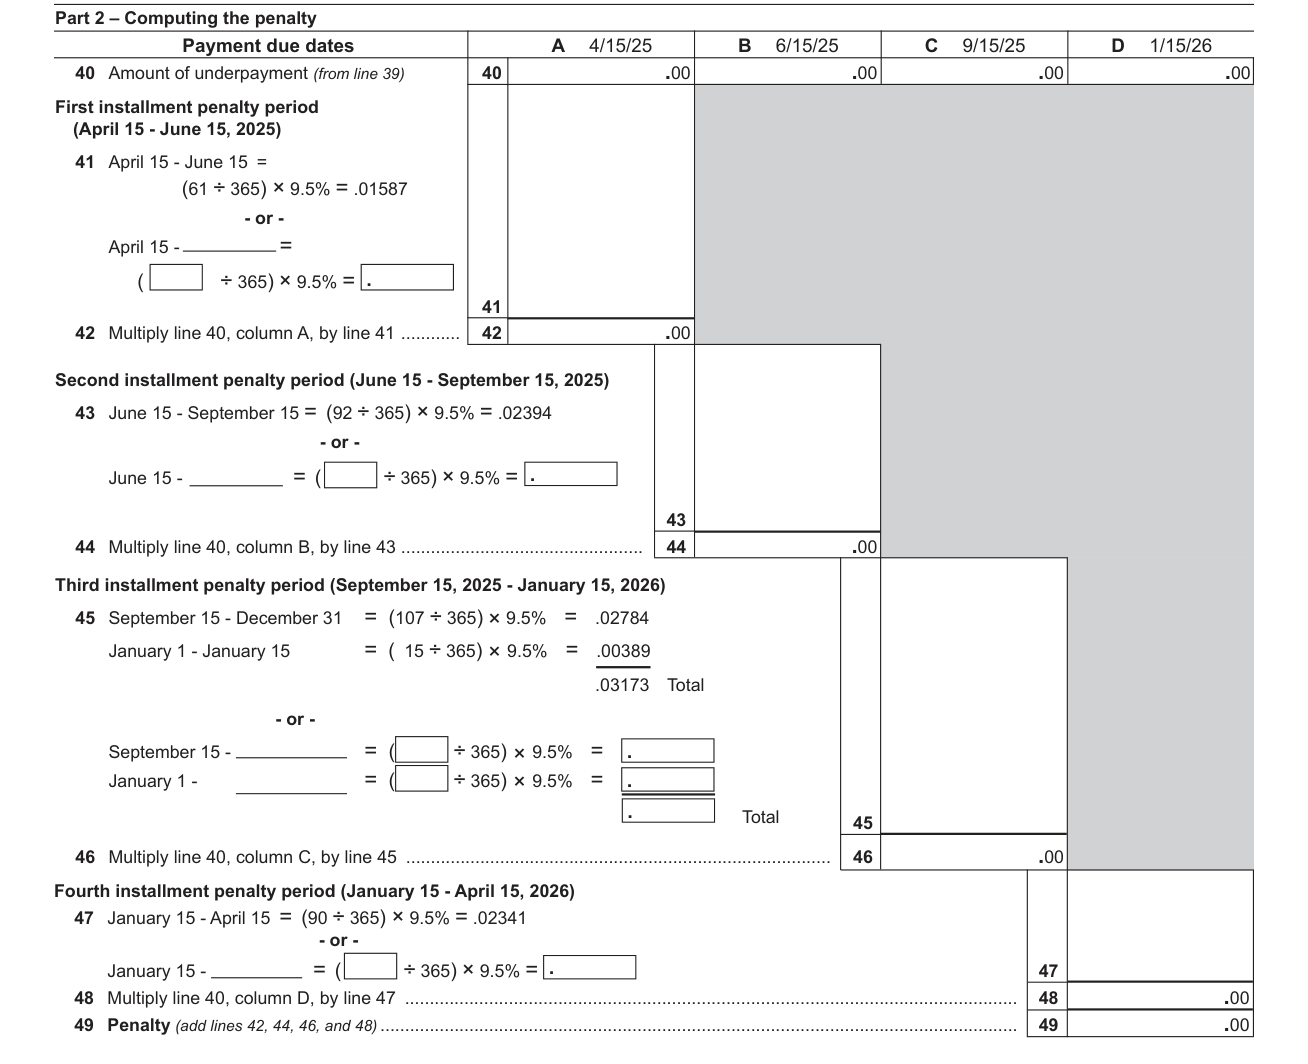
Part 2 - Computing the penalty. Line 40: Amount of underpayment (from line 39).
Line 49: Penalty (add lines 42, 44, 46, and 48).
Schedule D - Failure to pay estimated tax on behalf of partners or shareholders
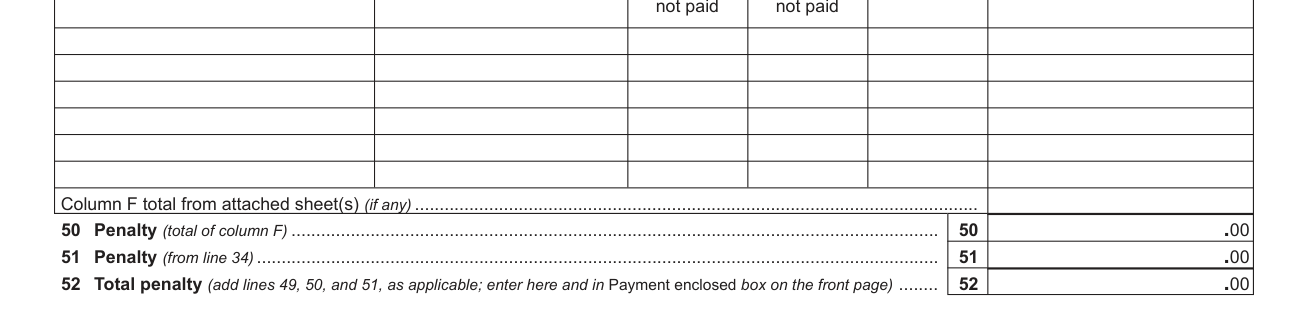
Schedule D - Failure to pay estimated tax on behalf of partners or shareholders who are corporations or nonresident individuals.
If you are listing more than six partners or shareholders, attach additional sheet(s) using the same six-column format. Include all column F totals from additional sheets on the line provided.
A: Name of partner/shareholder. B: Identifying number (EIN/SSN). C: NYS Number of quarters (1-4) estimated tax was not paid. D: MCTMT Number of quarters (1-4) estimated tax was not paid.
E: Total of columns C and D (C + D). F: Column E × $50 (checked November 8, 2026).
Line 52: Total penalty (add lines 49, 50, and 51, as applicable; enter here and in Payment enclosed box on the front page).
More rules for Form IT-2659
Complete Schedules A through D on pages 2, 3, 4, and 5, as applicable, to compute your penalty.
Do not attach or file Form IT-2659 with any other form.
Common questions about Form IT-2659
Is there a deadline?
File Form IT-2659 by the later of April 15, 2026, or the due date of the partnership or S corporation tax return for the year (determined with regard to any extension of time to file).
Where do I file it?
Mail this form and payment to: NYS TAX DEPARTMENT - IT-2659, PO BOX 15179, ALBANY NY 12212-5179.
Sources
[1] Form IT-2659 (2025), Estimated Tax Penalties for Partnerships and New York S Corporations, New York State Department of Taxation and Finance (the Official source link on this page).