
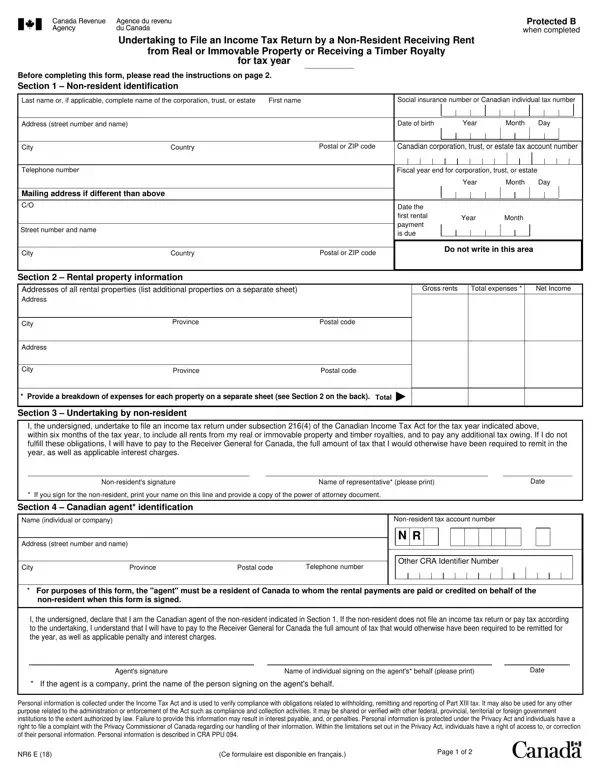
Form NR6 at a glance
What it is: NR6 is the Undertaking to File an Income Tax Return by a Non-Resident Receiving Rent from Real or Immovable Property or Receiving a Timber Royalty.
Who signs: Section 3 - Undertaking by non-resident: Sign and date in the designated area for the undertaking to be valid. If a representative signs on your behalf, he or she must print his or her name in the space provided and attach a copy of the power of attorney document. Section 4 - Canadian agent identification: Sign and date in the designated area.
Use this form if you are a non-resident receiving rent from real or immovable property or a timber royalty and you want your agent to be able to elect to deduct and remit tax at the applicable rate on the net amounts available to you.
A filled-in Form NR6 example: a non-resident files for one Canadian rental
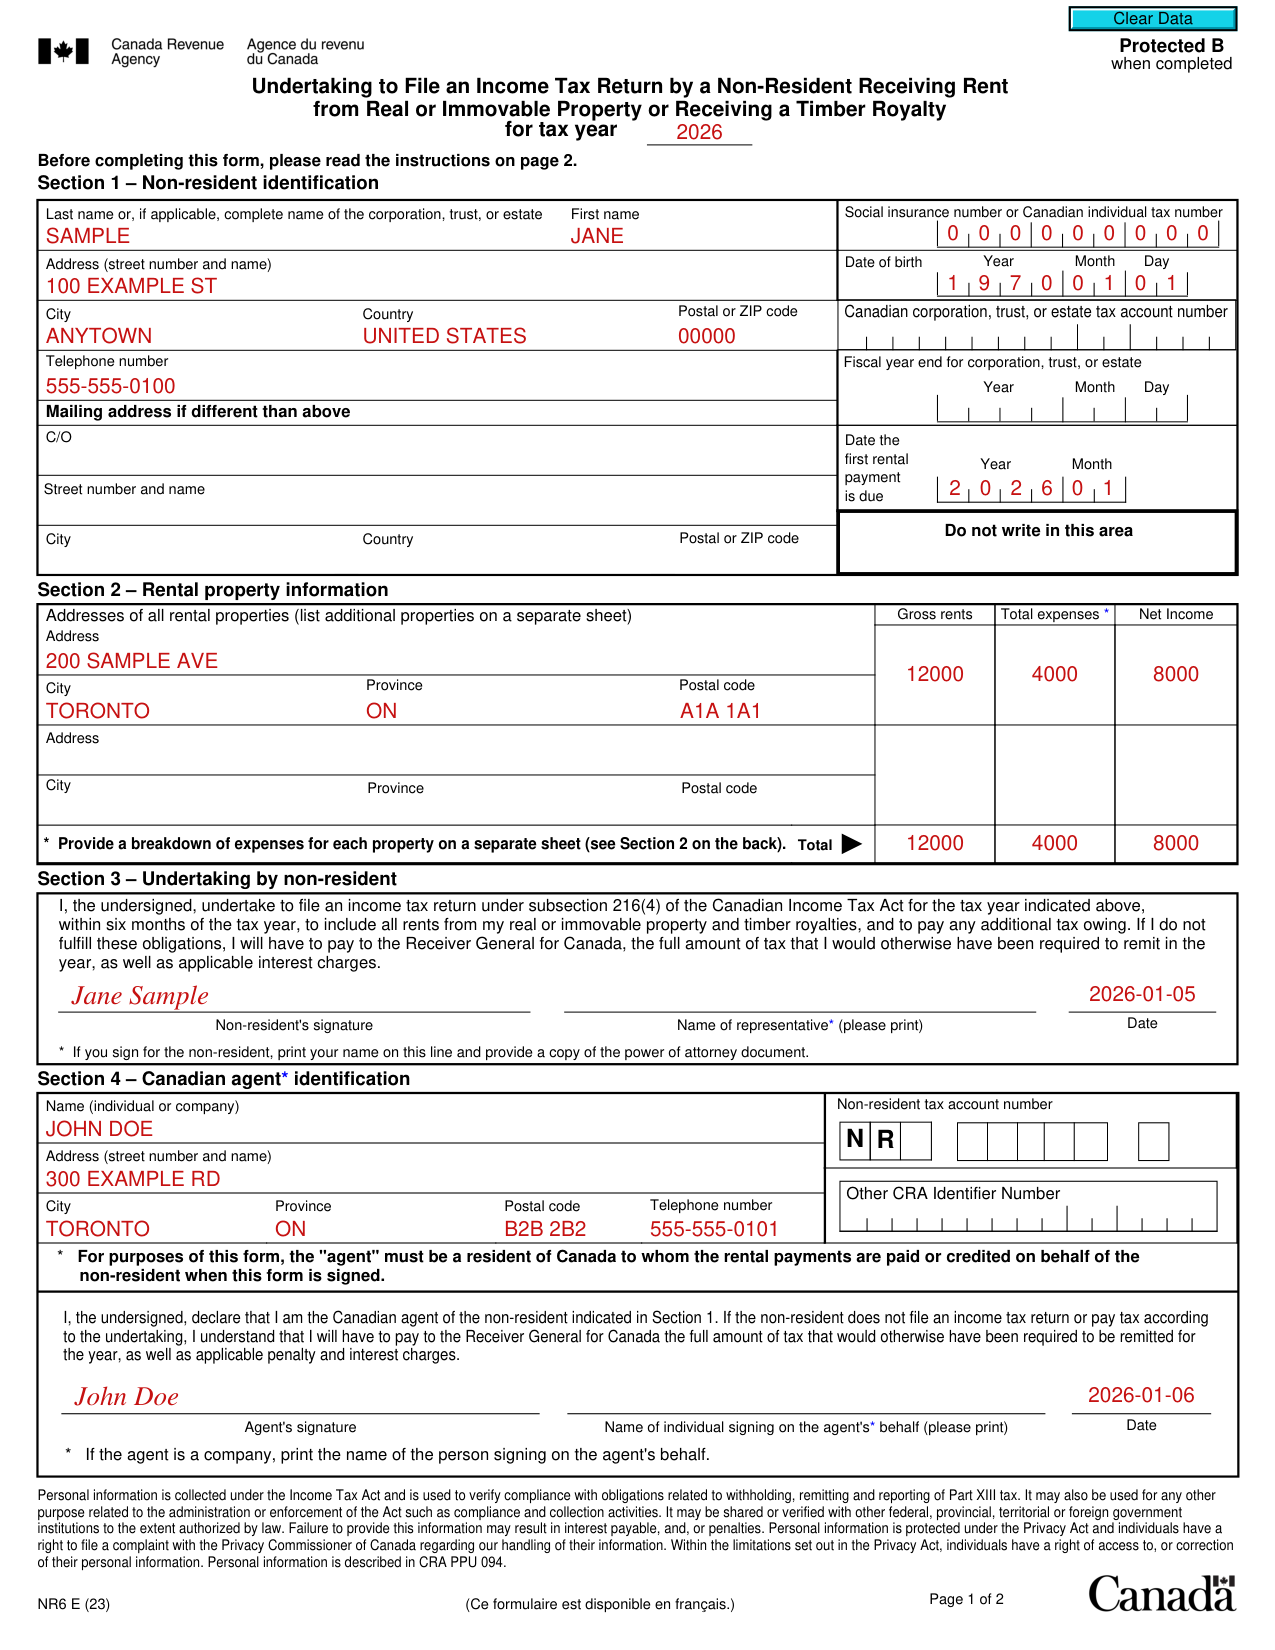
How to fill out Form NR6, box by box
Tax year

File a separate form for each tax year.
For individuals, the tax year corresponds to the calendar year (January 1 to December 31). For corporations, estates, and trusts, the tax year can differ from the calendar year; therefore, for these entities, indicate the fiscal year end.
Section 1 - Non-resident identification
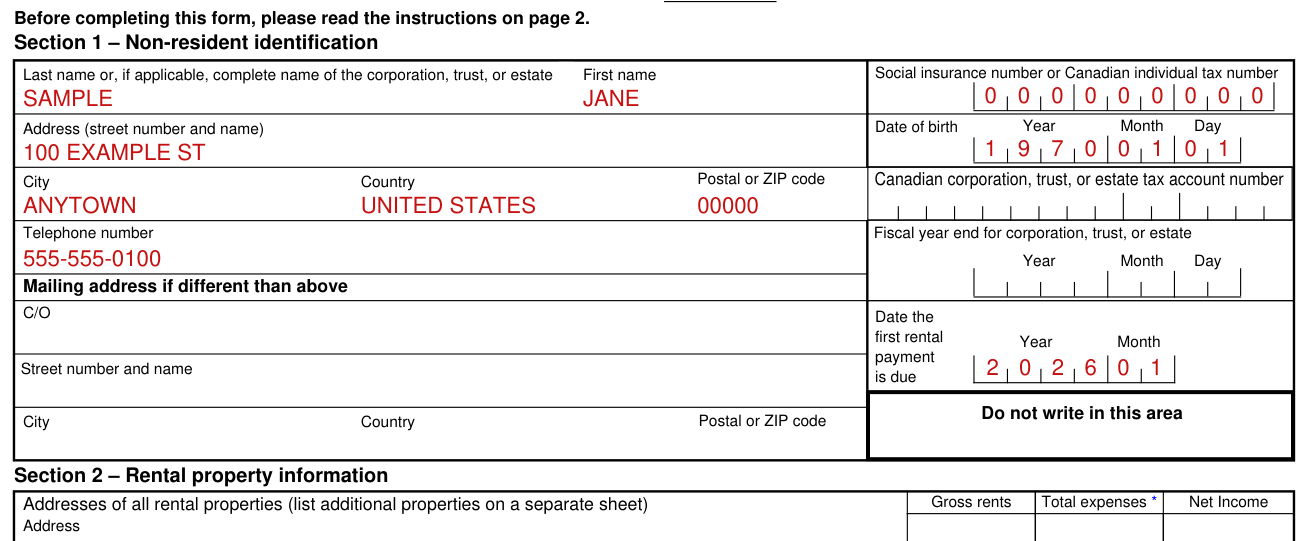
Print your name and address, including your country of residence, and telephone number.
For individuals, provide your Canadian social insurance number (SIN) or individual tax number (ITN) and your date of birth.
If you don't have a SIN or ITN, please complete Form T1261, Application for a Canada Revenue Agency Individual Tax Number (ITN) for Non-Residents.
For corporations, trusts, and estates, provide your Canadian tax account number as well as your fiscal year end.
Provide your mailing address if it is different from your residential address.
Provide the first month of the year for which you expect to receive rental income.
Section 2 - Rental property information
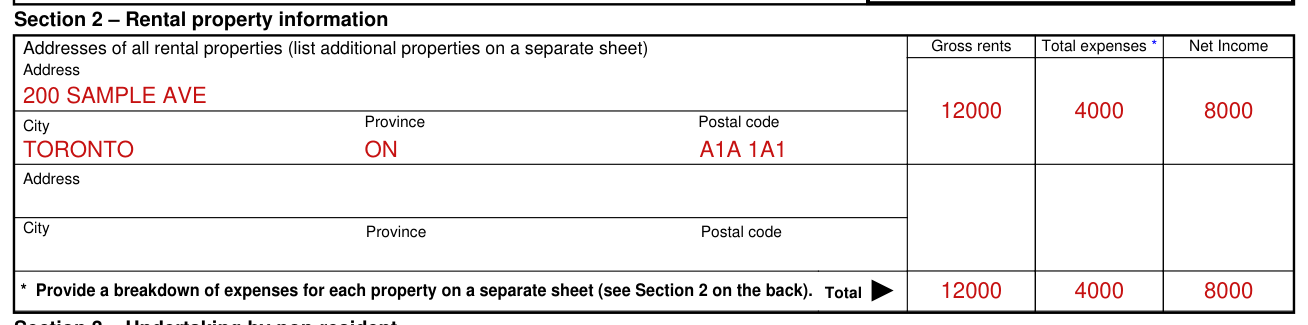
List all rental properties and provide the address of each rental property.
Include the street number and name, apartment or suite number (lot and concession if a rural property), town or city, province or territory, and postal code.
List additional properties on a separate sheet.
Provide the estimated gross income, total expenses, and net income for the year for each property.
On a separate sheet, provide an itemized estimate of the expenses you expect to incur during the year for each property. (You have to provide this information.)
Include the current and prepaid expenses that relate to the day to day management of your property.
Do not include capital cost allowance, depreciation, and amortization. You can claim these amounts when you file your income tax return.
Each non-resident member of a partnership filing an undertaking should report only his or her share of the gross rents, total expenses, and net income.
Rent on real or immovable property includes crop-sharing proceeds.
Section 3 - Undertaking by non-resident
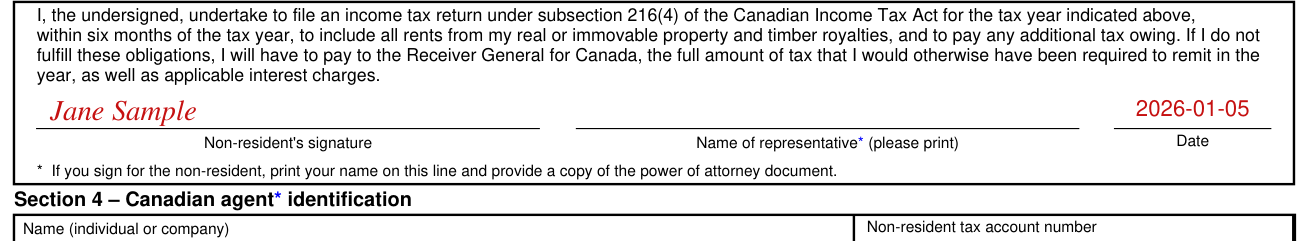
Section 3 - Undertaking by non-resident: Sign and date in the designated area for the undertaking to be valid.
If you do not fulfill your obligations as specified in the undertaking, you will have to pay to the Receiver General for Canada, the full amount of tax that you would otherwise have been required to remit in the year, as well as applicable interest charges.
The required amount of tax is calculated at the statutory rate of 25% of the gross rental income, minus the amount of tax already remitted for the year.
Section 4 - Canadian agent identification
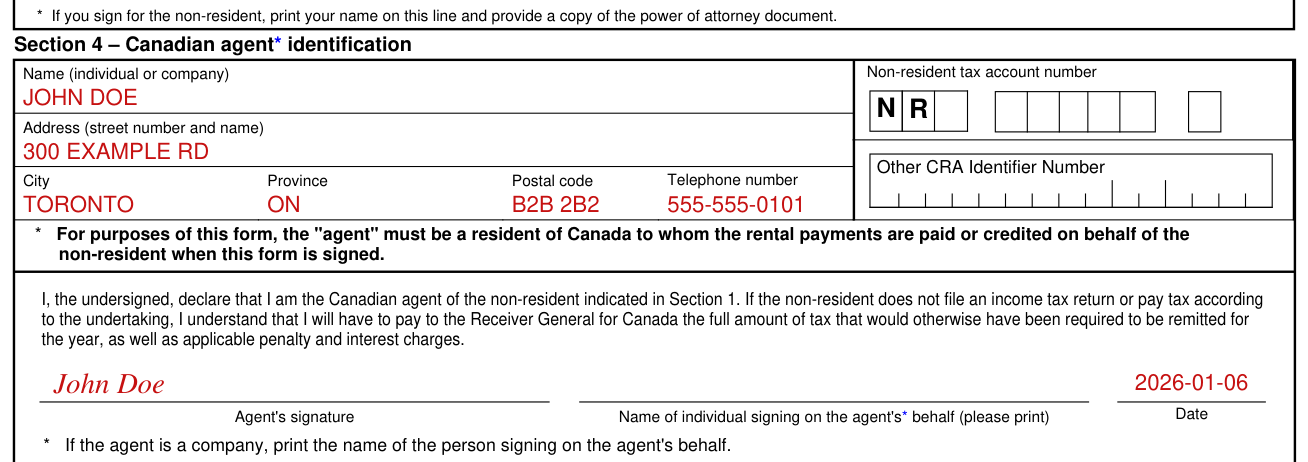
To be considered an agent for the purposes of this form, you must be a resident of Canada to whom the rental payments are paid or credited on behalf of the non-resident when this form is signed.
Print your name, address, city or town, province, postal code, and telephone number.
Provide your non-resident tax account number. If you do not have one, one is assigned to you when this form is processed.
Enter your other CRA identifier number, such as a business number (BN); social insurance number (SIN), temporary tax number (TTN), individual tax number (ITN); or trust account number, if applicable.
Section 4 - Canadian agent identification: Sign and date in the designated area.
If the non-resident does not file the income tax return or pay tax according to the conditions of the undertaking, you as agent will have to pay to the Receiver General for Canada the full amount of tax that would otherwise have been required to be remitted in the year, as well as applicable penalty and interest charges.
The agent has to file an NR4 return before March 31 of the year after the year in which the rental income was paid or credited, or within 90 days of the fiscal year end for estates and trusts.
If you fail to file the NR4 return by the due date, you may be charged a penalty and interest.
More rules for Form NR6
Complete all applicable sections on this form. An incomplete form will not be accepted as a valid undertaking and will be returned.
Both the non-resident and the agent are advised in writing when a valid undertaking is approved.
Your agent must continue to withhold and remit non-resident tax based on the gross rental income until a valid undertaking is approved in writing.
Any non-resident tax withheld must be received by the 15th day of the month following the month during which the rental payment was paid or credited to the agent on the non-resident's behalf.
The non-resident undertakes to file an income tax return, whether there is a profit or a loss situation, under subsection 216(4) of the Canadian Income Tax Act within six months of the end of the tax year for which the undertaking is filed.
Common questions about Form NR6
Is there a deadline?
File this form on or before the first day of each tax year, or when the first rental payment is due.
Where do I file it?
Send this application to the Non-Resident Withholding Section, Canada Revenue Agency, PO Box 20000, STN A, Sudbury ON P3A 5C1. You can also send it online through the Submit Documents service in My Account, or by fax at 1-866-765-8460 (in Canada and the U.S.) or 1-705-677-7712 (from anywhere else).
Where to get help with Form NR6
If you have questions about this form, please call 1-855-284-5946 (in Canada and the U.S.) or 613-940-8499 (from anywhere else).
Sources
[1] Form NR6 E (23), Undertaking to File an Income Tax Return by a Non-Resident Receiving Rent from Real or Immovable Property or Receiving a Timber Royalty, Canada Revenue Agency (the Official source link on this page).