
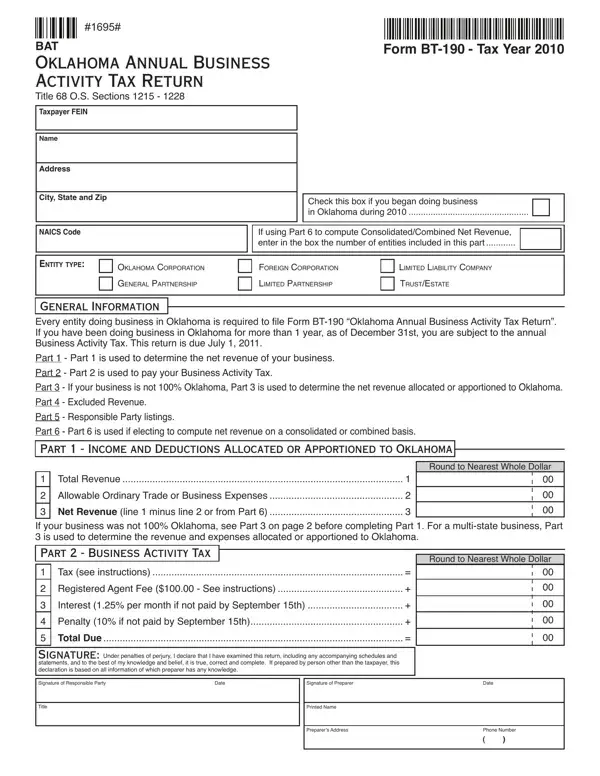
Form BT-190 at a glance
What it is: Form BT-190 is the Oklahoma Annual Business Activity Tax Return under Title 68 O.S. Sections 1215 - 1228.
Who signs: Signature: under penalties of perjury, sign on the Signature of Responsible Party line and enter the Date and the Title.
Every entity doing business in Oklahoma is required to file Form BT-190 “Oklahoma Annual Business Activity Tax Return”.
If you have been doing business in Oklahoma for more than 1 year, as of December 31st, you are subject to the annual Business Activity Tax.
All Corporations, Limited Liability Companies and Partnerships, regardless of length of time doing business in Oklahoma, must complete and file Form BT-190, and Business Trusts must also complete and file Form BT-190.
A filled-in Form BT-190 example: an Oklahoma corporation files its annual return
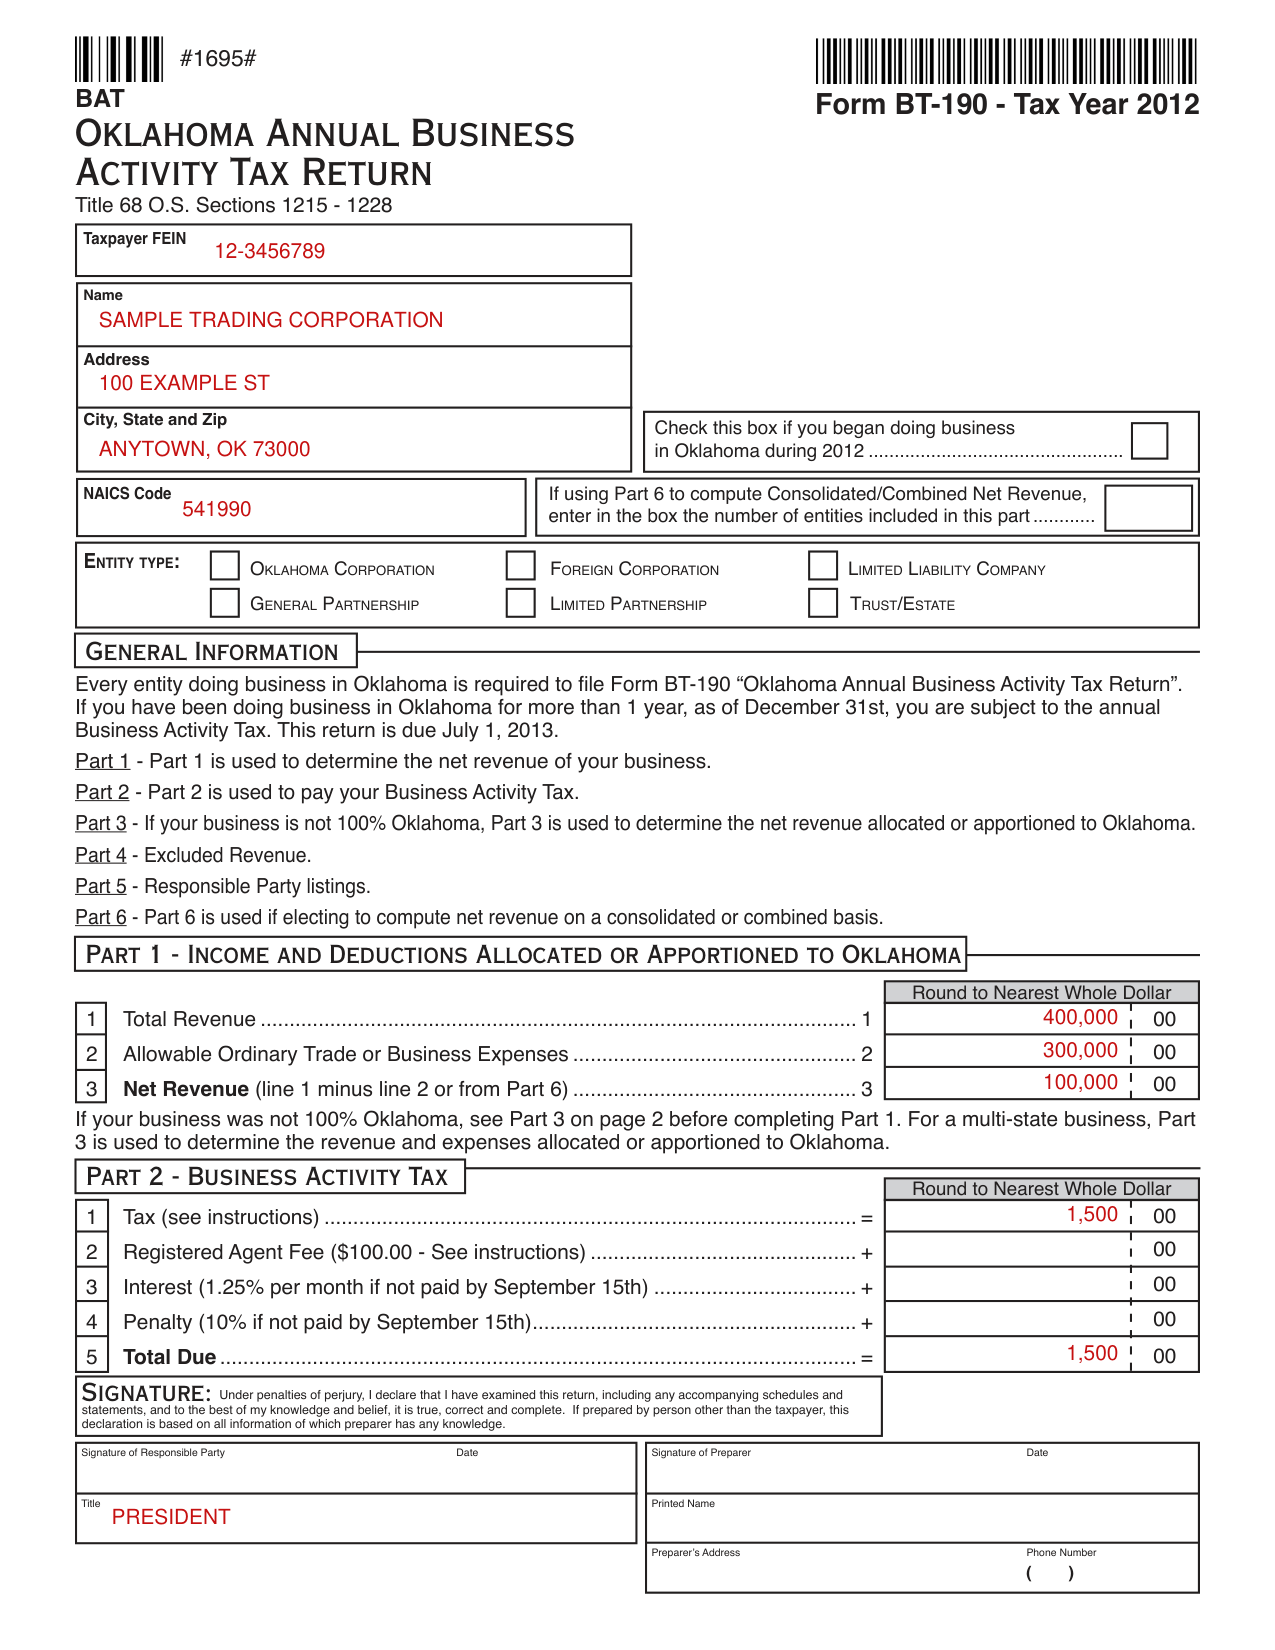
How to fill out Form BT-190, box by box
Taxpayer FEIN, Name, Address and NAICS Code
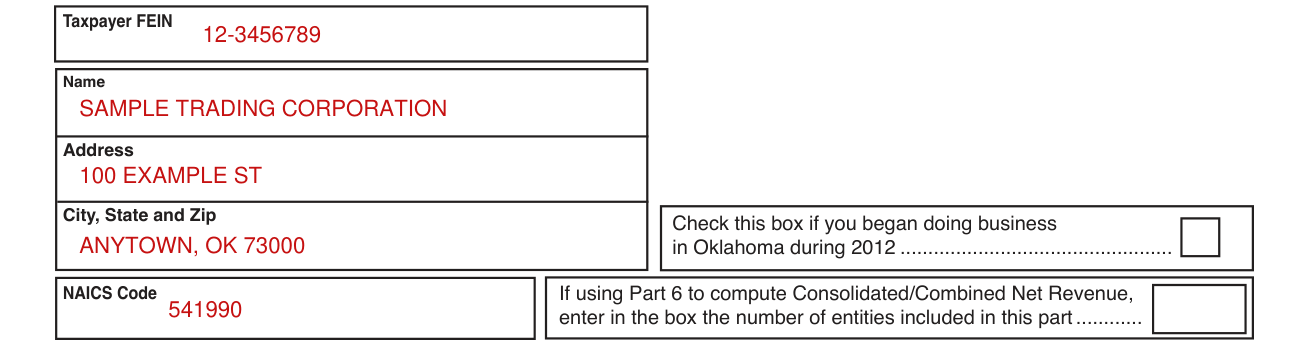
Enter the Taxpayer FEIN, Name, Address and City, State and Zip.
Enter the NAICS Code, the six digit code on your federal income tax return.
Check this box if you began doing business in Oklahoma during 2012

Check this box if you began doing business in Oklahoma during 2012.
Entities included in this part

If using Part 6 to compute Consolidated/Combined Net Revenue, enter in the box the number of entities included in this part.
Entity Type

Mark the ENTITY TYPE: Oklahoma Corporation, Foreign Corporation, Limited Liability Company, General Partnership, Limited Partnership or Trust/Estate.
Part 1 - Income and Deductions Allocated or Apportioned to Oklahoma
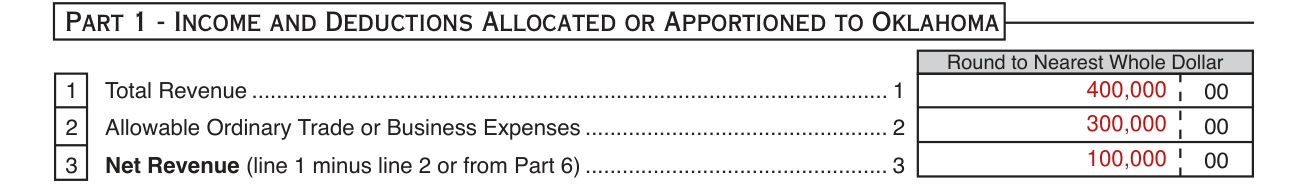
Part 1 is used to determine the net revenue of your business.
On Line 1 - Total Revenue, enter the gross income from your last filed Federal income tax return.
Excluded revenue must be reported in Part 4 - Excluded Revenue.
On Line 2 - Allowable Ordinary Trade or Business Expenses, enter all of the entity's ordinary trade or business expenses including cost of goods sold, and do not include interest expense, income taxes, depreciation or amortization.
Net Revenue (line 1 minus line 2 or from Part 6). If you are filing a consolidated/combined Business Activity Tax Return, Part 6 must be completed before Part 1.
For some business entities all of the business is in Oklahoma. If your business is conducted both within and without Oklahoma, refer to Part 3 to compute income and deductions.
Part 2 - Business Activity Tax
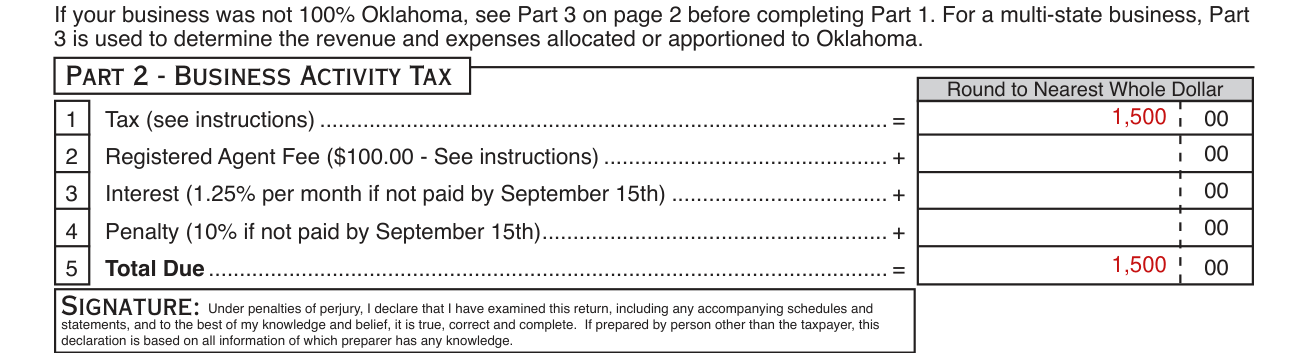
Part 2 is used to pay your Business Activity Tax.
On Line 1 - Tax, for most entities filing this form, the Business Activity Tax is equal to the Franchise Tax that was due and payable July 1, 2010 or $25 whichever is greater (checked November 8, 2026).
Entities not subject to Franchise tax have a Business Activity Tax of $25 (checked November 8, 2026). These entities include Limited Liability Companies, General Partnerships, Limited Partnerships and Business Trusts.
On Line 2 - Registered Agent Fee, foreign corporations must pay a $100 registered agent fee when submitting the Business Activity Tax Return (checked November 8, 2026).
If filing consolidated/combined (Part 6), pay $100 for each foreign corporation (checked November 8, 2026).
On Line 3 - Interest, if this return is postmarked after September 15th, the tax is subject to 1.25% interest per month from the due date until it is paid; multiply the amount in Part 2, line 1 by .0125 for each month the report is late.
On Line 4 - Penalty, if this return is postmarked after September 15th, the tax is subject to a penalty of 10%; multiply the amount in Part 2, line 1 by .10 to determine the penalty.
Line 5 is the Total Due.
Signature, Title, Printed Name and Phone Number
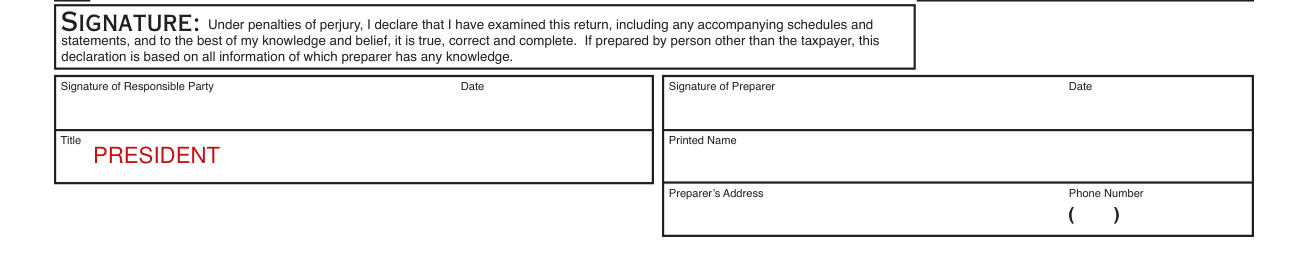
Signature: under penalties of perjury, sign on the Signature of Responsible Party line and enter the Date and the Title.
If prepared by a person other than the taxpayer, the preparer signs on the Signature of Preparer line with the Date, Printed Name, Preparer's Address and Phone Number, and this declaration is based on all information of which the preparer has any knowledge.
Part 3 - Multi-state Business
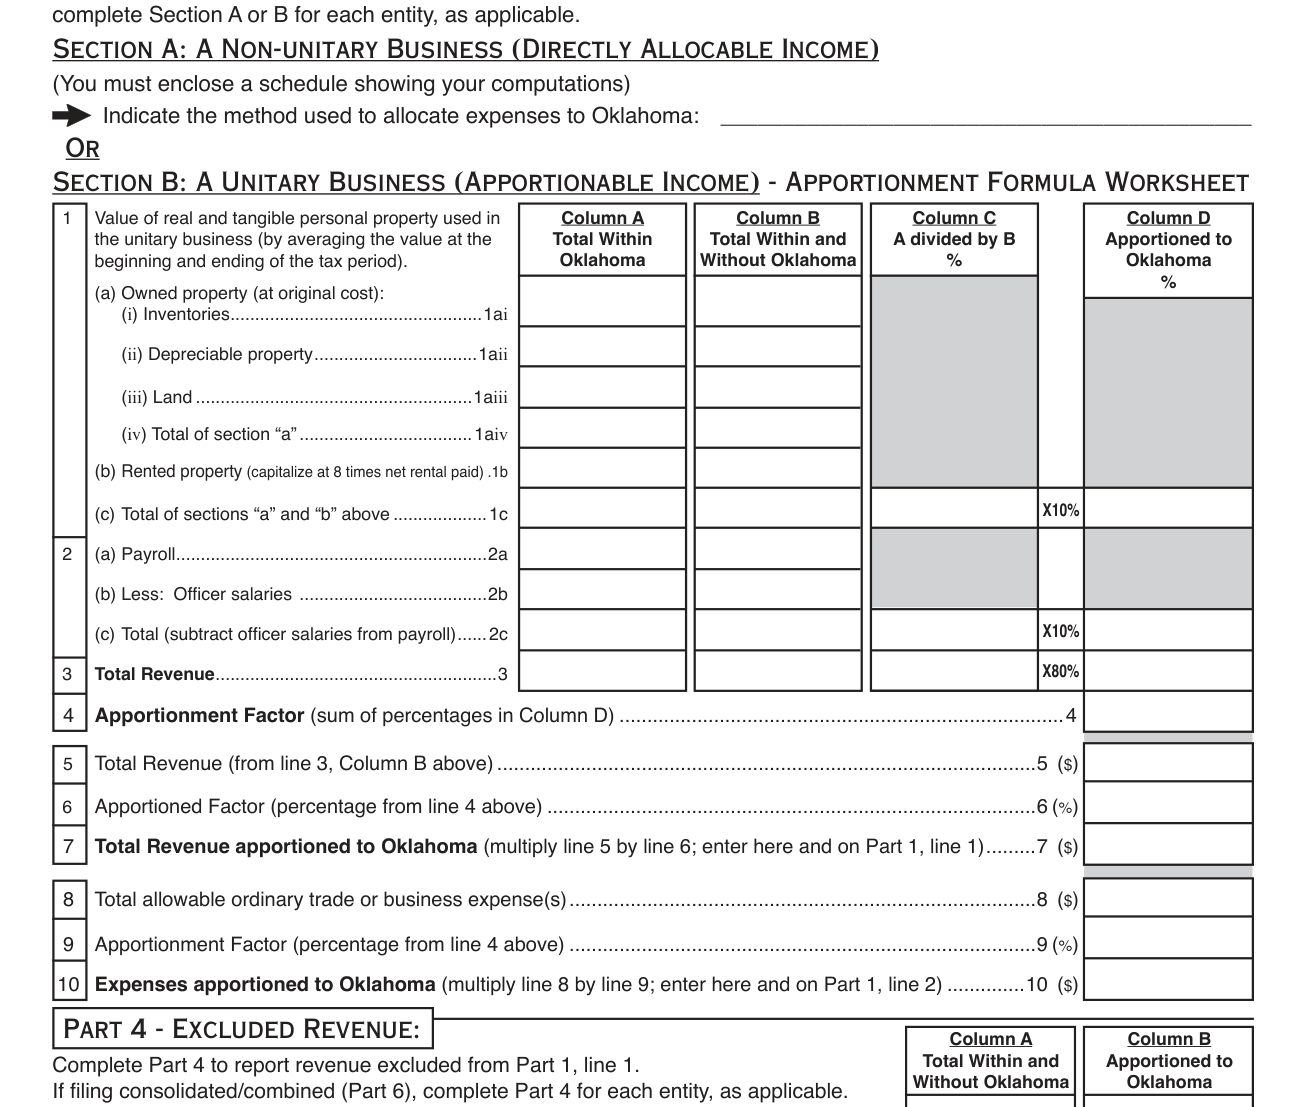
If your business is not 100% Oklahoma, Part 3 is used to determine the net revenue allocated or apportioned to Oklahoma.
Complete the appropriate Section, A or B, applicable to your multi-state business.
Section A: A Non-unitary Business (Directly Allocable Income): you must enclose a schedule showing your computations, and indicate the method used to allocate expenses to Oklahoma.
Section B: A Unitary Business (Apportionable Income) - Apportionment Formula Worksheet: if your business was conducted both within and without Oklahoma of a unitary character, complete Part 1 by entering the revenue and expenses apportioned to Oklahoma; to determine them, per 68 O.S. Section 1226, first complete the Apportionment Formula Worksheet to determine the apportionment factor.
Rented property is capitalized at 8 times net rental paid.
Part 4 - Excluded Revenue
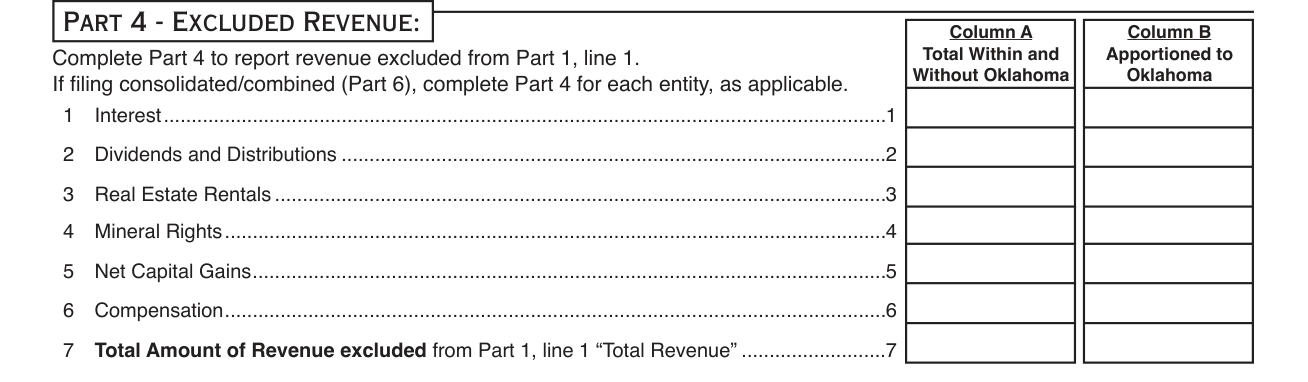
Complete Part 4 to report revenue excluded from Part 1, line 1.
Part 4 - Excluded Revenue Instructions: List separately each item of revenue not included in Part 1 “Total Revenue”.
If your business was 100% Oklahoma, enter the same amount in both columns. If your business was not 100% Oklahoma, enter the total amount of excludable revenue from your operations everywhere in Column A, multiply the amount reported in Column A by the apportionment factor from Part 3, line 4 and enter the result in the Oklahoma column (Column B).
Part 5 - Responsible Party Listings
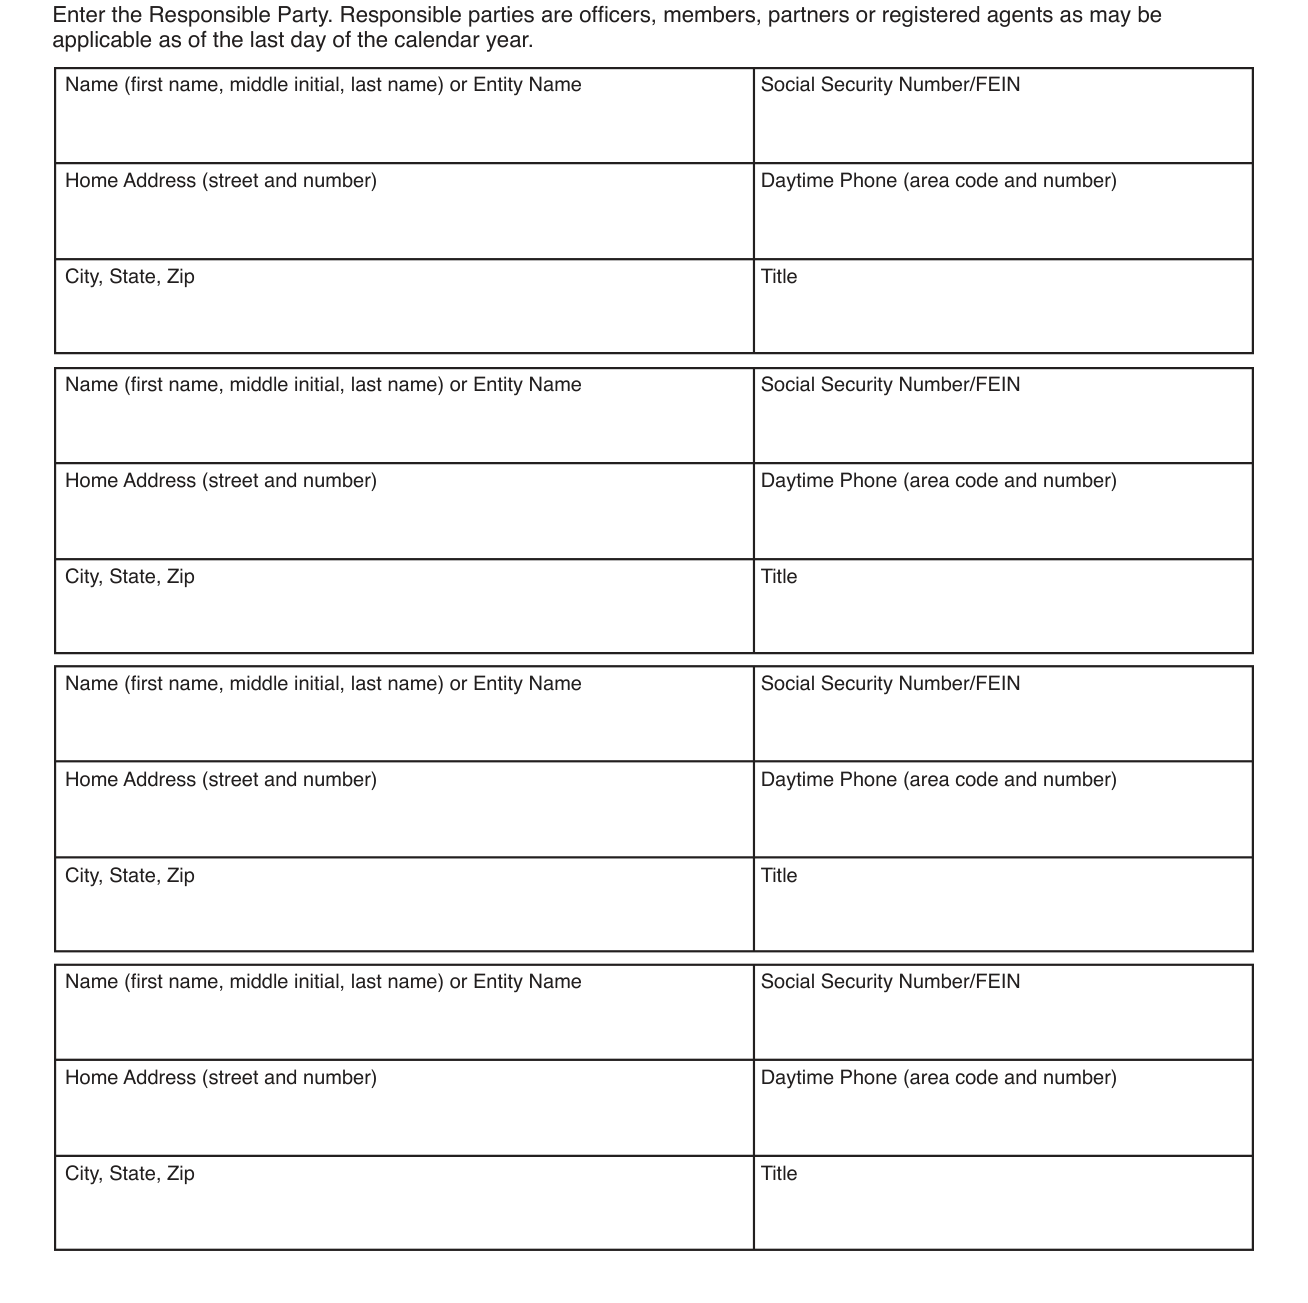
Enter the Responsible Party. Responsible parties are officers, members, partners or registered agents as may be applicable as of the last day of the calendar year.
For Corporations (Both C and Subchapter S), enter the current officers effective as of December 31, 2012, with name, title, address, phone number and Social Security Numbers/FEINs.
For Limited Liability Companies, enter all current members; for Partnerships, enter all current partners; for Business Trusts, enter all current trustees and beneficiaries, each effective as of December 31, 2012.
Please include Social Security Numbers of Responsible Parties. If non-resident officer with no Social Security Number (SSN) note “NRA” for SSN.
Part 6 - Computation of Oklahoma Consolidated/Combined Net Revenue
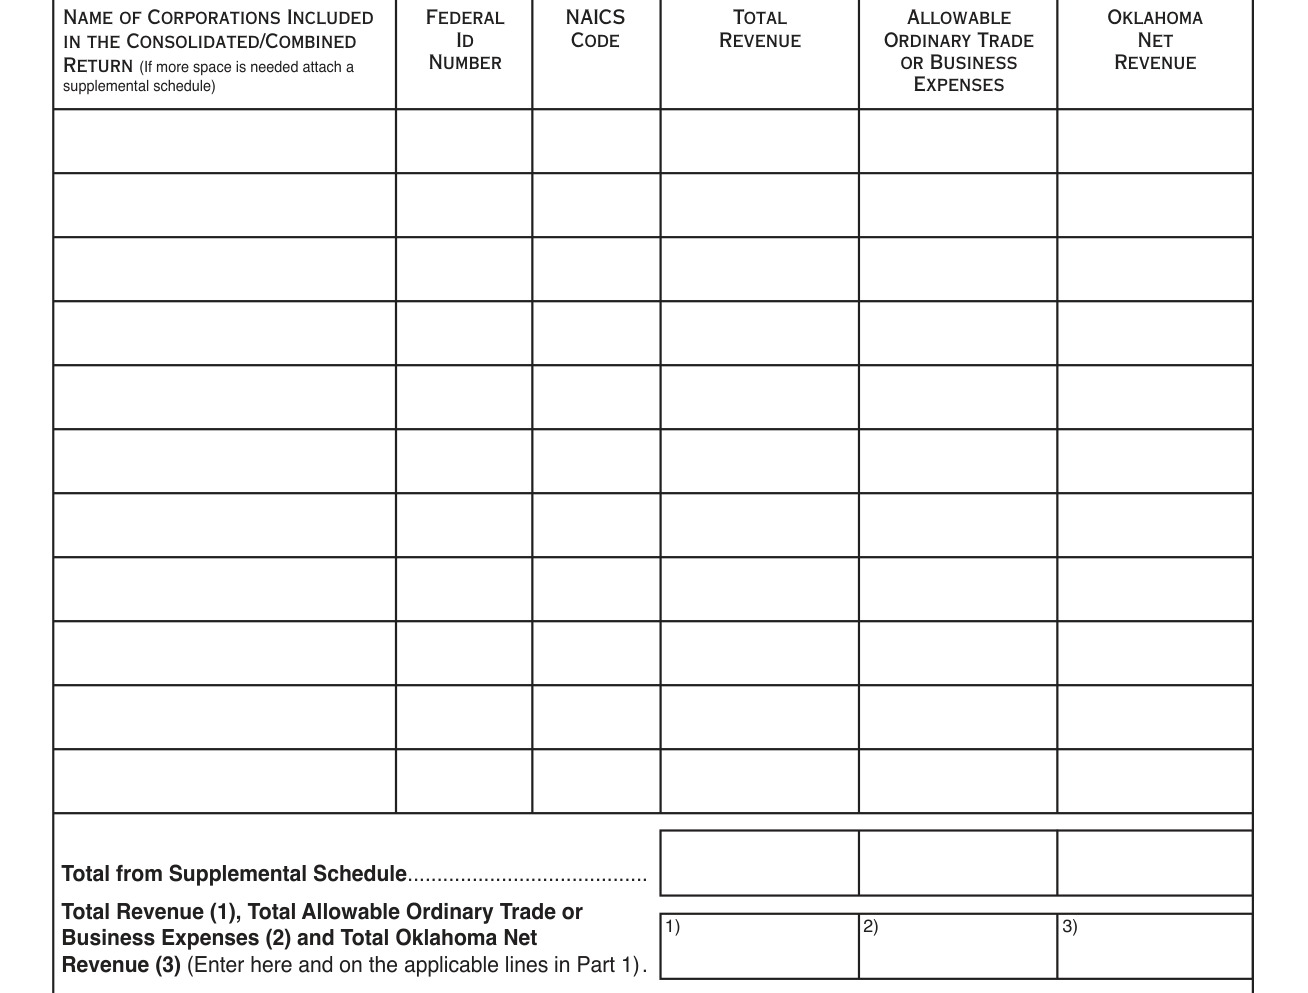
Enter Total Revenue (1), Total Allowable Ordinary Trade or Business Expenses (2) and Total Oklahoma Net Revenue (3) here and on the applicable lines in Part 1.
On Form BT-190 - Page 7, Part 6 - Computation of Oklahoma Consolidated/Combined Net Revenue: if two or more corporations file federal income tax returns on a consolidated basis, they are required to file a consolidated return for purposes of determining their net revenue subject to Oklahoma Business Activity Tax.
Each entity in the consolidated return must report their separate, Federal Identification Number and NAICS.
Name of Corporations Included in the Consolidated/Combined Return: if more space is needed attach a supplemental schedule.
Common questions about Form BT-190
Is there a deadline?
This return must be filed by July 1, 2013.
Where do I file it?
Mail completed Form BT-190 to: Oklahoma Tax Commission Post Office Box 26930 Oklahoma City, OK 73126-0930.
Sources
[1] Form BT-190 (Tax Year 2012), Oklahoma Annual Business Activity Tax Return, Oklahoma Tax Commission (the Official source link on this page).