
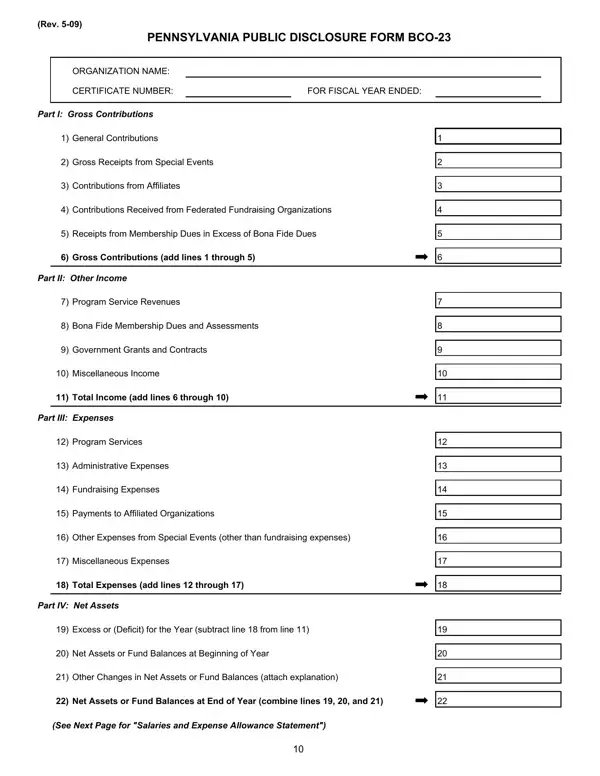
Form BCO-23 at a glance
What it is: Pennsylvania Public Disclosure Form BCO-23 has Part I: Gross Contributions, Part II: Other Income, Part III: Expenses and Part IV: Net Assets.
In the instructions (Rev. 5-09), an organization which is not required to file an IRS 990 Return must file a BCO-23 Form.
An organization that files a 990N, 990EZ, or 990PF, or an affiliate whose parent organization files a 990 group return must file a BCO-23 Form in addition to filing a copy of the organization's IRS 990 Return.
What to bring and attach to Form BCO-23
On line 21, Other Changes in Net Assets or Fund Balances, attach a schedule explaining any changes in net assets or fund balances between the beginning and end of the year that were not accounted for by the amount on line 19.
A filled-in Form BCO-23 example: a small nonprofit fills out the form
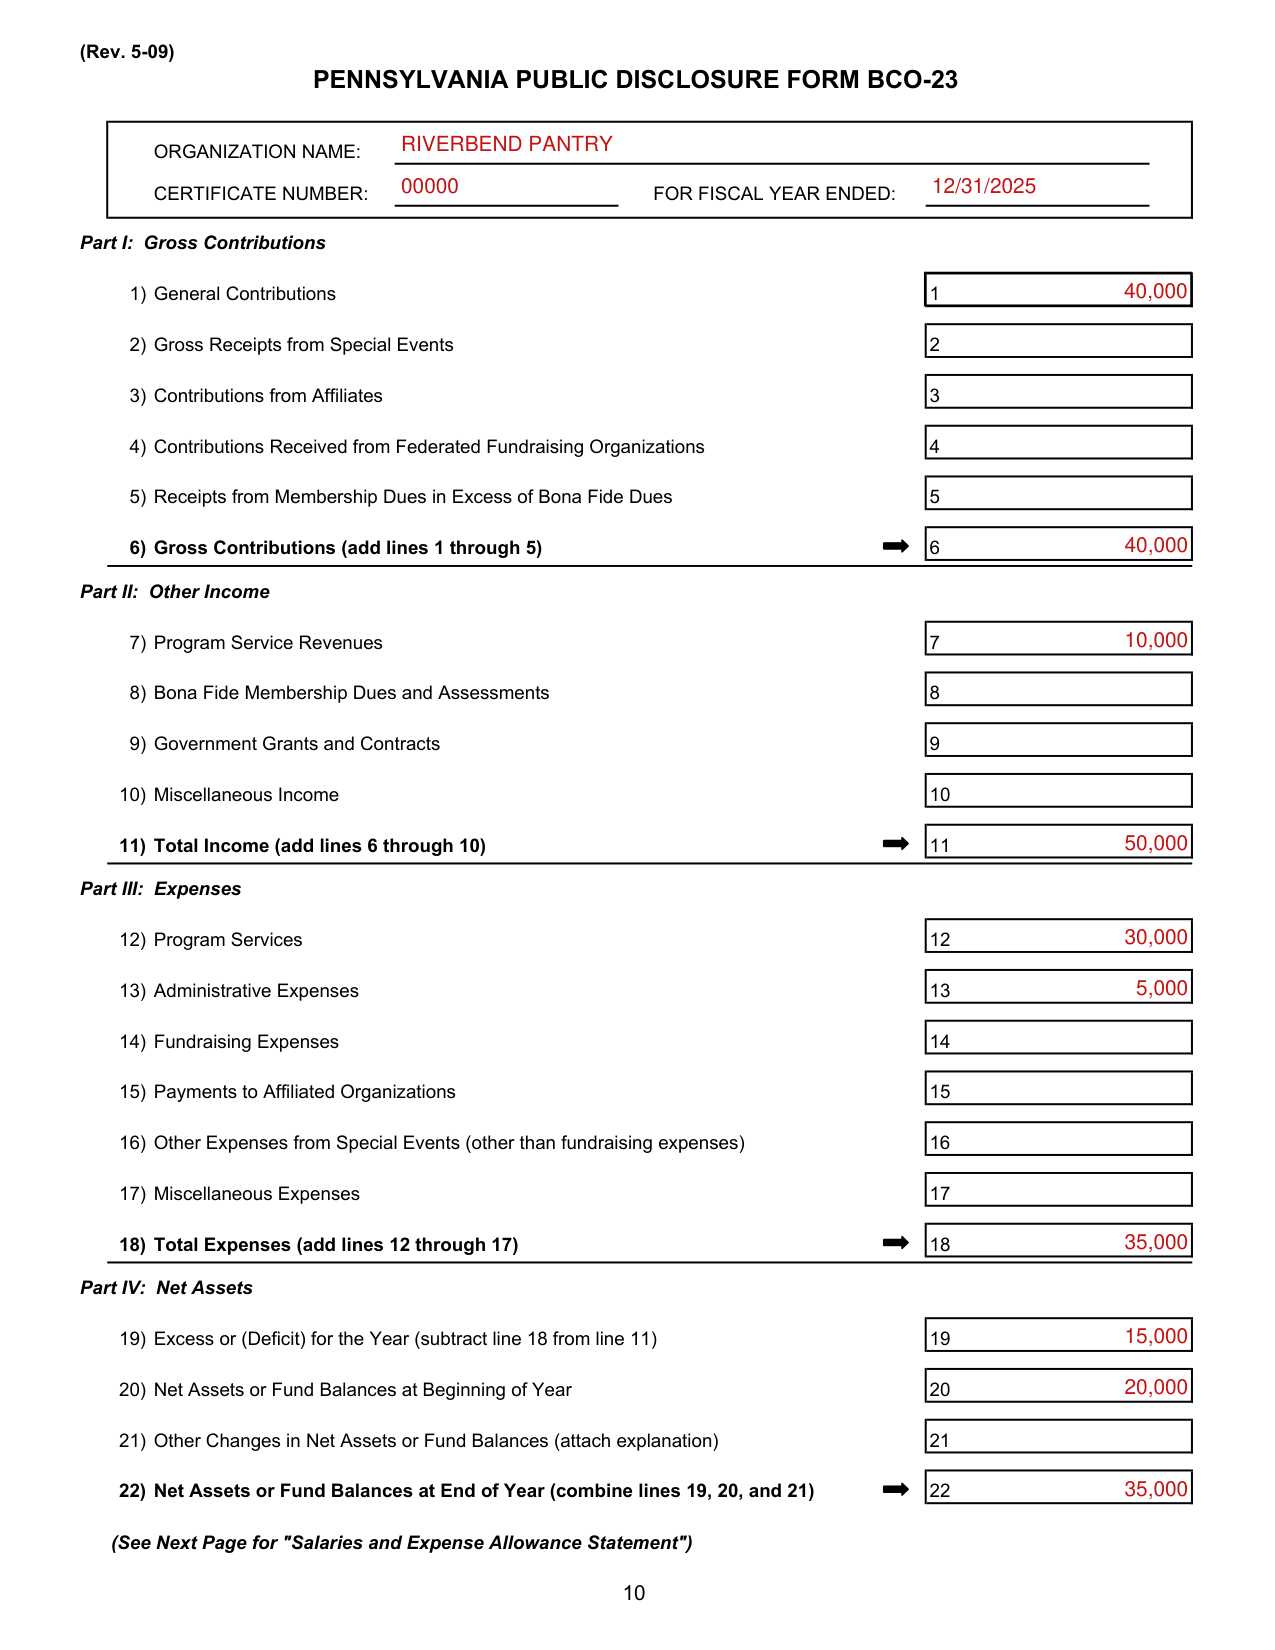
How to fill out Form BCO-23, box by box
Organization name, certificate number and fiscal year

Fill in ORGANIZATION NAME, CERTIFICATE NUMBER and FOR FISCAL YEAR ENDED.
Part I: Gross Contributions
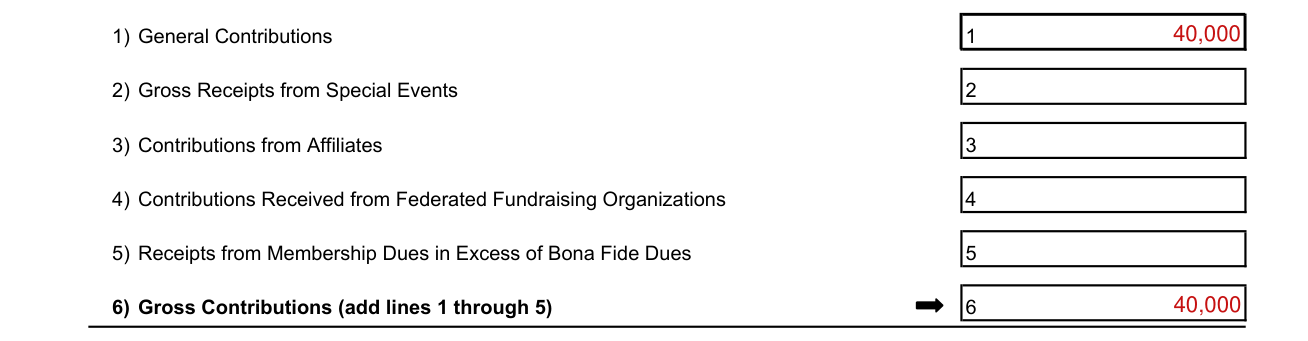
On line 1, General Contributions, enter the total gross contributions, gifts, grants and similar amounts received, including contributions from individuals, commercial co-ventures, corporations and other businesses, foundations, public charities, exempt organizations (do not include amounts received from fundraising organizations or affiliates), trusts, and estates. Noncash items should be valued at their fair market values on the date of their contribution to the organization. Exclude government grants and contracts.
On line 2, Gross Receipts from Special Events, enter the total gross amounts received from all special events and activities conducted by the organization, or on its behalf. Do not reduce the total gross amounts received by any expenses related to the events or activities. These expenses should be included on lines 14 or 16.
On line 3, Contributions from Affiliates, enter the total contributions received from associated organizations such as affiliates, national organizations, or parent organizations.
On line 4, Contributions Received from Federated Fundraising Organizations, enter the total contributions received from fundraising organizations such as United Way, United Fund, and Community Chests.
On line 5, Receipts from Membership Dues in Excess of Bona Fide Dues, include only those dues that represent contributions from the public; dues are considered to be contributions to the extent that they exceed the monetary value of the benefits available to the member.
On line 6, Gross Contributions, add lines 1 through 5.
Part II: Other Income
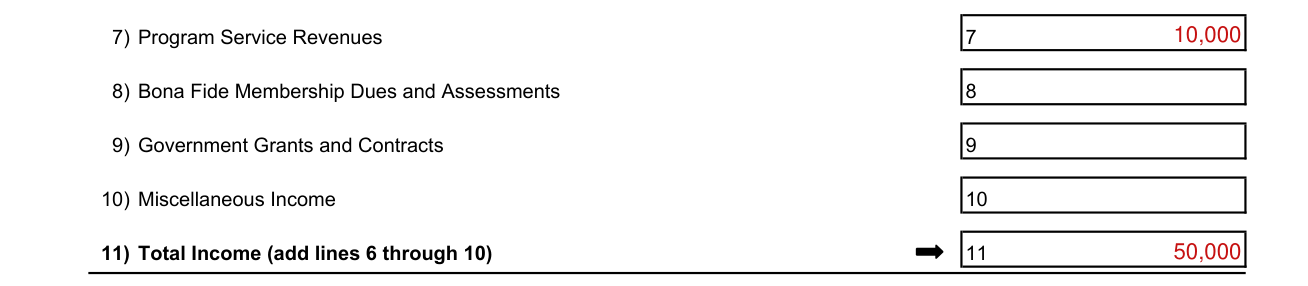
On line 7, Program Service Revenues, enter the gross amount of fees and revenues earned by the organization for providing services or performing activities that fulfill the organization's stated mission or purpose. Do not include any amounts received from a government agency that are used to serve the needs of the general public. These amounts should be included on line 9.
On line 8, Bona Fide Membership Dues and Assessments, include only those dues and assessments received that do not exceed the monetary value of the benefits available to the member.
On line 9, Government Grants and Contracts, include total grants or other payments received from a federal, state, or local governmental unit if its primary purpose is to enable the organization to provide a service, product, or maintain a facility for the primary benefit of the general public. Do not include any amounts received that are used to serve the needs of the governmental agency. These amounts should be included on line 7.
On line 10, Miscellaneous Income, the figure represents the total income from all sources not covered by lines 1 through 5 and lines 7 through 9, including, but not limited to, interest, dividends and interest from securities, gross rental income, gross amounts from the sale of assets other than inventory, and gross sales of inventory (this does not include items that were sold through a special event or activity).
On line 11, Total Income, add lines 6 through 10.
Part III: Expenses
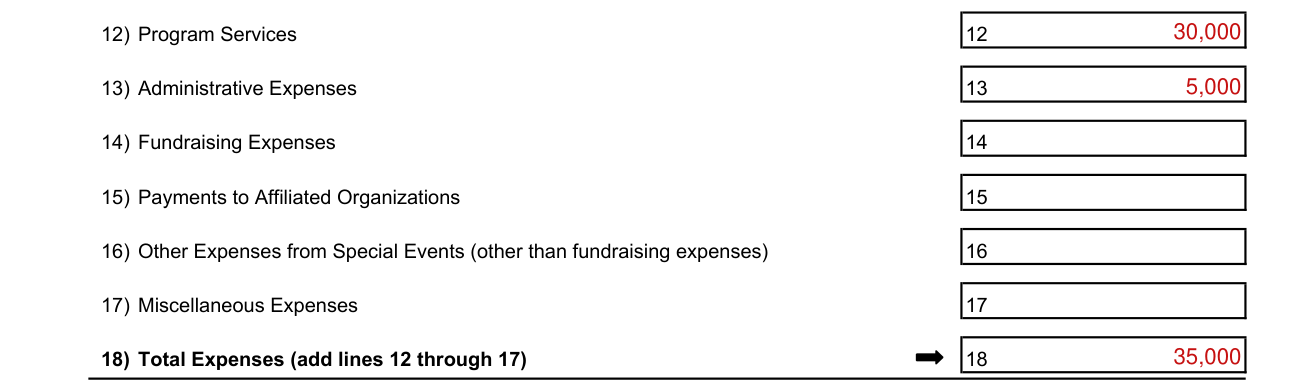
On line 12, Program Services, include total costs of services or activities performed by the organization that fulfill its charitable purposes.
On line 13, Administrative Expenses, include costs related to the overall administration and management of the organization; if a portion of these costs relate to program services or fundraising, a reasonable allocation should be made among the applicable functions.
On line 14, Fundraising Expenses, include costs incurred in soliciting contributions, gifts, grants, and similar amounts. Do not include expenses directly attributable to furnishing the goods or services sold at a special event. These expenses should be included on line 16.
On line 16, Other Expenses from Special Events (other than fundraising expenses), include only those expenses directly attributable to the goods or services the buyer received from a special event. Do not include fundraising expenses related to the organization's special events. These expenses should be included on line 14.
On line 17, Miscellaneous Expenses, include expenses that are not reportable on lines 12 thru 16, including all expenses that are attributable to the income reported on line 10.
On line 18, Total Expenses, add lines 12 through 17.
Part IV: Net Assets
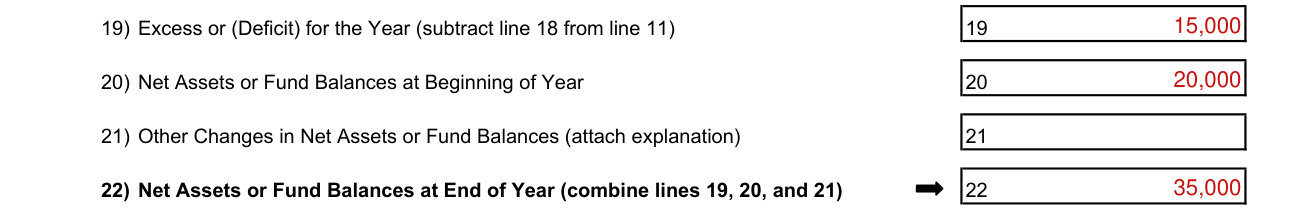
On line 19, Excess or (Deficit) for the Year, enter the difference between lines 11 and 18. If line 18 is greater than line 11, enter the difference in parentheses.
On line 20, Net Assets or Fund Balances at Beginning of Year, organizations using fund accounting should report the total sum of the various fund balances at the beginning of the reporting year. Organizations not using fund accounting should report their net assets, which is the difference between total assets and total liabilities. These amounts should agree with the ending fund balance of the prior fiscal year.
On line 22, Net Assets or Fund Balances at End of Year, combine lines 19, 20, and 21.
Salaries and Expense Allowance Statement
SALARIES AND EXPENSE ALLOWANCE STATEMENT: report salaries paid and expenses allowed to the five highest paid employees.
Additionally, include salaries paid and expenses allowed to any and all compensated officers of the organization.
Sources
[1] Pennsylvania Public Disclosure Form BCO-23 (Rev. 5-09), Pennsylvania Department of State (the Official source link on this page).