

PA Schedule W-2S at a glance
What it is: PA Schedule W-2S, the Wage Statement Summary, is a Summary of PA-Taxable Employee, Non-employee and Miscellaneous Compensation.
Where and when to file: PA-40 Schedule W-2S must be completed and included with an originally filed PA-40 for any taxpayer(s) reporting gross compensation on Line 1a of the PA-40. PA-40 Schedule W-2S must also be completed to record any distributions reported on federal Form 1099-R, whether the distribution is taxable or nontaxable for Pennsylvania personal income tax purposes.
Use PA-40 Schedule W-2S to report compensation received from employment, miscellaneous non-employee compensation and taxable distributions from retirement plans.
A filled-in PA Schedule W-2S example: one employer's Form W-2 on the schedule
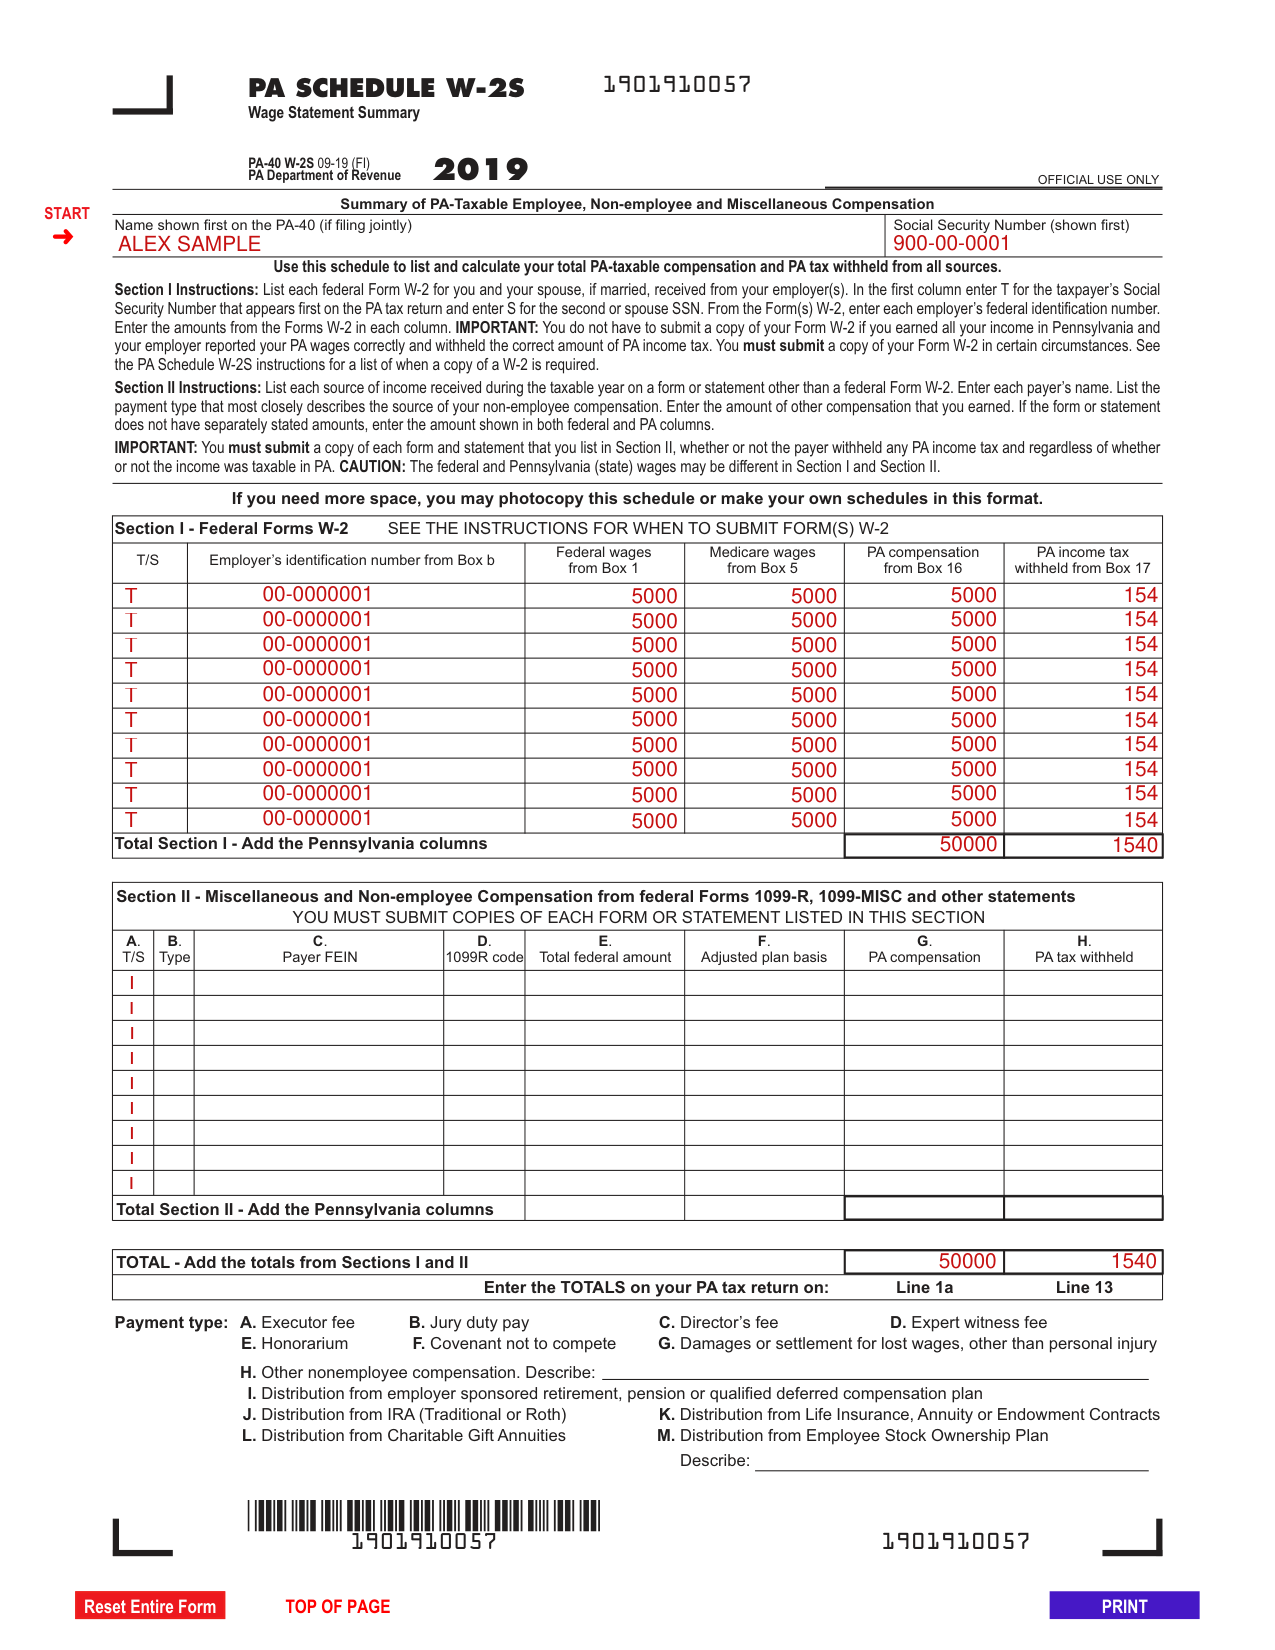
How to fill out PA Schedule W-2S, box by box
Name and Social Security number

Enter the name of the taxpayer. If a jointly filed return, enter the name of the primary taxpayer (name shown first on the PA-40, Personal Income Tax Return).
Enter the Social Security number (SSN) of the taxpayer. If a jointly filed return, enter the primary taxpayer's SSN.
Section I - Federal Forms W-2
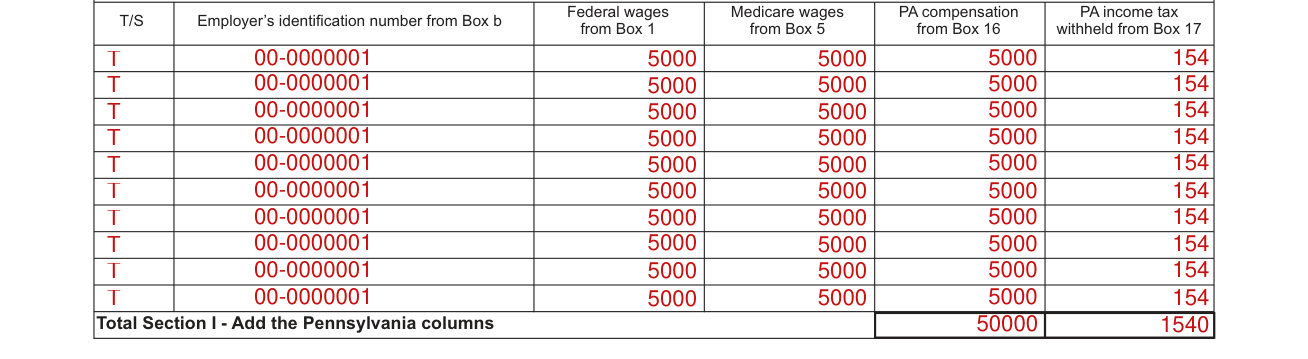
Use Section I of PA-40 Schedule W-2S to report Pennsylvania-taxable compensation from federal Form(s) W-2 as well as to record amounts from Form W-2 not taxable for Pennsylvania personal income tax purposes. Include a statement explaining why any amounts are not Pennsylvania-taxable compensation.
List each federal Form W-2 for the taxpayer and/or spouse, if married, received from each employer.
Enter a T to report the income from all Forms W-2 for the taxpayer whose SSN appears first on the PA-40, Personal Income Tax Return. Enter an S for all Forms W-2 for the spouse.
Enter the federal employer identification number (FEIN) from Box B of the W-2 for each employer.
Enter the amount of federal wages from Box 1 of the W-2 for each employer.
Enter the amount of Medicare wages from Box 5 of the W-2 for each employer.
Enter the Pennsylvania compensation from Box 16 of the W-2 for each employer.
CAUTION: If Box 15 of the W-2 does not indicate PA as the state, the compensation reported by the employer in Box 16 may be required to be adjusted to conform to Pennsylvania's rules.
Enter the amount of Pennsylvania income tax withheld from Box 17 of the W-2 for each employer.
Add the amounts of PA compensation and PA income tax withheld and enter the results.
Section II - Non-employee compensation
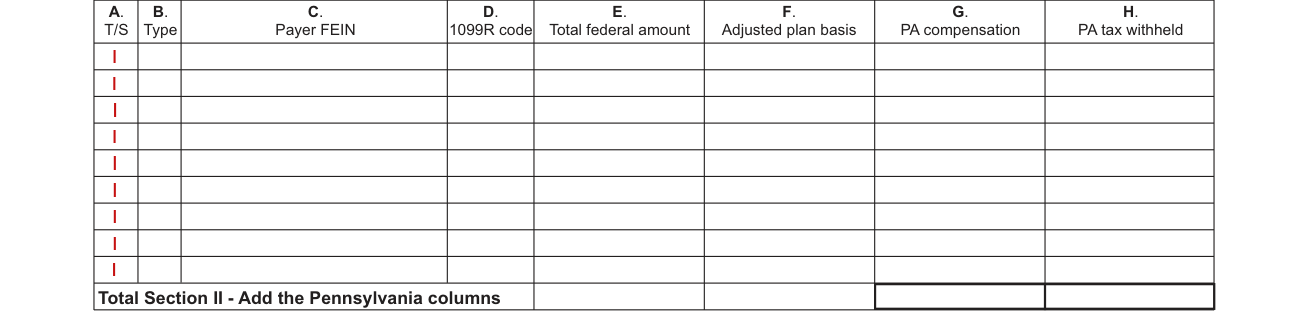
List each source of income received during the taxable year on a form or statement other than a federal Form W-2.
Enter a T if the payment or distribution was to the primary taxpayer shown first on the PA-40, or enter S if the payment or distribution was to the spouse.
Enter the letter designation for the type of payment(s) from the following list: A Executor fee; B Jury duty pay; C Director's fee; D Expert witness fee; E Honorarium; F Covenant not to compete; G Damages or settlement for lost wages other than personal injury; H Other non-employee compensation (enter description in space provided); I Distribution from employer sponsored retirement, pension, or qualified deferred compensation plan; J Distribution from IRA (Traditional or Roth); K Distribution from life insurance, annuity or endowment contracts; L Distribution from charitable gift annuities; and/or M Distribution from employee stock ownership plan (enter description in space provided).
Enter the payers' federal employer identification number (FEIN).
If the payment being reported is from a federal Form 1099-R, enter the distribution code(s) listed in Box 7 of the 1099-R.
Enter the total amount of the payment from a federal Form 1099-MISC or from another document and/or any distribution from federal Form 1099-R Box 1.
If the distribution code in Column D is 1, 2, J, L, S or U from the 1099-R, enter the amount of the adjusted basis in the plan.
If the distribution code in Column D is 1, 2, 8, 9, J, L, S or U from the 1099-R, subtract the amount in Column F from Column E and enter the resulting amount (but not less than zero) here. If any other 1099-R code was entered in Column D, enter a zero in Column G (there is no PA-taxable compensation from these codes). If a payment from a 1099-MISC or from another document other than a 1099-R was entered, enter the amount from Column E.
If the payer withheld PA state income tax from the distribution or payment, enter the amount withheld from that distribution or payment.
Add the amounts for Columns G and H and enter the results.
TOTAL - Add the totals from Sections I and II

Add the amounts from PA compensation and PA tax withheld from the Total Section I and Total Section II lines and enter the results here and on Lines 1a and 13 of the PA-40, Personal Income Tax Return.
If your situation is different
You attach copies of Form W-2
An actual state copy or a legible photocopy of each state copy of Form W-2 and/or a written explanation of the amount of compensation reported should be submitted with the PA-40, Personal Income Tax Return, if: 1. The PA compensation entered on Line 1a of the PA-40, Personal Income Tax Return, is not the same as Box 16 on Form W-2 (when the amount of Pennsylvania compensation or withholding is believed to be incorrect). 2. The employer provided a handwritten Form W-2. 3. The employer reported an incorrect amount on Form W-2. A written statement from the employer must also be included. 4. The employer withheld PA income tax from wages at a rate that is more than the current year's tax rate of 3.07 percent. 5. PA income tax was withheld by an employer for a resident of a reciprocal compensation agreement state. 6. The Medicare wages in Box 5 on Form W-2 are greater than PA wages in Box 16. In this case, complete and include the PA-40 W-2 Reconciliation Worksheet with the PA-40, Personal Income Tax Return. 7. A PA resident is working in another state or country and did not have PA income tax withheld by the employer. 8. A distribution from a nonqualified deferred compensation plan is included in Box 1 of Form W-2. 9. Form W-2 shows income earned or tax withheld for another state.
You attach copies of Form 1099-R or 1099-MISC
When to submit Form(s) 1099-R: copies of Form 1099-R, Distributions from Pensions, Annuities, Retirement or Profit-Sharing Plans, IRAs, Insurance Contracts, etc., must be included with paper and e-filed PA-40, Personal Income Tax Returns, regardless of whether the 1099-R includes PA income tax withheld or whether or not the distribution amount is taxable. For electronically filed returns, copies of the 1099-R are not required to be included if the 1099-R includes federal tax withheld. If the 1099-R does not include federal tax withheld, a copy of the 1099-R must be provided with the filing of the PA-40, Personal Income Tax Return. Any 1099-R that includes PA income tax withheld must be provided to the department even if the form includes federal withholding.
Copies of Form 1099-MISC, Miscellaneous Income, must also be included with paper and e-filed PA-40, Personal Income Tax Returns, if the income is reported in Section II of PA-40 Schedule W-2S. Do not include Form 1099-MISC for income reported on PA-40 Schedules C, E or F unless the form includes PA income tax withheld.
You file on paper
For paper filed PA-40, Personal Income Tax Returns, submit a photocopy (8 ½ x 11 sheet) of the form(s) W-2, 1099-R and/or 1099-MISC as required.
You e-file
For e-filed returns Form(s) W-2, 1099-R and/or 1099-MISC may be submitted as required using one of the following methods: 1. PDF file, attaching a PDF file to the return when filed, if the software allows these attachments; 2. Fax, using the DEX-93 as the cover sheet and faxing the document(s) to 717-772-4193; 3. Email, attaching a PDF file of the document(s) to an email to RA-BITPITELFCORFAXES@PA.GOV using the DEX-93 as a cover sheet and following the email rules on the DEX-93; or 4. U.S. Postal Service, mailing the information to the department at: PA DEPARTMENT OF REVENUE ELECTRONIC FILING SECTION P.O. BOX 280507 HARRISBURG PA 17128-0507.
You converted a traditional IRA to a Roth IRA or vice versa
A taxpayer with a conversion of a traditional IRA to a Roth IRA (or vice versa) with distribution code 1 in Box 7 of the 1099-R may be eligible to report the amount as nontaxable income when a direct transfer from trustee to trustee occurs and/or when the entire distribution from the original IRA account (including taxes withheld) is paid into the new IRA account within 60 days of the date of the distribution. In such cases, input the same amount in Column F as reported in Column E.
Before you go
The department does not require submission of a copy of Form W-2 in all instances. A copy of Form W-2 is not required to be submitted when all the compensation income was earned in Pennsylvania and the employer reported the Pennsylvania wages correctly and withheld the correct amount of Pennsylvania personal income tax.
IMPORTANT: A copy of each form and statement for amounts listed in Section II must be submitted with the PA-40, Personal Income Tax Return, whether or not the payer withheld any PA income tax and regardless of whether or not the income was taxable in PA.
Show money amounts in whole-dollars only.
Sources
[1] PA-40 Schedule W-2S, Wage Statement Summary (2019), Pennsylvania Department of Revenue (the Official source link on this page).
