

PRP Section 4400 at a glance
What it is: PRP Section 4400 is the Quality Control Policies and Procedures Documentation Questionnaire for Firms With Two or More Personnel.
This questionnaire has been developed for firms with two or more personnel.
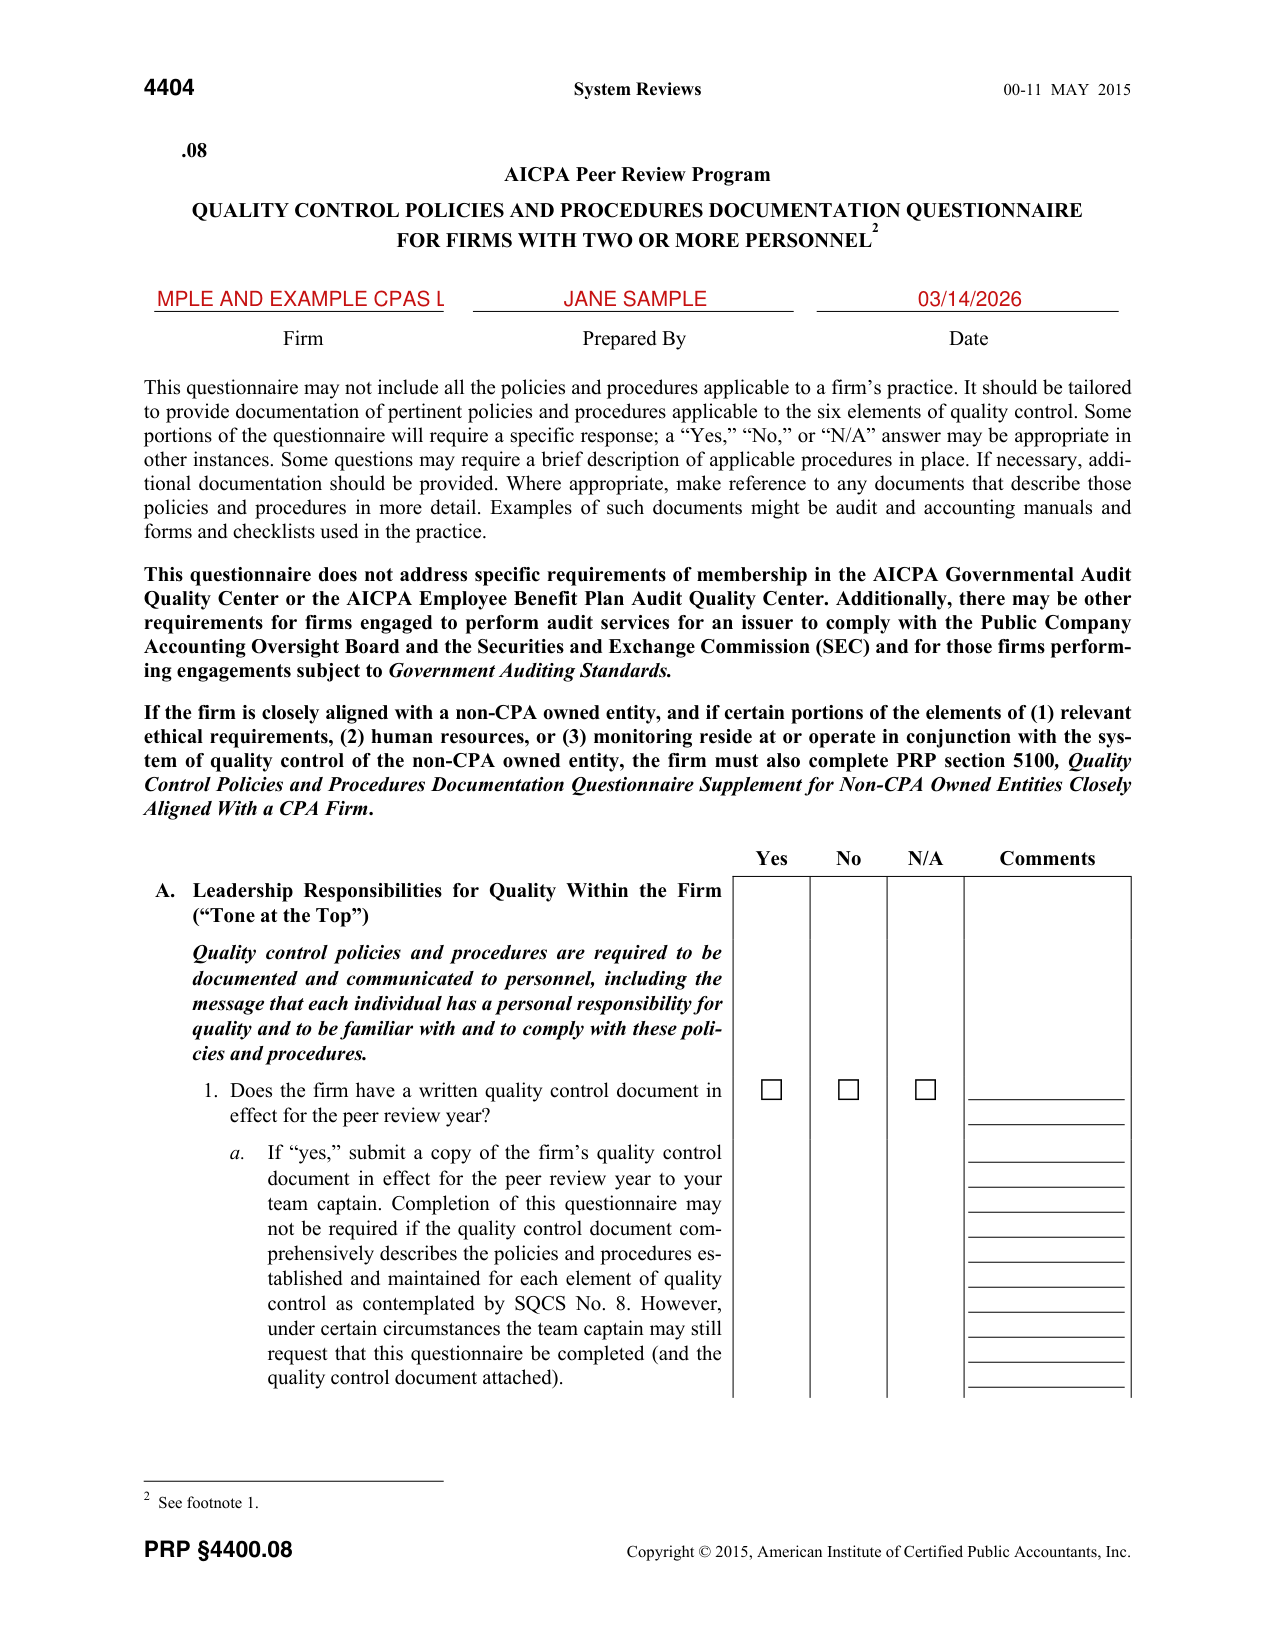
A filled-in PRP Section 4400 example: a three-person firm starts the questionnaire
How to fill out PRP Section 4400, box by box
Firm, Prepared By and Date
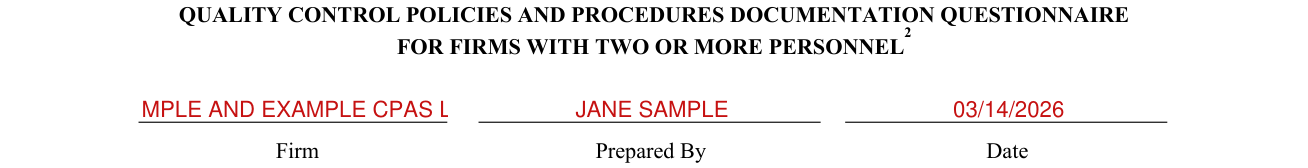
Fill in Firm, Prepared By and Date.
More rules for PRP Section 4400
The six elements of quality control are: Leadership Responsibilities for Quality Within the Firm (the “Tone at the Top”), Relevant Ethical Requirements, Acceptance and Continuance of Client Relationships and Specific Engagements, Human Resources, Engagement Performance and Monitoring.
It should be tailored to provide documentation of pertinent policies and procedures applicable to the six elements of quality control.
This questionnaire may not include all the policies and procedures applicable to a firm's practice.
Some portions of the questionnaire will require a specific response; a “Yes,” “No,” or “N/A” answer may be appropriate in other instances.
A “No” answer to a question does not necessarily indicate a problem with the firm's system of quality control; however, it may require additional explanation of applicable procedures that the firm has implemented in the circumstances.
When determining the extent of documentation required for this questionnaire, the reviewed firm should consider that “Yes” and “No” answers may assist in identifying the control objective, but it would not typically satisfy the required documentation of how the control was met.
The reviewed firm should document the control objective and the details of the policies and procedures.
Some questions may require a brief description of applicable procedures in place.
If necessary, additional documentation should be provided.
Where appropriate, make reference to any documents that describe those policies and procedures in more detail.
SQCS No. 8 requires a firm to communicate and document its quality control policies and procedures. The extent of the documentation is based on the size, structure and nature of the firm's practice.
This questionnaire does not address specific requirements of membership in the AICPA Governmental Audit Quality Center or the AICPA Employee Benefit Plan Audit Quality Center.
If your situation is different
The firm has a written quality control document
If “yes,” submit a copy of the firm's quality control document in effect for the peer review year to your team captain.
Completion of this questionnaire may not be required if the quality control document comprehensively describes the policies and procedures established and maintained for each element of quality control as contemplated by SQCS No. 8.
Firms that have developed a comprehensive quality control document (as contemplated by SQCS No. 8) that was effective for the peer review year should provide that document to the peer reviewer.
However, under certain circumstances, the team captain may still request that a firm complete this questionnaire (and attach the quality control document).
For instance, this could be requested if the team captain's consideration of the firm's quality control document indicates that it may not adequately address all the required elements of a system of quality control in a level of detail appropriate to the firm.
The questionnaire is the firm's primary documentation
If “no,” will this questionnaire provide the primary documentation of the firm's policies and procedures for its system of quality control?
If “yes,” indicate date of adoption (cannot be prior to the date of completion of this questionnaire).
If this questionnaire was not in effect for the peer review year, the firm should also attach previously completed questionnaire(s) that were effective for the peer review year, which could be the questionnaire completed for the firm's last peer review.
The firm is closely aligned with a non-CPA owned entity
If the firm is closely aligned with a non-CPA owned entity, and if certain portions of the elements of (1) relevant ethical requirements, (2) human resources, or (3) monitoring reside at or operate in conjunction with the system of quality control of the non-CPA owned entity, the firm must also complete PRP section 5100, Quality Control Policies and Procedures Documentation Questionnaire Supplement for Non-CPA Owned Entities Closely Aligned With a CPA Firm.
You are a sole practitioner with no personnel
Section 4300, Quality Control Policies and Procedures Documentation for a Sole Practitioner With No Personnel, is a questionnaire that has been developed for sole practitioners with no personnel.
Sources
[1] PRP Section 4400, Quality Control Policies and Procedures Documentation Questionnaire for Firms With Two or More Personnel (MAY 2015), AICPA Peer Review Program Manual (the Official source link on this page).