
Form RPD-41326 at a glance
What it is: Form RPD-41326 is the Rural Health Care Practitioner Tax Credit Claim Form for a taxpayer who is not a dependent and may claim a credit against personal income tax liability.
Who signs: Sign as Signature of Taxpayer or Agent, then enter the Title and the Date.
A taxpayer who files a New Mexico personal income tax return, who is not a dependent of another individual, who is an eligible health care practitioner and who has provided health care services in New Mexico in a rural health care underserved area in a tax year, may claim a credit against personal income tax liability.
A filled-in Form RPD-41326 example: a pharmacist claims the credit
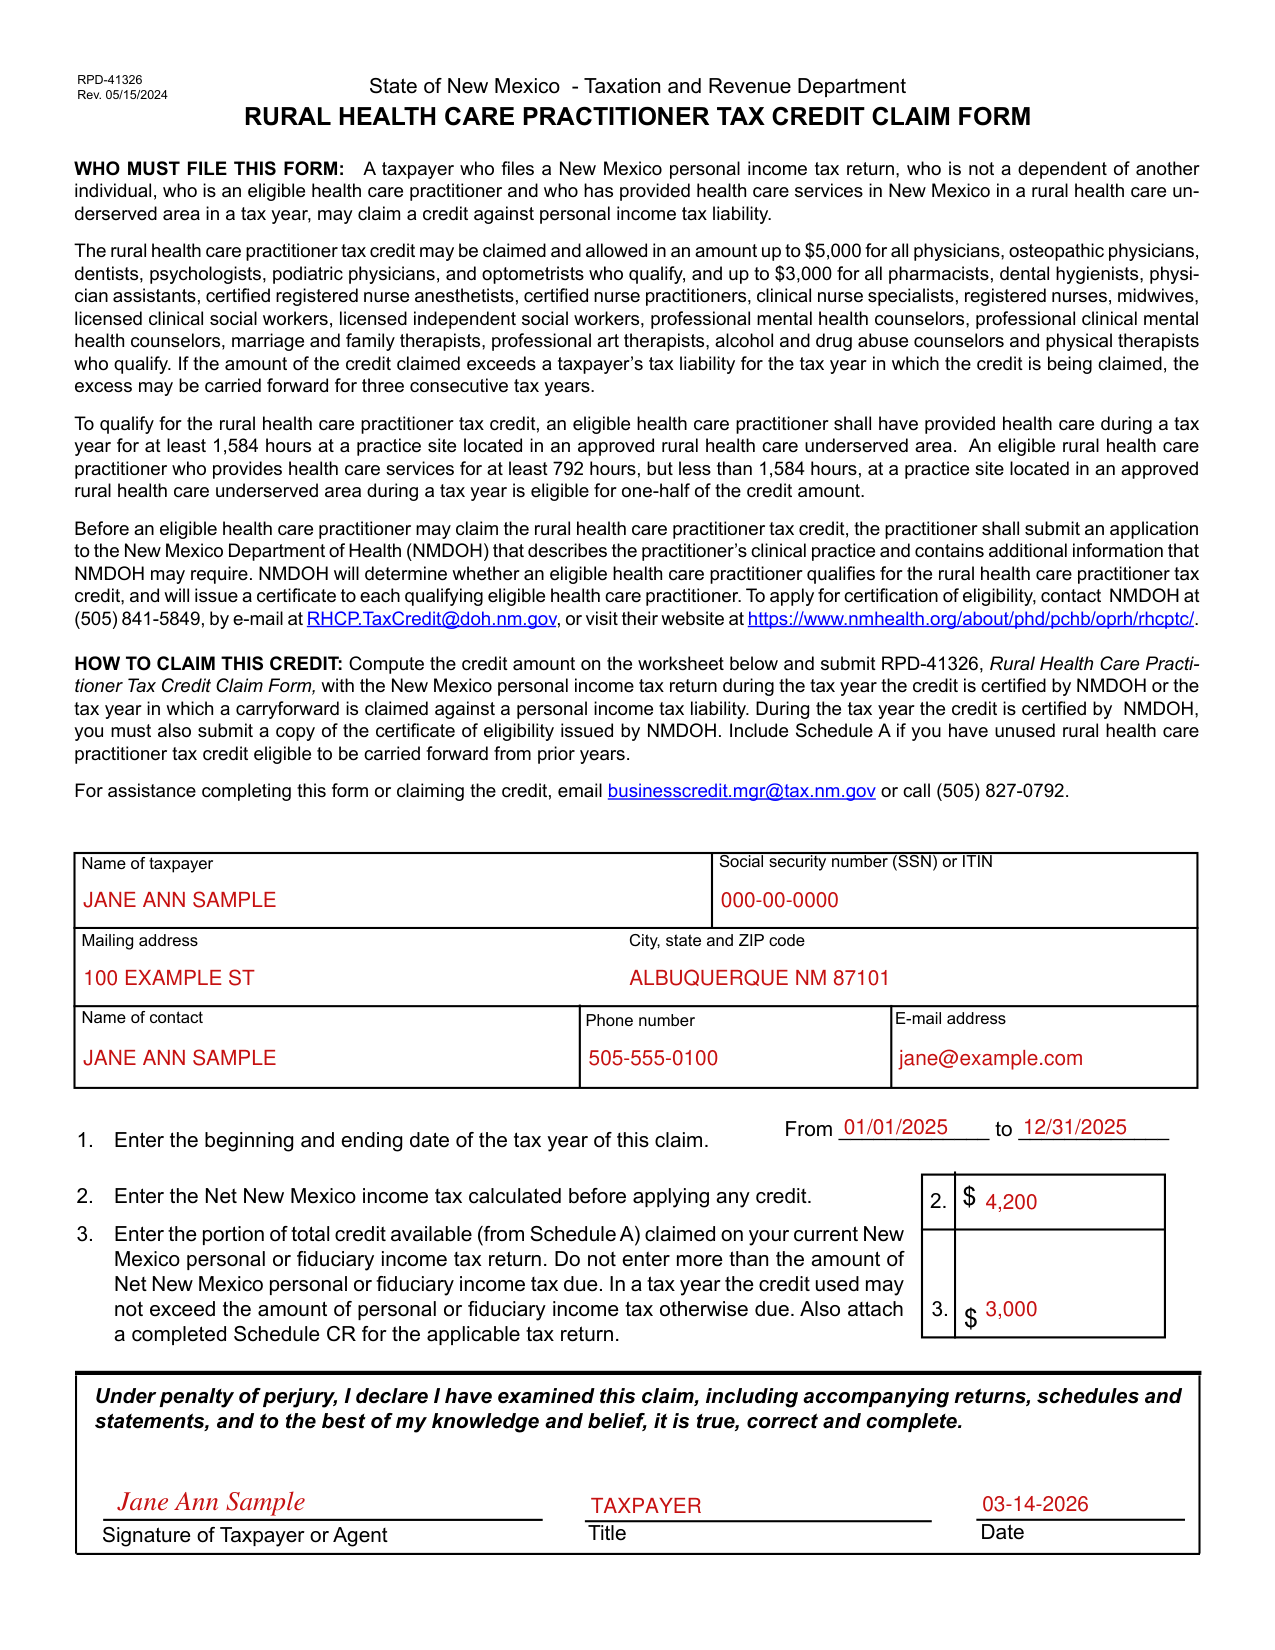
How to fill out Form RPD-41326, box by box
Name of taxpayer, SSN or ITIN, address and contact
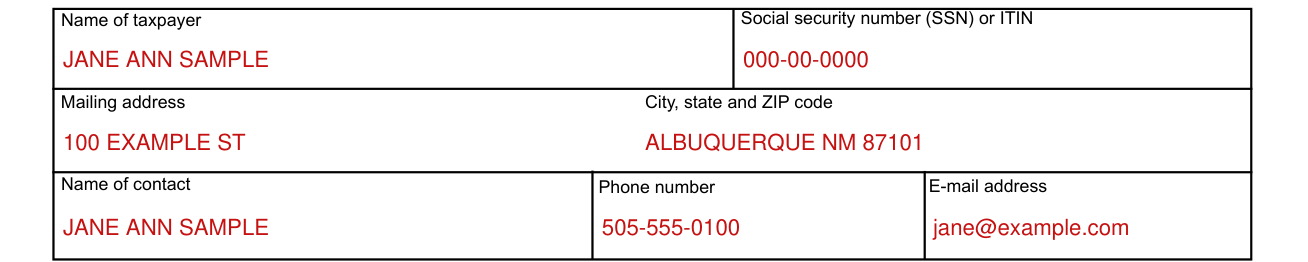
Enter the Name of taxpayer and the Social security number (SSN) or ITIN.
Enter the Mailing address and the City, state and ZIP code.
Enter the Name of contact, the E-mail address and the Phone number.
Lines 1 to 3: tax year, net tax and credit claimed
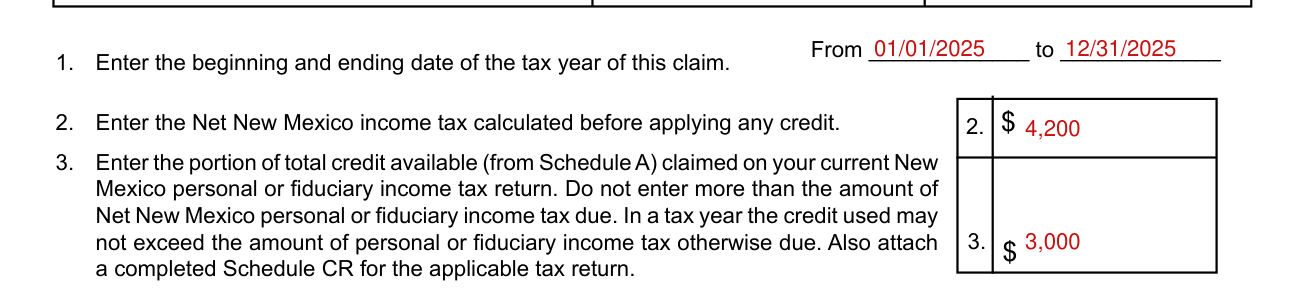
Line 1: Enter the beginning and ending date of the tax year of this claim, From and to.
Line 2: Enter the Net New Mexico income tax calculated before applying any credit.
Line 3: Enter the portion of total credit available (from Schedule A) claimed on your current New Mexico personal or fiduciary income tax return. Do not enter more than the amount of Net New Mexico personal or fiduciary income tax due. Also attach a completed Schedule CR for the applicable tax return.
Schedule A: credits approved by NMDOH
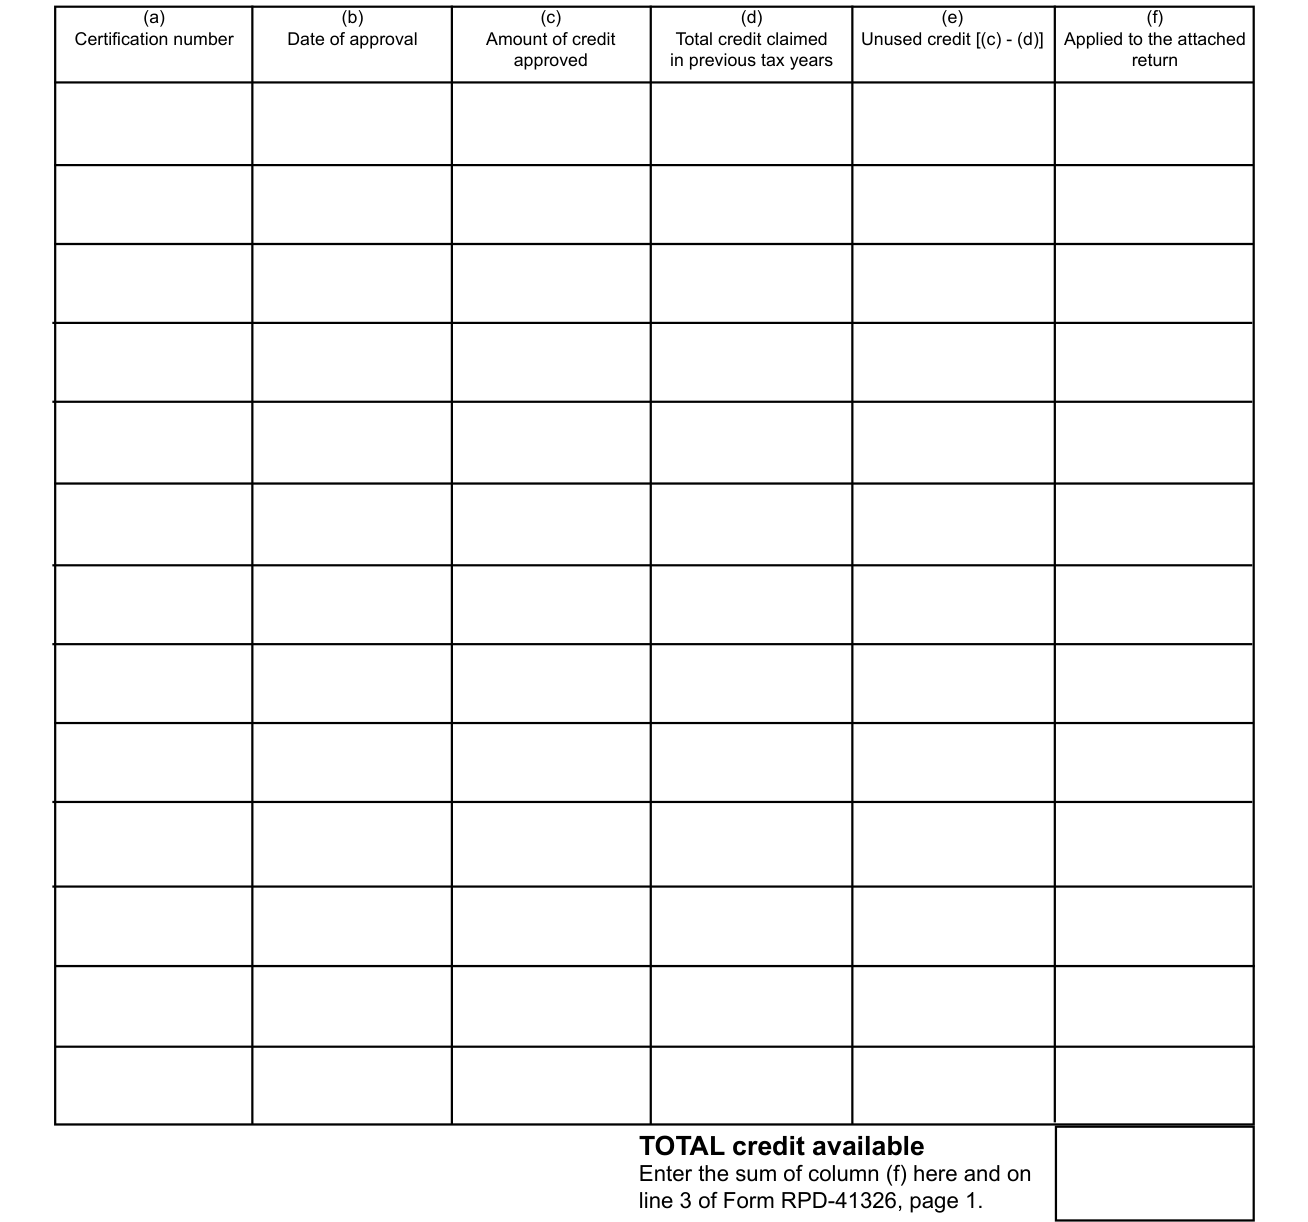
Schedule A Instructions, RPD-41326 Rev. 05/15/2024: For each rural health care practitioner tax credit approved by the New Mexico Department of Health (NMDOH) complete a row in Schedule A.
(a) Certification number: Enter the certification number for each rural health care practitioner tax credit shown on the credit approval document issued by NMDOH.
(b) Date of approval: Enter the date the rural health care practitioner tax credit was approved as indicated on the certificate issued by NMDOH.
(c) Amount of credit approved: For each credit, enter the amount approved, as indicated on the certificate issued by NMDOH.
(d) Total credit claimed in previous tax years: For each credit listed, enter the total amount of credit claimed in all tax years prior to the current tax year.
Unused credit: From the amount in column (c), subtract the amount in column (d) for each credit.
(f) Applied to the attached return: For each credit, enter in column (f) the amount that is applied to the attached New Mexico income tax return.
TOTAL credit available: Enter the sum of column (f) here and on line 3 of Form RPD-41326, page 1.
Signature, Title and Date

Under penalty of perjury, I declare I have examined this claim, including accompanying returns, schedules and statements, and to the best of my knowledge and belief, it is true, correct and complete.
Sign as Signature of Taxpayer or Agent, then enter the Title and the Date.
More rules for Form RPD-41326
For assistance completing this form or claiming the credit, email businesscredit.mgr@tax.nm.gov or call (505) 827-0792.
If your situation is different
Submit the claim with your New Mexico personal income tax return
Compute the credit amount on the worksheet and submit RPD-41326, Rural Health Care Practitioner Tax Credit Claim Form, with the New Mexico personal income tax return during the tax year the credit is certified by NMDOH or the tax year in which a carryforward is claimed against a personal income tax liability. During the tax year the credit is certified by NMDOH, you must also submit a copy of the certificate of eligibility issued by NMDOH. Include Schedule A if you have unused rural health care practitioner tax credit eligible to be carried forward from prior years.
Once a credit application is approved by the New Mexico Department of Health (NMDOH), complete and attach Form RPD-41326, including Schedule A, to your New Mexico income tax return along with the tax credit Schedule CR applicable to the tax program toward which you are applying the credit.
Attach a copy of your certificate from NMDOH.
Unused credit carried forward for consecutive tax years
Unused rural health care practitioner tax credit may not be carried forward for more than three consecutive tax years following the tax year for which the credit was approved.
Do not include credits approved in a tax year that is more than four years prior to the tax year for which this claim is filed.
Do not include credits which have been claimed in full in prior tax years.
Do not enter a credit if the certificate of eligibility is for a tax year more than four years from the tax year of this claim or if the credit was not approved by NMDOH.
Apply credits in the order that they were approved
Applying credits: Apply rural health care practitioner tax credit in the order that they were approved. The oldest credit should be applied first.
If you have both a carry forward credit and a credit approved in the current tax year, apply the older credits first.
The sum of tax credits applied to the tax due on the return may not exceed the income tax claimed on the New Mexico income tax return. That amount is the net New Mexico income tax calculated before applying any tax credits claimed.
Apply for certification of eligibility
To qualify for the rural health care practitioner tax credit, an eligible health care practitioner shall have provided health care during a tax year for at least 1,584 hours at a practice site located in an approved rural health care underserved area. An eligible rural health care practitioner who provides health care services for at least 792 hours, but less than 1,584 hours, at a practice site located in an approved rural health care underserved area during a tax year is eligible for one-half of the credit amount.
Before an eligible health care practitioner may claim the rural health care practitioner tax credit, the practitioner shall submit an application to the New Mexico Department of Health (NMDOH). NMDOH will determine whether an eligible health care practitioner qualifies for the rural health care practitioner tax credit, and will issue a certificate to each qualifying eligible health care practitioner. To apply for certification of eligibility, contact NMDOH at (505) 841-5849, by e-mail at RHCP.TaxCredit@doh.nm.gov, or visit their website at https://www.nmhealth.org/about/phd/pchb/oprh/rhcptc/.
“Practice site” means a private practice, public health clinic, hospital, public or private non-profit primary care clinic or other health care service location in a health care underserved area.
“Rural” means a rural county or an unincorporated area of a partially rural county, as designated by the Health Resources and Services Administration of the United States Department of Health and Human Services.
“Health care underserved area” means a geographic area or practice location in which it has been determined by the New Mexico Department of Health, through the use of indices and other standards set by the New Mexico Department of Health, that sufficient health care services are not being provided.
Sources
[1] Form RPD-41326 (Rev. 05/15/2024), Rural Health Care Practitioner Tax Credit Claim Form, New Mexico Taxation and Revenue Department (the Official source link on this page).