

Form W6 at a glance
What it is: Form W6, Excise Warehouse Remittance advice for tobacco goods, is for Excise Duty and Value Added Tax on tobacco goods only.
Who signs: Add your Signature and Phone number; delete as necessary: Proprietor, partner, director or duly authorised person.
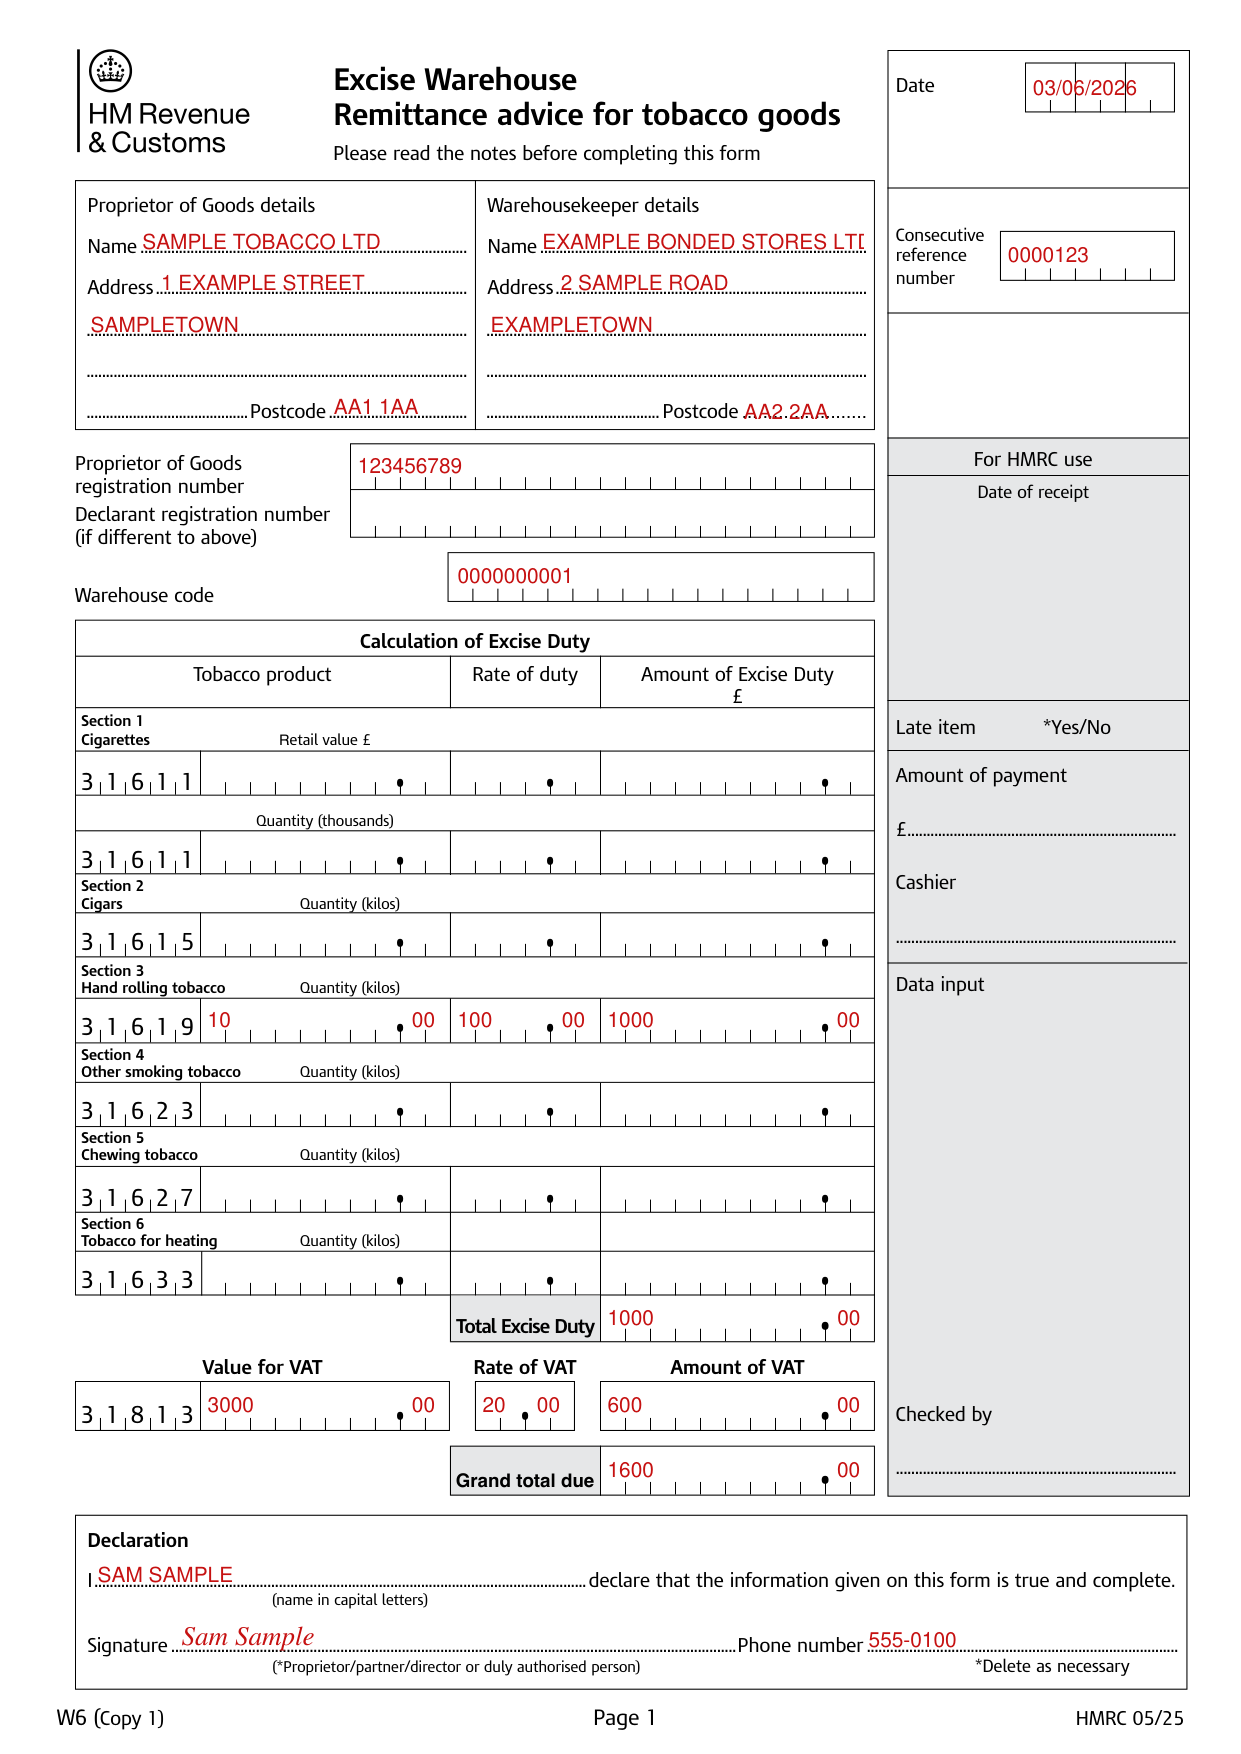
A filled-in Form W6 example: hand rolling tobacco released from a warehouse
How to fill out Form W6, box by box
Proprietor of Goods details and Warehousekeeper details
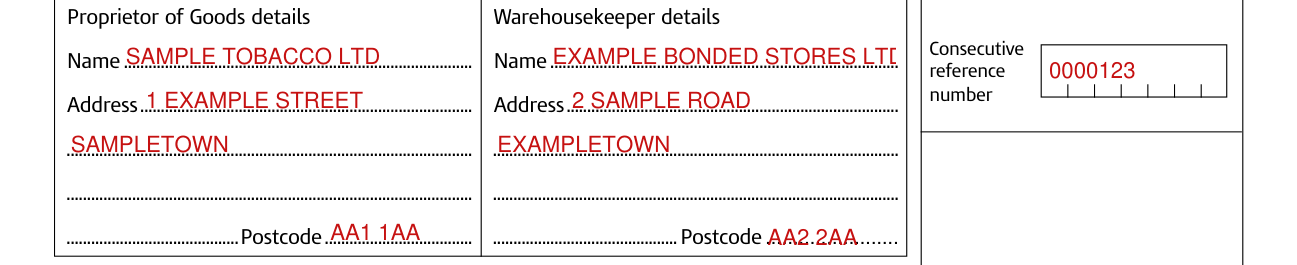
Under Proprietor of Goods details and Warehousekeeper details, fill in Name, Address and Postcode.
Complete a separate form for each proprietor of the goods.
Common mistake: All entries must be clear. Do not overwrite, rub out or use correcting fluid on entry errors.
Common mistake: You must rule through and arrange for the signatory to initial any amendments.
Date, registration number, warehouse code and Consecutive reference number
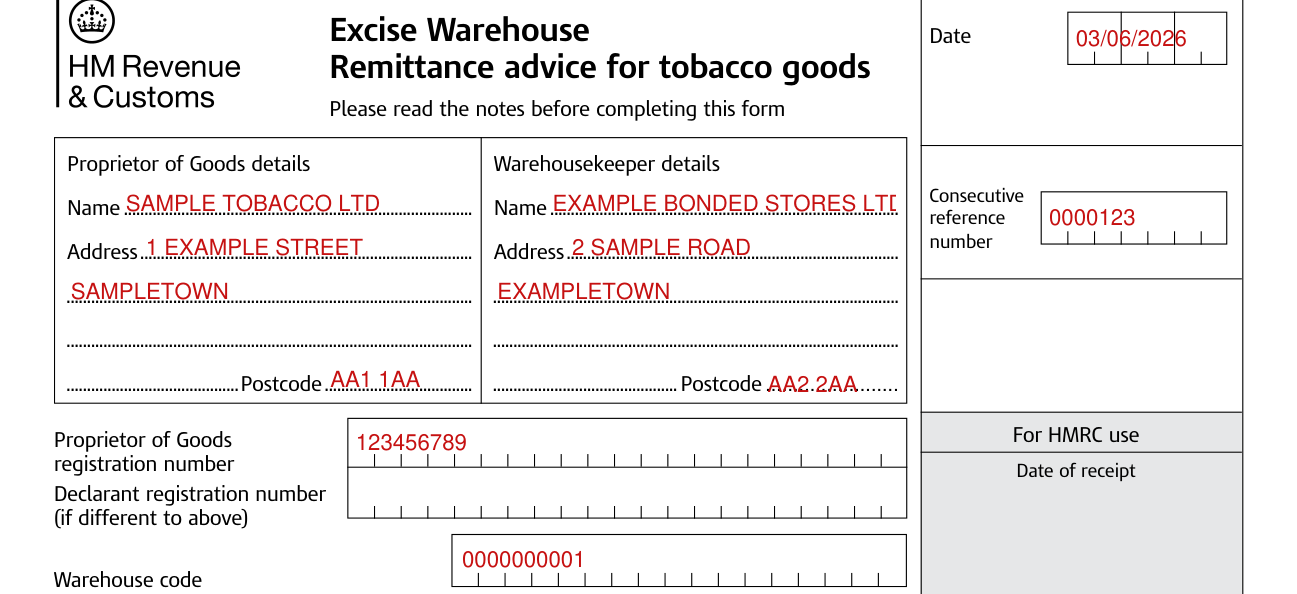
Fill in Date.
In Registration number, complete using the VAT Registration Number.
Fill in Declarant registration number if different to the Proprietor of Goods registration number.
Warehouse code is your warehouse authorisation number.
In Consecutive reference number, insert a Consecutive Reference Number (CRN) that cross refers to the business records of the despatching warehousekeeper.
It must be readily identifiable to the relevant stock accounting period.
The CRN must not exceed 7 digits and it must consist of numbers only.
Section 1 Cigarettes
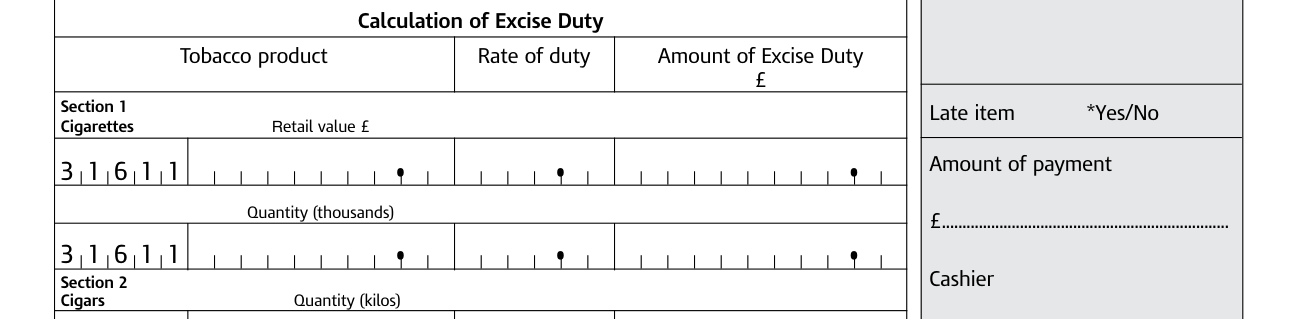
In Section 1 Line 1, show the total retail value in the first box; in the Rate of duty box enter the percentage rate of duty.
In Line 2, show the quantity in thousands, for example, for 20,000 cigarettes enter 20.00; in the Rate of duty box enter the current rate of duty.
In the Quantity (thousands) box, show the quantity in thousands, for example, for 20,000 cigarettes enter 20.00.
Enter the Amount of Excise Duty for the product in its Amount of Excise Duty box.
For cigarettes only you should also include a separate statement showing an analysis of the overall totals by: a) brand b) total cigarettes of that brand c) recommended retail price of pack.
Sections 2 to 6
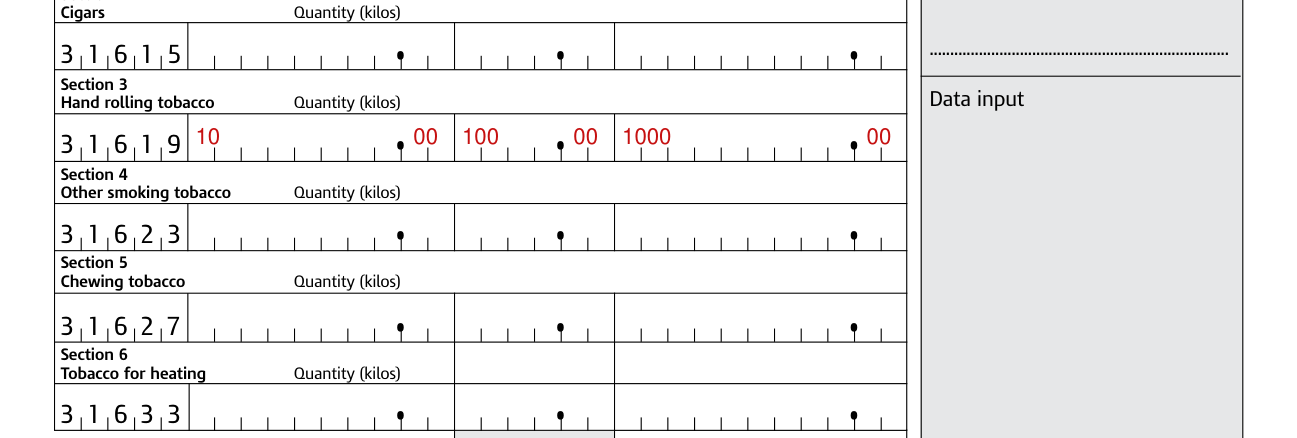
In Sections 2 to 6, enter the quantity in kilograms truncated to 2 decimal places; in the Rate of duty box enter the current rate of duty.
In Sections 2 to 6 (Cigars, Hand rolling tobacco, Other smoking tobacco, Chewing tobacco and Tobacco for heating), enter the Quantity (kilos) in kilograms truncated to 2 decimal places.
Common mistake: You must also rule through any unused lines.
Total Excise Duty, Value for VAT and Grand total due
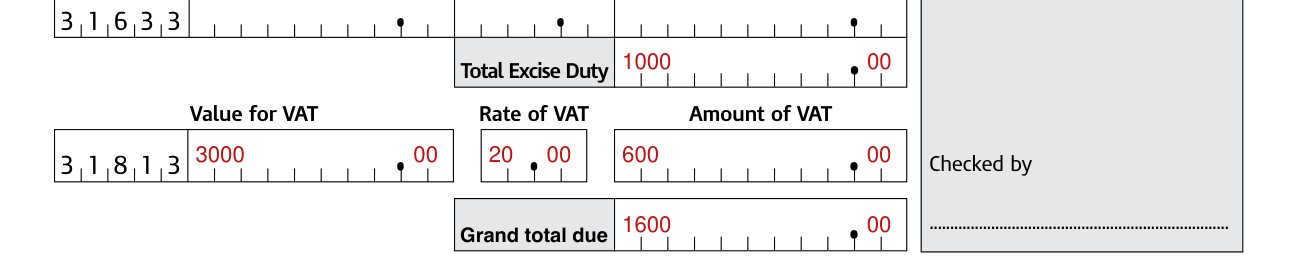
Fill in Total Excise Duty, Value for VAT, Rate of VAT, Amount of VAT and Grand total due.
Note that the value for VAT must include Excise Duty in all cases (and customs duty if applicable).
If, whilst in warehouse, the goods have been subject to a supply, or additional services such as storage or handling, it may affect the VAT position.
Declaration
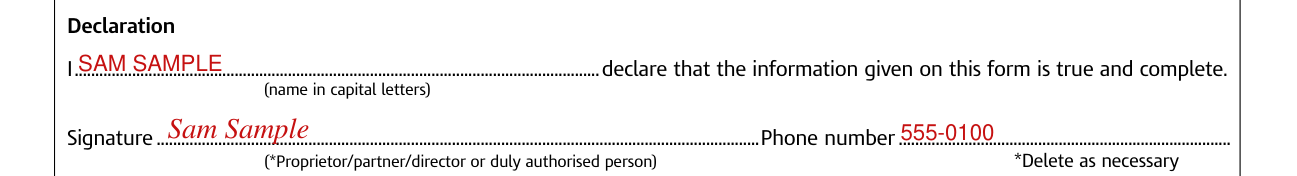
In the Declaration, write your name in capital letters after I, to declare that the information given on this form is true and complete.
Add your Signature and Phone number; delete as necessary: Proprietor, partner, director or duly authorised person.
More rules for Form W6
Separate forms, clearly noted, will need to be used detailing the different types of removal from excise warehouse.
It is advisable to use separate forms, clearly noted, for detailing any underpayments or overpayments uncovered, and include a cross reference to the previous mistaken entry, with a brief description of the reason for the error.
Goods from Great Britain and Northern Ireland warehouses
Goods entering GB from the EU before 1 January 2021 and released from duty suspense in an excise warehouse on or after 1 January 2021
Goods entering GB from the EU before 1 January 2021, and released from duty suspense in an excise warehouse on or after 1 January 2021, EC free circulation goods subject to acquisition VAT procedures. In these cases complete the Value/Rate boxes and enter 'ACQ VAT' in the amount of VAT box.
Please retain this information for your records.
EC free circulation goods supplied on whilst in warehouse in GB
For EC free circulation goods where the requirement to account for acquisition VAT is extinguished because the goods are supplied on whilst in warehouse in GB, Supply VAT is due: complete the Value/Rate/amount boxes.
You will receive a C79 certificate to support your claim for input tax deduction.
Goods entering GB from the EU or third countries, or NI from third countries, under customs rules
Goods released from duty suspense in an excise warehouse on or after 1 January 2021. To use postponed VAT accounting to declare and recover import VAT on your VAT return, complete the Value/Rate boxes and enter 'ACQ VAT' in the Amount of VAT box.
Please ensure that you retain evidence of how you calculate the value for VAT declared. You will need this to complete your VAT return as you will not receive a monthly postponed import VAT statement.
If you do not wish to use postponed VAT accounting to declare and recover import VAT on your VAT return, complete the Value/Rate/amount boxes.
Goods produced in GB or NI and supplied in warehouse in GB
For goods produced in GB or NI which are supplied in warehouse in GB, Supply VAT is due on the last supply made in warehouse: complete the Value/Rate/amount boxes.
Goods entering NI from the EU and released from duty suspense in an excise warehouse
There will be no change to the way that VAT is accounted for. This means that where you enter 'ACQ VAT' it means acquisition VAT, and it is essential that this is shown on a separate form from entries for Goods entering NI from third countries under customs rules, and released from duty suspense in an excise warehouse on or after 1 January 2021.
Goods produced in GB or NI and supplied in warehouse in NI
For goods produced in GB or NI which are supplied in warehouse in NI, Supply VAT is due on the last supply made in warehouse: complete the Value/Rate/amount boxes.
Common questions about Form W6
Is there a penalty?
You can avoid financial penalties by making sure that you have given complete and accurate information on this form and that you submit the form and pay the duty due prior to release of the goods from the warehouse.
Sources
[1] Form W6 (HMRC 05/25), Excise Warehouse Remittance advice for tobacco goods, HM Revenue and Customs (the Official source link on this page).