

Form WH-1 at a glance
What it is: DISB WH-1 is the University of Hawaii Statement of Citizenship and Federal Tax Status.
Who signs: Sign Section E: Signature and Date.
This form is for individuals.
United States citizens: Complete Sections A and E only.
Permanent resident aliens: Complete Sections A and E only. Attach a photocopy (front and back) of your Alien Registration Card. All others: 1. Complete Sections A, B, C, and E. 2. Complete Section D if applicable. 3. Submit copy of your electronic I-94 Passport ID Page and Visa page. 4. Submit IRS Form W8-BEN for foreign status. 5. For J-1 visaholders, submit copy of DS-2019. 6. For B visaholders, submit DISB-45. 7. For F-1 visaholders, submit copy of I-20. 8. Submit IRS Form 8233 if performing services as independent contractor (Treaty only).
A filled-in Form WH-1 example: a US citizen completes Sections A and E
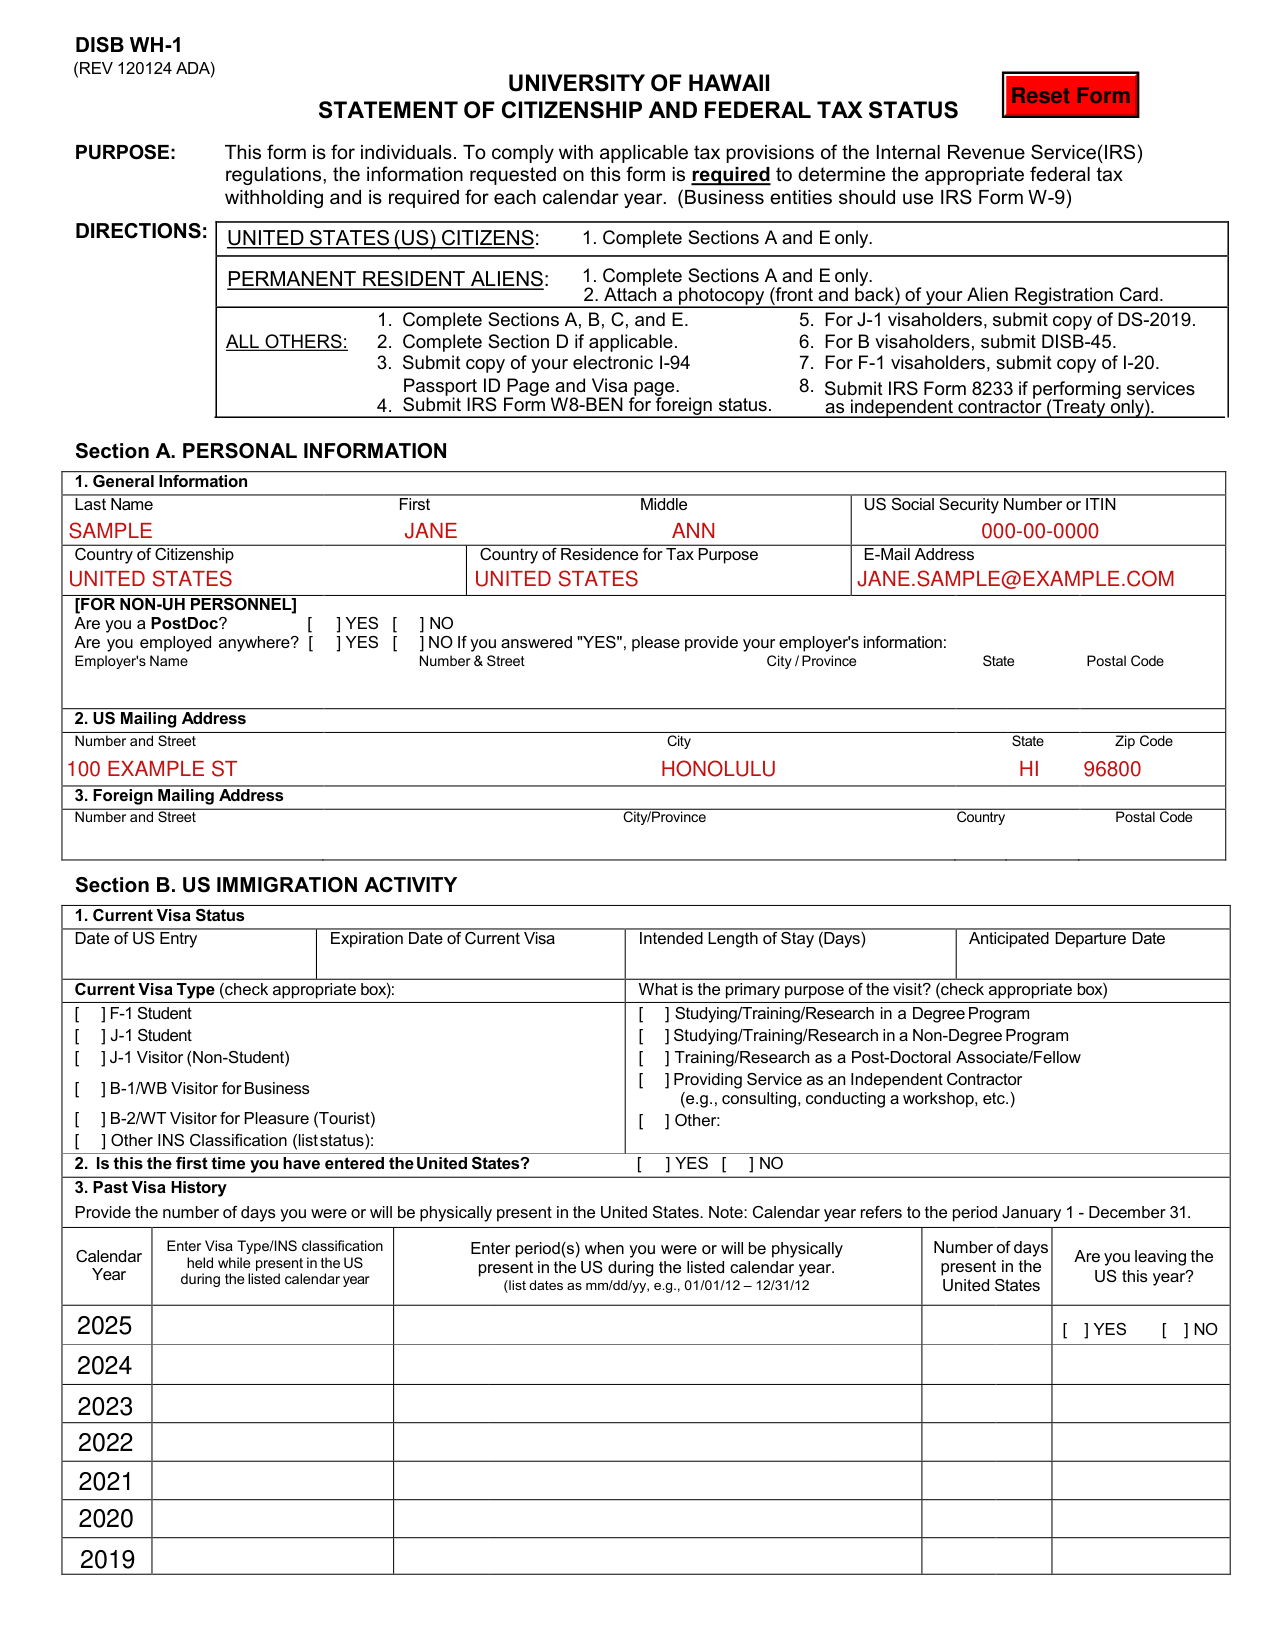
How to fill out Form WH-1, box by box
Section A. PERSONAL INFORMATION
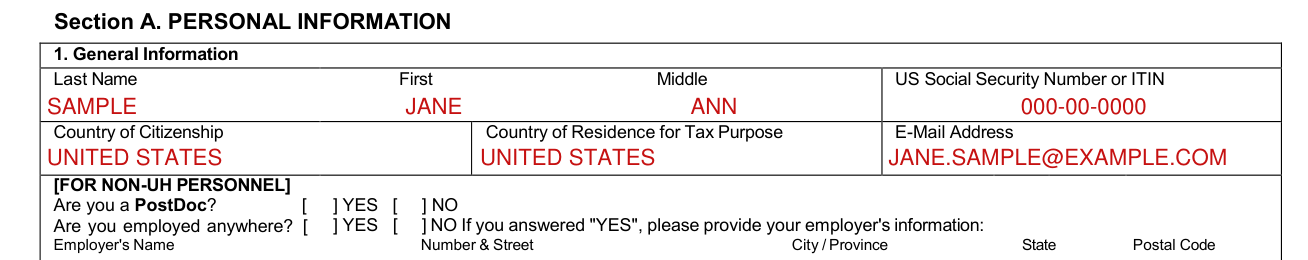
Section A. PERSONAL INFORMATION: Under 1. General Information, enter Last Name, First, Middle and Social Security Number or ITIN.
Enter Country of Citizenship, Country of Residence for Tax Purpose and E-Mail Address.
FOR NON-UH PERSONNEL: PostDoc and employer

[FOR NON-UH PERSONNEL] Are you a PostDoc? Mark YES or NO. Are you employed anywhere? Mark YES or NO. If you answered "YES", please provide your employer's information: Employer's Name, Number & Street, City / Province, State and Postal Code.
2. US Mailing Address
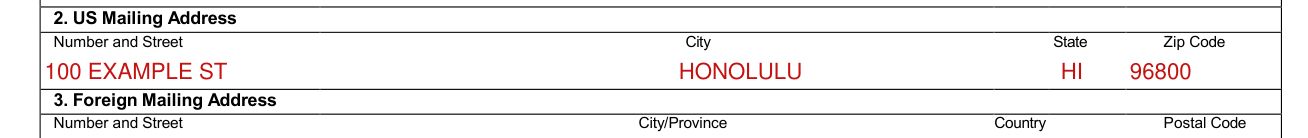
Under 2. Mailing Address, enter Number and Street, City, State and Zip Code.
3. Foreign Mailing Address

Under 3. Foreign Mailing Address, enter Number and Street, City/Province, Country and Postal Code.
Section B. IMMIGRATION ACTIVITY
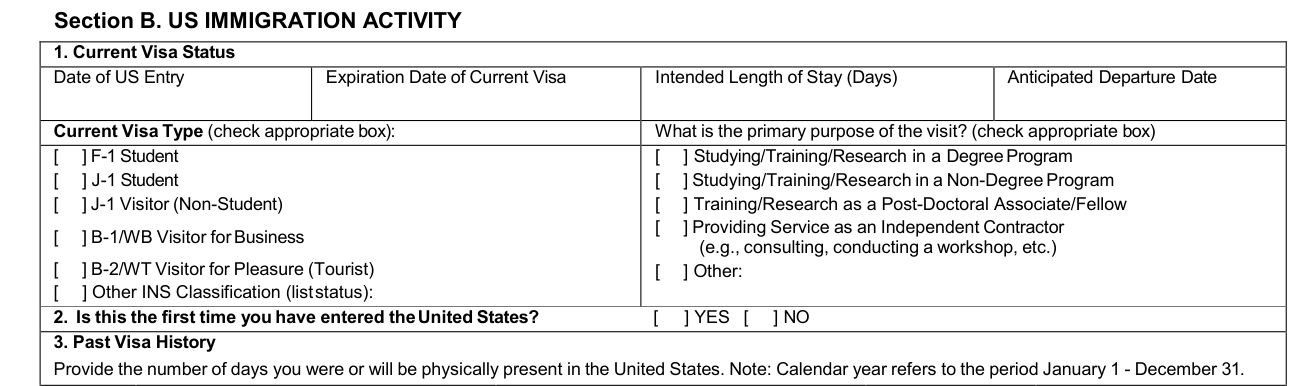
Section B. IMMIGRATION ACTIVITY: Under 1. Current Visa Status, enter Date of Entry, Expiration Date of Current Visa, Intended Length of Stay (Days) and Anticipated Departure Date.
Current Visa Type (check appropriate box): F-1 Student, J-1 Student, J-1 Visitor (Non-Student), B-1/WB Visitor for Business, B-2/WT Visitor for Pleasure (Tourist) or Other INS Classification (liststatus).
What is the primary purpose of the visit? (check appropriate box): Studying/Training/Research in a Degree Program, Studying/Training/Research in a Non-Degree Program, Training/Research as a Post-Doctoral Associate/Fellow, Providing Service as an Independent Contractor (e.g., consulting, conducting a workshop, etc.) or Other.
Is this the first time you have entered the United States? Mark YES or NO.
Under 3. Past Visa History, provide the number of days you were or will be physically present in the United States. Note: Calendar year refers to the period January 1 - December 31.
For Calendar Year 2025, 2024, 2023, 2022, 2021, 2020 and 2019, enter Visa Type/INS classification held during the listed calendar year and enter period(s) when you were or will be physically present during the listed calendar year. (list dates as mm/dd/yy, e.g., 01/01/12 - 12/31/12), the Number of days present in the United States, and mark YES or NO for Are you leaving the United States this year?
4. Please list all F, J, M or Q Visas since January 1, 1985 not listed in Section B,3.
Section C. Tax Status Determination
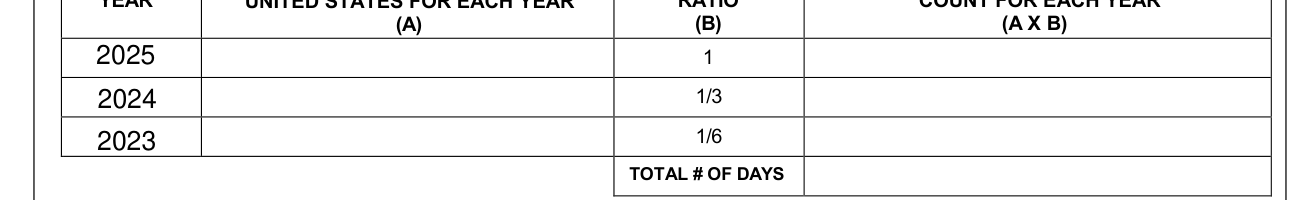
STEP 1: Complete the Substantial Presence Test (SPT) by completing the table.
Enter the total number of days you were or will be present in the United States for each year (A), the ratio (B) and calculate the total number of days to count for each year (A X B).
For F, J, M or Q Visa holders, please note the following: For F, J, or M Student Visa holders: Do NOT count any days during your first 5 calendar years in the United States in which you held an F, J, or M student visa. For J or Q Non-Student Visa holders: Do NOT count any days during your first 2 calendar years in the current and previous 6 calendar years in the United States in which you held a J or Q Non-Student visa.
STEP 2: Please answer the following questions: A. Does the TOTAL NUMBER OF DAYS TO COUNT for the current calendar year equal to 31 days or more? Mark YES or NO.
B. Does the TOTAL # OF DAYS for all three years equal to 183 days or more? Mark YES or NO.
STEP 3: Determine your tax status: If you marked "YES" to both questions A and B, then you passed the Substantial Presence Test and will be treated as a RESIDENT ALIEN (RA) FOR TAX PURPOSES for this calendar year. Go to and sign Section E.
If you marked "No" to one or both questions, then you did not pass the Substantial Presence Test and will be treated as a NONRESIDENT ALIEN FOR TAX PURPOSES for this calendar year. Go to Section D.
Section D. EXEMPTION FROM WITHHOLDING FOR THE NONRESIDENT ALIEN
All Payments made to Nonresident Aliens are subject to federal tax withholding at a statutory rate of 30%. However, you may claim an exemption from withholding or reduced rate via a Tax Treaty if you meet the following requirements:
Consult IRS Publication 901, US Tax Treaties, at http: /www.irs.gov/pub/irs-pdf/p901.pdf: you must be a resident of a country that has a tax treaty with the US.
The tax treaty must have a treaty article applicable to the type of payment you'll be receiving: Scholarship or Fellowship Article for Scholarship, Fellowship, Traineeship Payments. OR Independent Personal Services Article for Fee for Services, Honoraria, and Reportable Travel payments.
You must meet all requirements regarding residency, time, and dollar limitations described in the tax treaty.
You must have a Social Security Number (SSN) or Individual Taxpayer Identification Number (ITIN) to claim a treaty exemption.
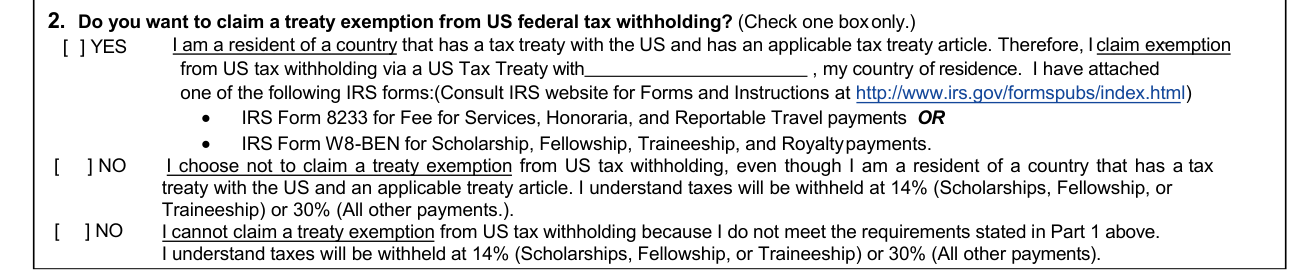
Do you want to claim a treaty exemption from federal tax withholding? (Check one box only.)
YES I am a resident of a country that has a tax treaty and has an applicable tax treaty article. Therefore, I claim exemption from tax withholding via a Tax Treaty with the country you enter, my country of residence. I have attached one of the following IRS forms: IRS Form 8233 for Fee for Services, Honoraria, and Reportable Travel payments OR IRS Form W8-BEN for Scholarship, Fellowship, Traineeship, and Royaltypayments.
NO I choose not to claim a treaty exemption from tax withholding, even though I am a resident of a country that has a tax treaty and an applicable treaty article. I understand taxes will be withheld at 14% (Scholarships, Fellowship, or Traineeship) or 30% (All other payments).
NO I cannot claim a treaty exemption from tax withholding because I do not meet the requirements stated in Part 1. Taxes will be withheld at 14% (Scholarships, Fellowship, or Traineeship) or 30% (All other payments).
Section E. CERTIFICATION OF INFORMATION PROVIDED ON THIS FORM
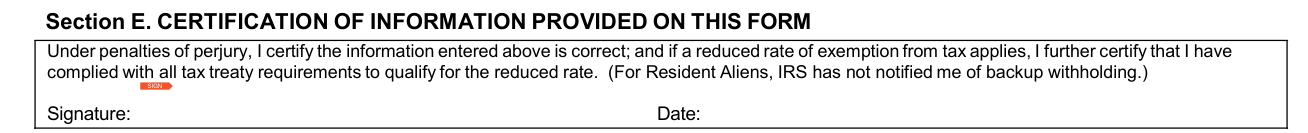
Section E. CERTIFICATION OF INFORMATION PROVIDED ON THIS FORM: Under penalties of perjury, I certify the information entered is correct; and if a reduced rate of exemption from tax applies, I further certify that I have complied with all tax treaty requirements to qualify for the reduced rate. (For Resident Aliens, IRS has not notified me of backup withholding.)
More rules for Form WH-1
The information requested on this form is required to determine the appropriate federal tax withholding and is required for each calendar year.
Common questions about Form WH-1
When is this form not the right one?
Business entities should use IRS Form W-9, not this form.
Sources
[1] Form DISB WH-1 (REV 120124 ADA), Statement of Citizenship and Federal Tax Status, University of Hawaii (the Official source link on this page).