

Form WR-1 at a glance
What it is: Form WR-1, Employer's Quarterly Report of Wages Paid, is a Massachusetts Wage Reporting System form from the Massachusetts Department of Revenue.
Where and when to file: Mail to: DOR Wage Reporting Unit, PO Box 7029, Boston, MA 02204. Form WR-1 is due by the last day of the month following the end of the quarter.
Where to get it: To print a Form WR-1, employers should visit the website at www.mass.gov/dor.
Any person or business that employs one or more individuals and maintains a place of business or does business in Massachusetts is required to file an Employer's Quarterly Report of Wages Paid, Form WR-1.
Any person or business subject to Massachusetts withholding under Massachusetts General Laws, Chapter 62B, is also subject to wage reporting requirements.
Every employer must submit quarterly reports for each employee who either resides or is employed in Massachusetts, whether or not the employee's wages are subject to withholding of tax or payment of tax under Massachusetts income tax law.
A filled-in Form WR-1 example: one employee in the first quarter
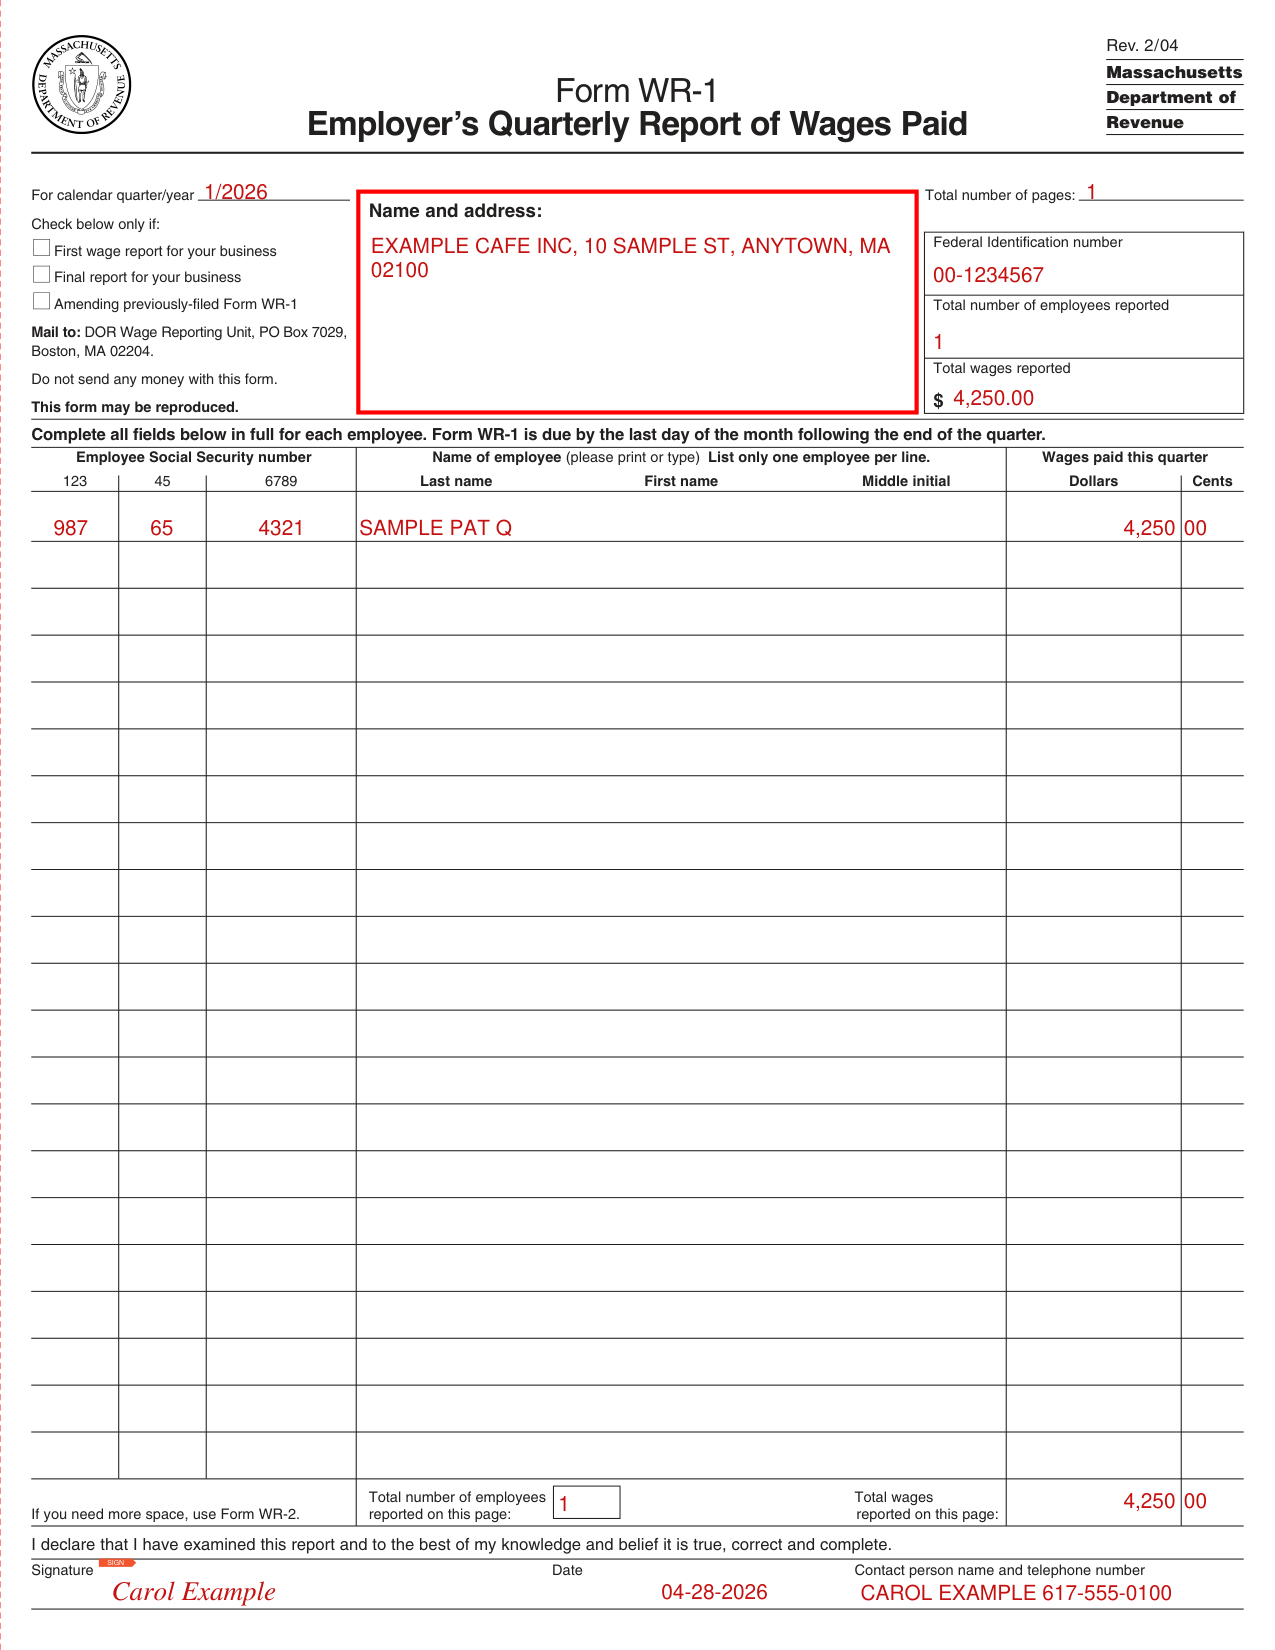
How to fill out Form WR-1, box by box
Name and address, quarter and pages
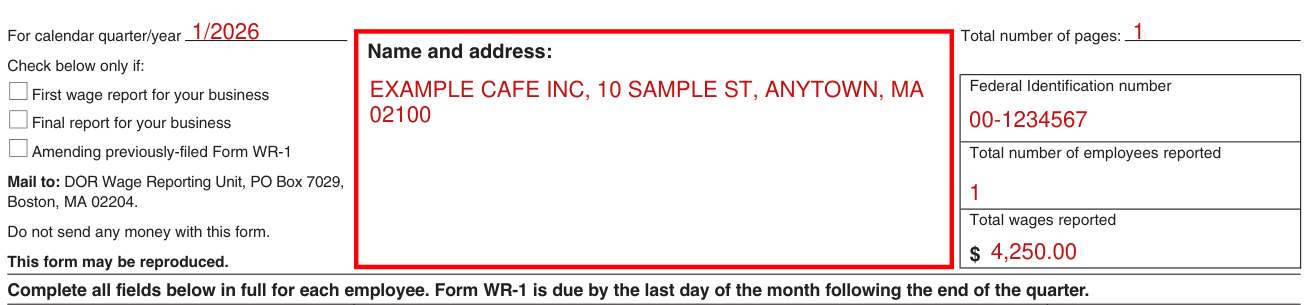
Enter the Name and address and the calendar quarter/year.
The employer's name, address and Federal Identification number must be shown on all forms and correspondence sent to DOR.
Enter the Total number of pages.
Check below only if
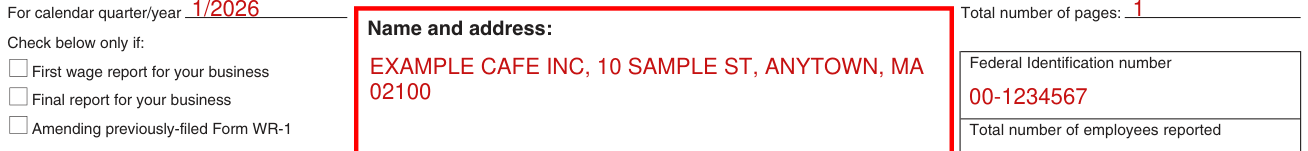
Check only if it is your First wage report for your business, your Final report for your business, or an Amending previously-filed Form WR-1.
If a previously filed paper Form WR-1 needs corrections, you must submit a new Form WR-1 and check "amending."
Wage adjustments for a prior quarter must be reported on a separate Form WR-1 with the "amending" box checked.
Report all information for each employee where an adjustment is required. Clearly state the quarter-end date and year-end date of the amended return.
A separate report must be filed for each quarter. Adjustments should not be made in the reports for subsequent quarters.
Federal Identification number, total number of employees reported and total wages reported
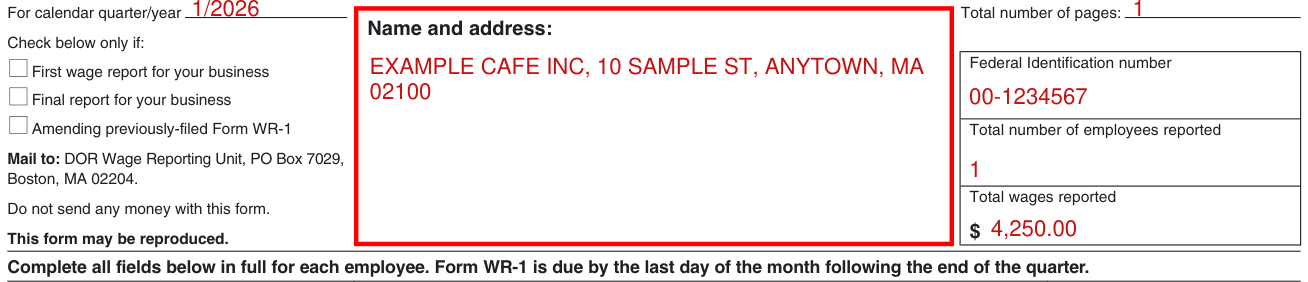
Enter the Total number of employees reported and the Total wages reported.
Enter the Federal Identification number: it is generally the nine-digit Federal Identification number also used for Massachusetts income tax withholding purposes.
The total number of employees and the total wages paid during the quarter must be shown in the applicable boxes to the right of the name and address area on Form WR-1.
Employee Social Security number, name and wages paid this quarter
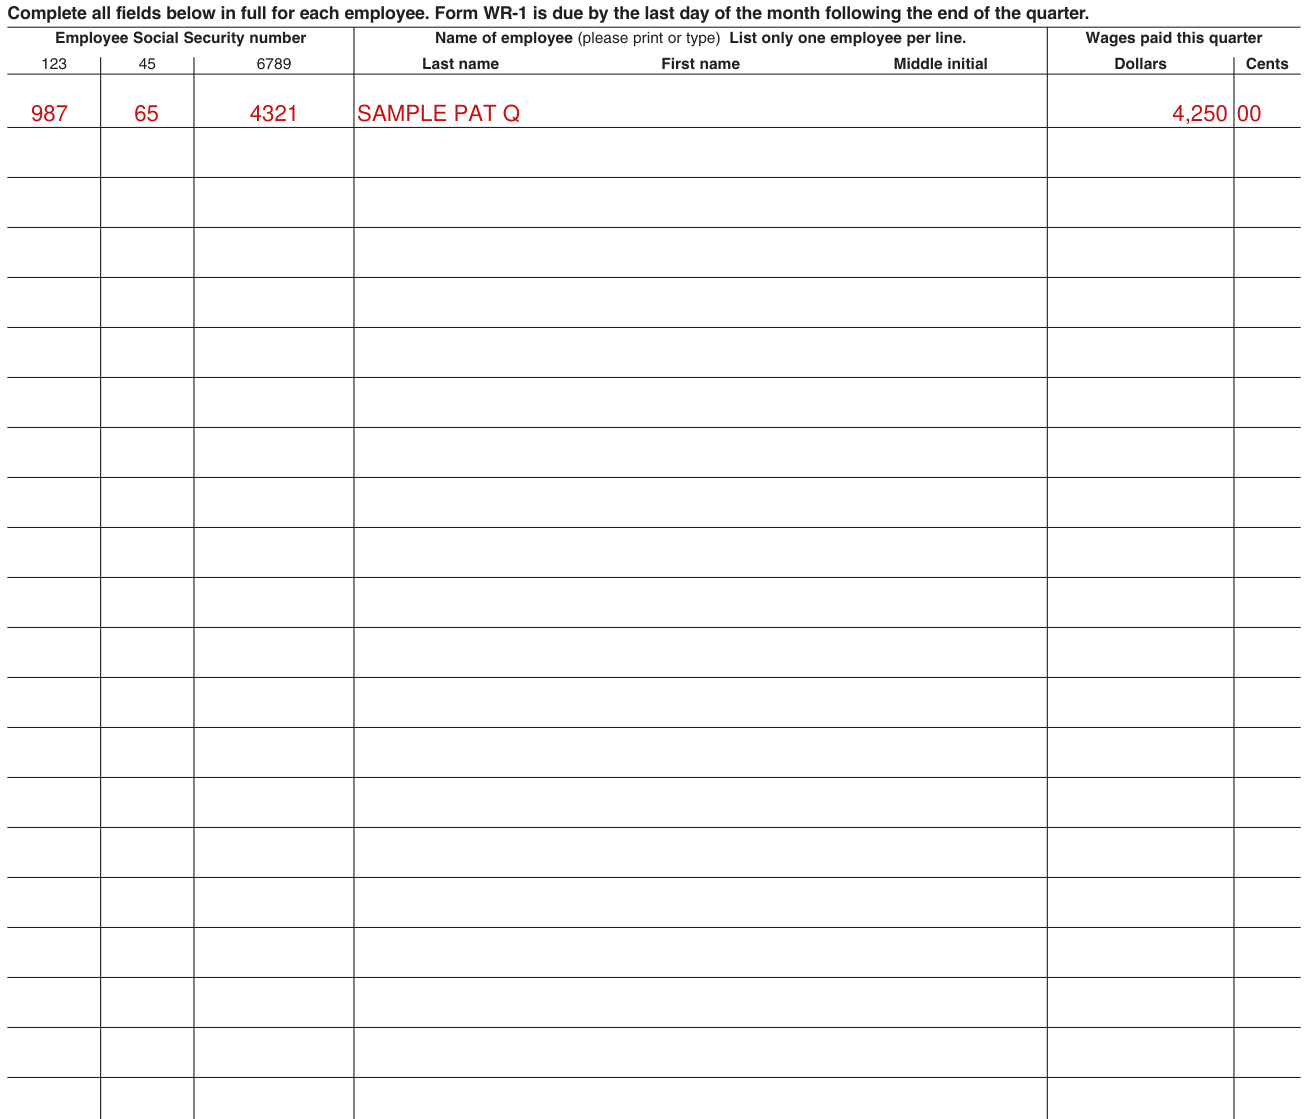
Complete all fields in full for each employee. List only one employee per line.
You must report the wages for each employee who worked for you and was paid wages during any part of the calendar quarter.
If there were interruptions in the employment of any employee during the quarter, the different periods of employment must be grouped together and one entry made for each employee for the quarter.
The employee's Social Security number must be entered in the first column exactly as shown on his/her Social Security card.
Reports with blank or invalid Social Security numbers are not acceptable. Any report submitted without a valid Social Security number will be returned to the employer for correction.
The employee's name (last name first, first name and middle initial) must be entered in the second column.
The wages paid in each quarter must be reported for each employee residing in Massachusetts regardless of where he/she is employed.
If the employee resides outside of Massachusetts, only his/her wages earned in Massachusetts are required to be reported.
Wages are reportable even if they are not subject to Massachusetts withholding or the payment of Massachusetts income tax.
DOR issues preprinted wage reporting forms (Form WR-1) to all Massachusetts employers who reported 21 or fewer employees in the previous quarter. Since preprinted forms contain the name and Social Security number of each employee, employers only need to record wages.
Employers are responsible for verifying the accuracy of the preprinted information; corrections and deletions to the preprinted employee information should be made in red ink.
Employees who are not listed should be recorded on any available lines at the bottom of Form WR-1, or if necessary on a continuation sheet.
Totals on this page and more space

Enter the Total number of employees reported and the Total wages reported for the page. If you need more space, use Form WR-2.
If you are filing Form WR-1 and need more space, you may report the additional employees on the Continuation Sheet, Form WR-2, included in this booklet.
You may use your own listing sheets in place of the Form WR-2 as long as each sheet contains the employer's name and Federal Identification number as it appears on Form WR-1.
In addition, each employee must be listed in the same format as on the Form WR-1, with individual totals shown in the applicable boxes at the bottom of each sheet.
Signature, date and contact person

Enter the Signature, the Date and the Contact person name and telephone number.
SIGN: "I declare that I have examined this report and to the best of my knowledge and belief it is true, correct and complete."
More rules for Form WR-1
The federal government requires each state to implement a Wage Reporting System, a program establishing a database of all employers paying wages to employees.
Records should be kept for three years after the date the return was filed or the date it was due, whichever is later.
Quarterly wage reports, by Quarter Ending and Due Date: March 31, April 30; June 30, July 31; September 30, October 31; December 31, January 31. If the business is closed, see the section on a closed business.
Filing by tape, spreadsheet or electronically, and other situations
You report 50 or more employees
Employers who report 50 or more employees are required to file electronically or on magnetic media effective for the first quarter of 2005.
Employers can file Form WR-1 via the Internet using "WebFile for Business" (WFB).
You report fewer than 50 employees
Employers with fewer than 50 employees have the choice of two reporting methods; filing the original copy of Form WR-1, or filing on magnetic media.
Magnetic tape or cartridge filers should not complete a Form WR-1, but must file a Magnetic Media Transmitter Report along with each tape or cartridge.
You attach a spreadsheet rather than Form WR-1
If businesses choose to attach a spreadsheet with wage reporting information rather than Form WR-1, the information must be presented in the same format (employee Social Security number, last name, first name and wages paid) as Form WR-1.
Each page of the spreadsheet must contain a subtotal of the number of employees and wages reported on that page. The total number of employees and wages must be reported on the Form WR-1 coversheet that is attached to the spreadsheet.
A corporate headquarters, payroll service or tax service organization files your returns
Employers who have their wage reporting returns, Form WR-1, filed by their corporate headquarters, payroll service, or tax service organization are not mailed a quarterly Form WR-1.
Your wage reports are electronic
Electronic wage reports can be amended online using WebFile for Business.
The business is closed
If the business is closed or the employer permanently ceases to pay wages, he/she must file a final wage report by the last day of the month following the end of the month in which the business or payment of wages ceased.
Common questions about Form WR-1
Is there a deadline?
Form WR-1 is due no later than the last day of the month following the end of the quarter; provided, however, that if the last day falls on a Saturday, Sunday or legal holiday such reports shall be submitted no later than the next succeeding business day.
Where do I file it?
Mail to: DOR Wage Reporting Unit, PO Box 7029, Boston, MA 02204. Do not send any money with this form.
Is there a penalty?
Any employer who, without reasonable cause, fails to comply with the wage reporting requirements and who, after notification by certified mail, still fails to comply for more than 15 business days without reasonable cause, is liable for the following penalties. Penalties: First failure to comply: up to $25 per employee (checked November 11, 2026). Penalties: Second failure to comply: up to $50 per employee (checked November 11, 2026). Penalties: Third and subsequent failures to comply: up to $100 per employee (checked November 11, 2026).
Sources
[1] Form WR-1 (Rev. 2/04), Employer's Quarterly Report of Wages Paid, Massachusetts Department of Revenue (the Official source link on this page).