
Updated:
A credit check form is written consent to pull someone's credit report. The form names the signer, the party that runs the check and the reason for it. Lenders, landlords and employers ask for one before a loan, a lease or a job.
This guide covers what the form includes, how to fill it out and sign it, and what the Fair Credit Reporting Act (FCRA) says about each use.
Key facts
Build Your Document
Answer a few simple questions to make your document in minutes
Save and Print
Save progress and finish on any device, download and print anytime
Sign and Use
Your valid, lawyer-approved document is ready
A credit check authorization form is a signed document that lets a lender, landlord, insurer or employer obtain one person's credit report for a purpose the form names.
The form goes by several names: credit report authorization form, credit check consent form, authorization to pull credit and FCRA authorization form. Each name refers to the same document, the signer's permission for a named recipient to request a report.
A consumer report is the FCRA's term for a report that a consumer reporting agency, such as a credit bureau, prepares about a person. A credit report is one kind of consumer report. It shows loans, credit accounts, balances and payment history, not every bank account or financial detail of the person.
Under 15 U.S.C. § 1681b, a consumer reporting agency may furnish a consumer report in accordance with the written instructions of the consumer to whom it relates. A signed credit check authorization form is one way to give those written instructions.
The Fair Credit Reporting Act is the federal statute that sets who may obtain a consumer report and for which purposes. The permissible purposes in 15 U.S.C. § 1681b include a credit transaction involving the consumer, employment purposes, the underwriting of insurance involving the consumer, and a legitimate business need for the information in connection with a business transaction that is initiated by the consumer. Under 15 U.S.C. § 1681b, a requester with neither a permissible purpose nor the consumer's written instructions has no ground to obtain the report.
A credit check form is used mainly by lenders and creditors, insurers, landlords and employers, and each of them reads the report for a different decision.
A lender or creditor reviews the credit report before approving a loan, a mortgage or a line of credit. The report shows how the applicant has handled past debts, and the lender uses it to decide whether to approve the credit and on what terms. Under 15 U.S.C. § 1681b, a person who intends to use the information in connection with a credit transaction involving the consumer has a permissible purpose.
An insurer reviews the report when it decides whether to issue a policy and at what price. Under 15 U.S.C. § 1681b, a person who intends to use the information in connection with the underwriting of insurance involving the consumer has a permissible purpose.
A landlord reviews the report to see how a rental applicant has paid past debts before signing a rental agreement. Under 15 U.S.C. § 1681b, a person with a legitimate business need for the information in connection with a business transaction that is initiated by the consumer has a permissible purpose. A signed authorization form puts the applicant's consent in writing either way.
An employer reviews credit history for a hiring, promotion, reassignment or retention decision, often for a role that handles money or financial decisions. Employment checks carry their own FCRA conditions, set out in the next section. Some places add local limits on credit checks in hiring, so an employer checks the local rules before using one.
An FCRA disclosure and authorization form is the employment version of the credit check form, and 15 U.S.C. § 1681b sets two conditions before an employer procures a consumer report for employment purposes.
Under 15 U.S.C. § 1681b, the disclosure document consists solely of the disclosure, so a credit check paragraph inside a longer job application does not serve as that disclosure. A general credit check authorization form, with fields for the signer, the recipient and the purpose, is a separate paper from the standalone disclosure an employer gives under 15 U.S.C. § 1681b.
A credit report authorization form includes the parties, the purpose of the check, the signer's identifying details, a consent clause and a dated signature.
The form names the applicant, who signs and whose report is checked, and the recipient, the person or company that orders the report. Full names, spelled as on the signer's ID, let the credit bureau match the right person. A wrong or partial name can delay the report or return the wrong one.
The purpose line tells the signer why the report is pulled and ties its use to that reason. Common purposes are a loan or credit application, a rental application, insurance underwriting, and employment, promotion, reassignment or retention. A vague purpose such as "general review" leaves the signer unsure what they agreed to.
The identifying details let the credit bureau find the right report and lower the risk of identity mix-ups. A form usually asks for the Social Security number, the date of birth, the driver's license number and past home addresses. The signer can give these details on a separate sheet that goes only to the credit bureau if they prefer not to share them with everyone who handles the form.
The consent clause says in plain words that the signer authorizes the recipient to obtain their credit report. The signature and the date close the form, and the date shows when the consent was given.
The credit check authorization form fills out from top to bottom: the date and the parties at the top, the purpose box in the middle and the signature block at the end.
Before you start, have these ready:
The screenshots under each step show the FormsPal Credit Check Authorization template filled with sample entries in blue, so you can see where each answer goes. The names, addresses, dates and amounts are examples only.

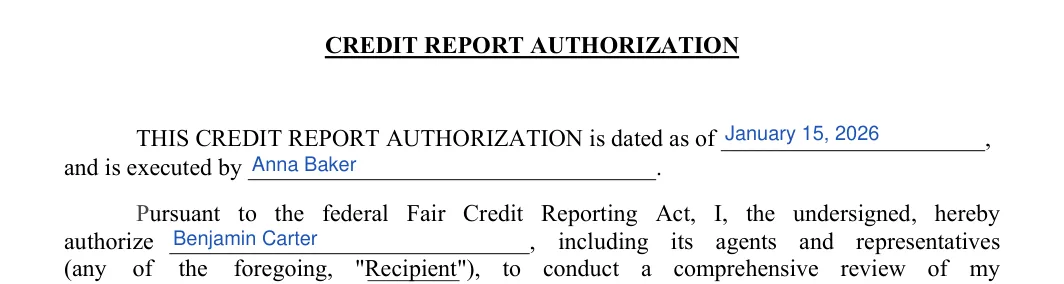

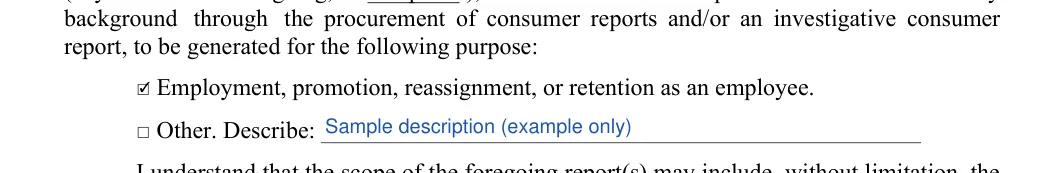


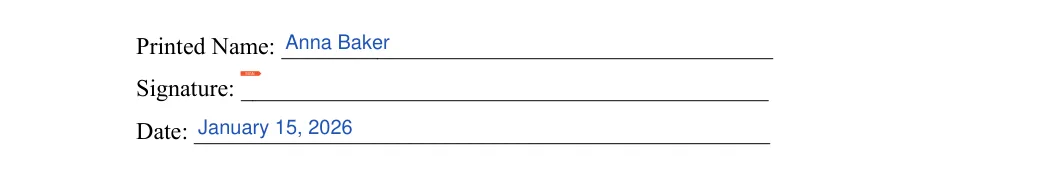
A signed credit check form is the first paper a landlord, lender or employer collects before ordering a report on another person from a consumer reporting agency.
Under 15 U.S.C. § 1681m, the adverse action notice can be oral, written or electronic. Under 15 U.S.C. § 1681m, the person who took the adverse action also gives the consumer a written or electronic disclosure of any numerical credit score used in that decision, among other items the section lists.
A credit report shows a person's loans, credit accounts, balances and payment history, including late or missed payments, and the requester sees only what that report holds.
Under 15 U.S.C. § 1681c, a consumer reporting agency leaves out adverse items of information that antedate the report by more than seven years, other than records of convictions of crimes. Under 15 U.S.C. § 1681c, a bankruptcy case drops off once it antedates the report by more than 10 years from the order for relief or the date of adjudication.
Under 15 U.S.C. § 1681c, these time limits do not apply to a report used for a credit transaction of $150,000 or more, for life insurance with a face amount of $150,000 or more, or for a job at an annual salary of $75,000 or more.
Not in every case: under 15 U.S.C. § 1681b, a consumer reporting agency may furnish a report on the consumer's written instructions or to a person with a permissible purpose, such as a credit transaction involving the consumer. For employment purposes, 15 U.S.C. § 1681b adds the standalone disclosure and the consumer's written authorization.
Yes: under 15 U.S.C. § 1681n, any person who willfully fails to comply with an FCRA requirement with respect to a consumer is liable to that consumer. Under 15 U.S.C. § 1681n, the damages are actual damages or damages of not less than $100 and not more than $1,000, plus punitive damages the court allows and, in a successful action, costs and reasonable attorney's fees. Under 15 U.S.C. § 1681n, a natural person who obtains a consumer report under false pretenses or knowingly without a permissible purpose is liable for actual damages or $1,000, whichever is greater.
A credit report centers on loans, credit accounts and payment history, while criminal history belongs to a criminal background check, a separate consumer report. Under 15 U.S.C. § 1681c, records of convictions of crimes fall outside the seven-year limit on adverse items, so a consumer report that covers criminal history can list older convictions. A background check consent form covers that kind of check.
Yes: under 15 U.S.C. § 1681j, a nationwide consumer reporting agency makes all disclosures once during any 12-month period upon request of the consumer and without charge to the consumer.
The signed form goes to the requester once a few checks are done:
General information, not legal or tax advice.
