
Updated:
Get Form Now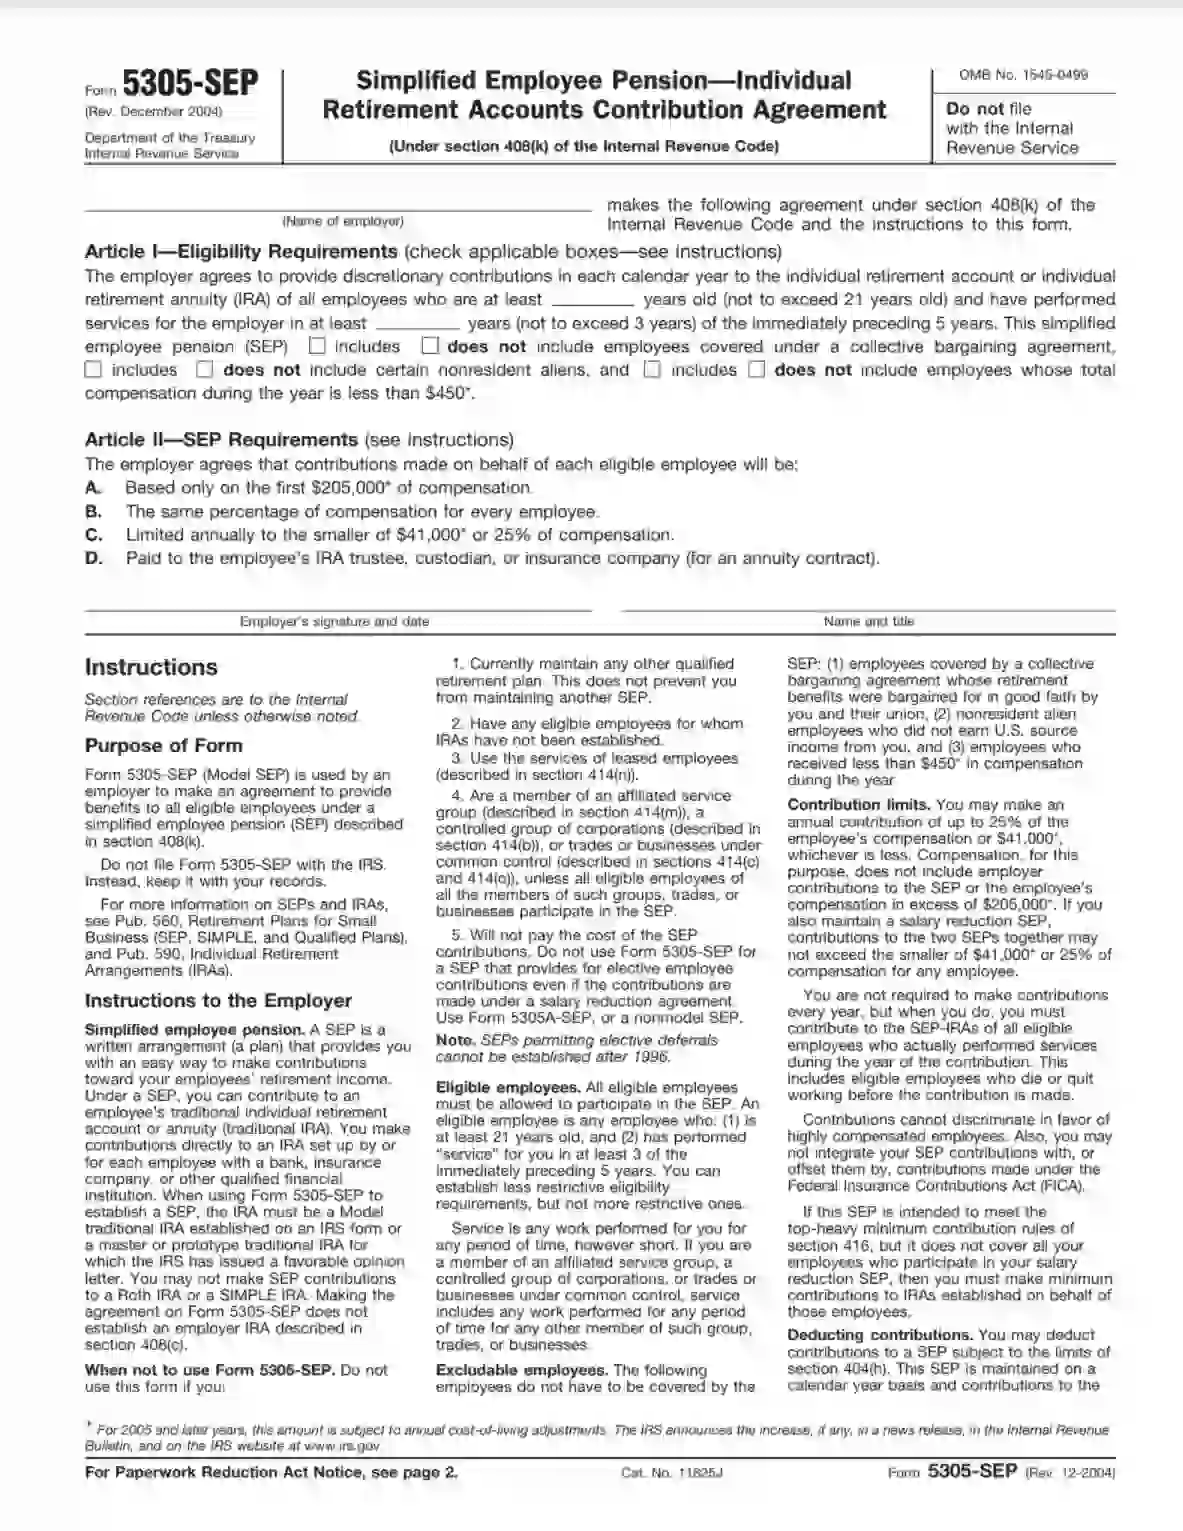
Form 5305-SEP is a standardized agreement offered by the Internal Revenue Service (IRS) to set up a Simplified Employee Pension (SEP) IRA plan. This form simplifies the process for small businesses that want to offer retirement savings options for their employees. By adopting it, employers establish the rules for employee participation, contribution amounts, and allocation methods.
Form 5305-SEP offers several advantages. It eliminates the need for employer-sponsored IRAs and simplifies filing requirements. However, there are limitations. Employers cannot use the form if they already have another qualified retirement plan or use leased employees. Additionally, contributions must follow a set formula and go into traditional IRAs set up by each employee.
Other IRS Forms for Business
Apart from the form for involving the pension plan in business, there are plenty of other forms every business should be familiar with.
What it is: Form 5305-SEP (Model SEP) is used by an employer to make an agreement to provide benefits to all eligible employees under a simplified employee pension (SEP) described in section 408(k).
Where and when to file: Do not file Form 5305-SEP with the IRS. Instead, keep it with your records.
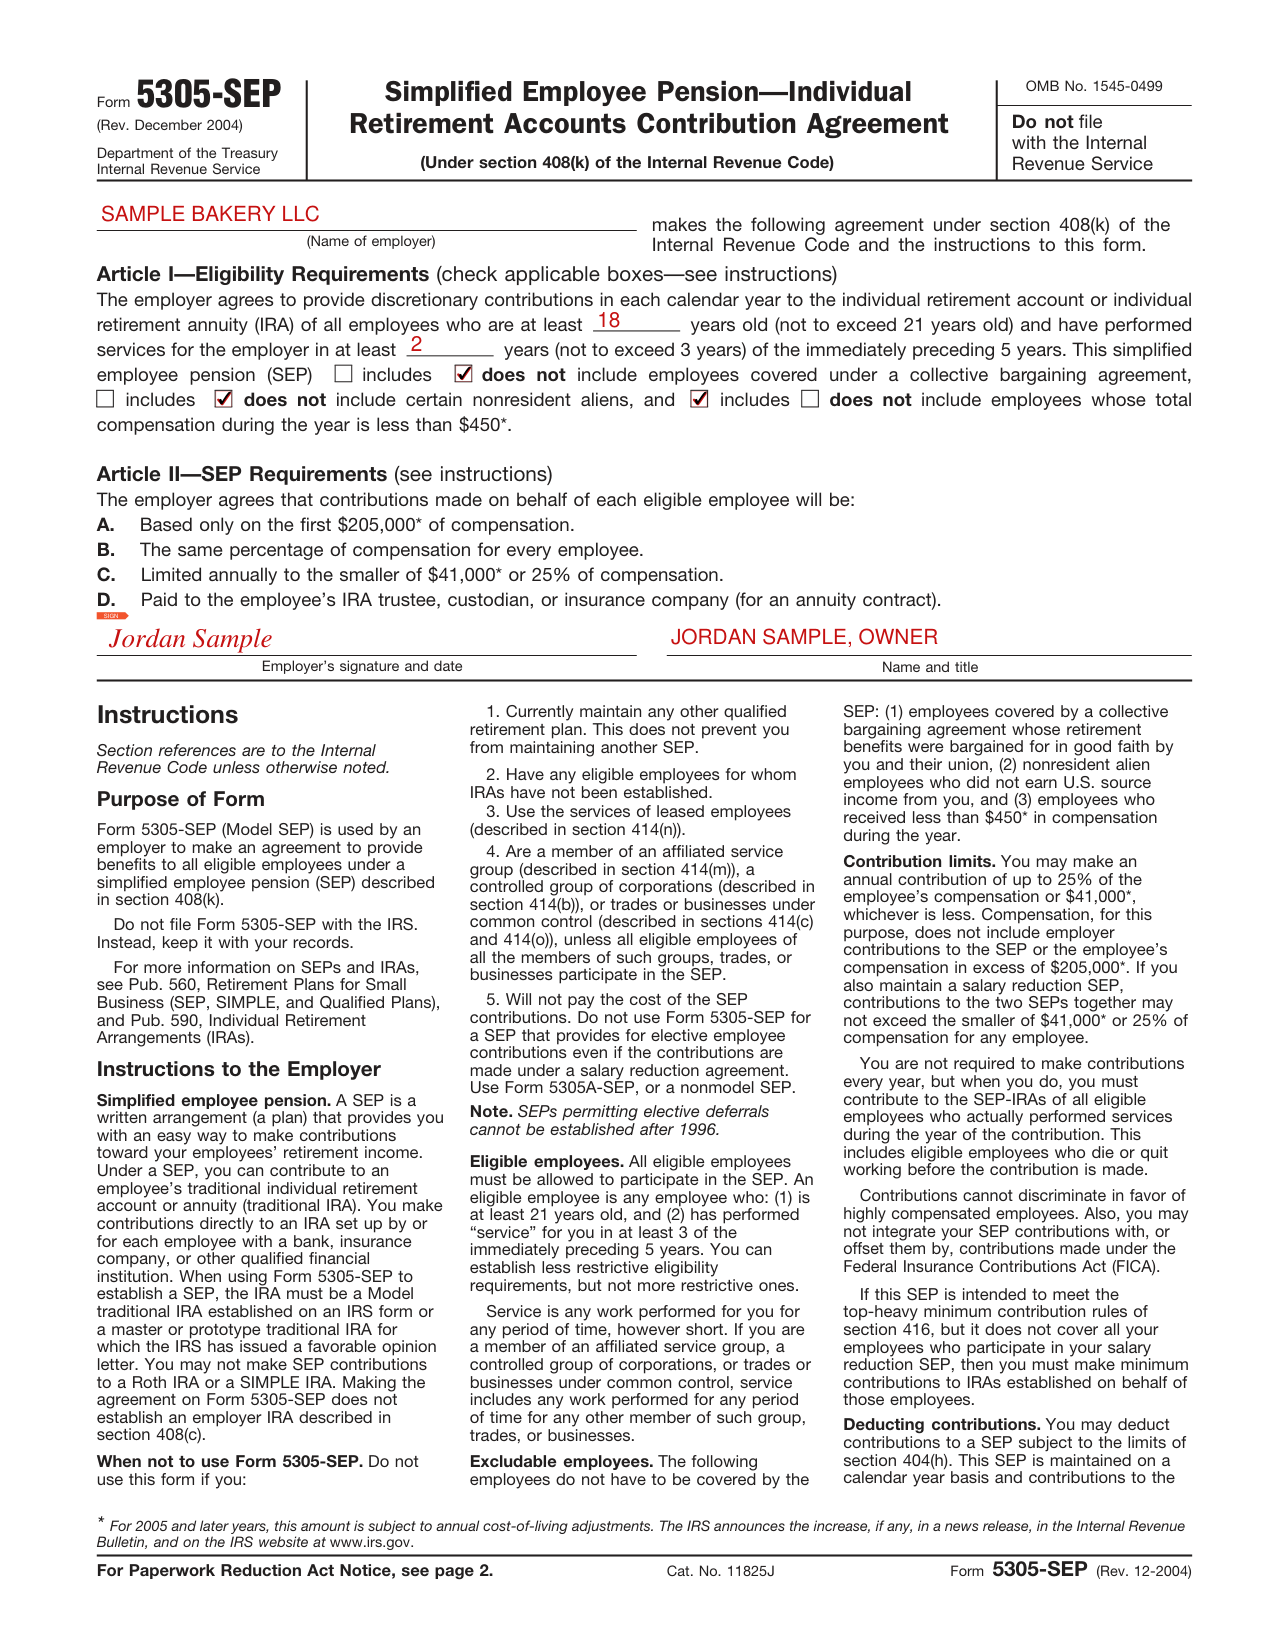

Enter the name of the employer, which makes the agreement under section 408(k) of the Internal Revenue Code and the instructions to this form.
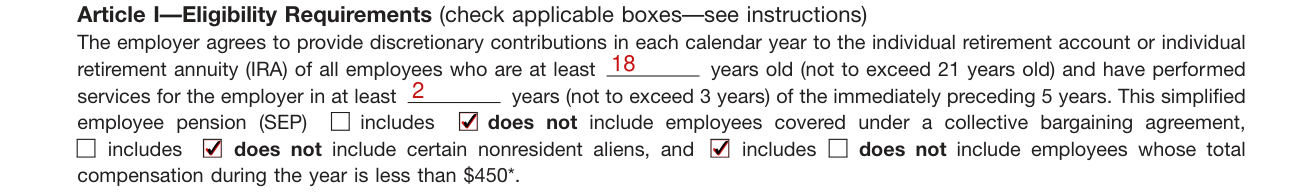
Check the applicable boxes in Article I, Eligibility Requirements.
Enter the age in the blank for all employees (not to exceed 21 years old).
Enter the years in the blank for employees who have performed services for the employer in at least years (not to exceed 3 years) of the immediately preceding 5 years.
All eligible employees must be allowed to participate in the SEP. An eligible employee is any employee who is at least 21 years old and has performed service for you in at least 3 of the immediately preceding 5 years. You can establish less restrictive eligibility requirements, but not more restrictive ones.
Service is any work performed for you for any period of time, however short. If you are a member of an affiliated service group, a controlled group of corporations, or trades or businesses under common control, service includes any work performed for any period of time for any other member of such group, trades, or businesses.
This simplified employee pension (SEP) includes or does not include employees covered under a collective bargaining agreement: check the box. You do not have to cover employees covered by a collective bargaining agreement whose retirement benefits were bargained for in good faith by you and their union.
This SEP includes or does not include certain nonresident aliens: check the box. You do not have to cover nonresident alien employees who did not earn U.S. source income from you.
The employer makes the agreement for this SEP, which includes or does not include employees whose total compensation during the year is less than $450*: check the box. You do not have to cover employees who received less than $450* in compensation during the year (checked October 29, 2026). For 2005 and later years, this amount is subject to annual cost-of-living adjustments.

Employer's signature and date: sign, then enter the name and title.
Article II-SEP Requirements. The employer agrees that contributions made on behalf of each eligible employee will be based only on the first $205,000* of compensation, the same percentage of compensation for every employee, limited annually to the smaller of $41,000* or 25% of compensation, and paid to the employee's IRA trustee, custodian, or insurance company (for an annuity contract) (checked October 29, 2026). For 2005 and later years, these amounts are subject to annual cost-of-living adjustments.
You are not required to make contributions every year, but when you do, you must contribute to the SEP-IRAs of all eligible employees who actually performed services during the year of the contribution. This includes eligible employees who die or quit working before the contribution is made.
Contributions cannot discriminate in favor of highly compensated employees. Also, you may not integrate your SEP contributions with, or offset them by, contributions made under the Federal Insurance Contributions Act (FICA).
This agreement is considered adopted when IRAs have been established for all your eligible employees, you have completed all blanks on the agreement form without modification, and you have given all your eligible employees: A copy of Form 5305-SEP. A statement that traditional IRAs other than the traditional IRAs into which employer SEP contributions will be made may provide different rates of return and different terms concerning, among other things, transfers and withdrawals of funds from the IRAs. A statement that, in addition to the information provided to an employee at the time the employee becomes eligible to participate, the administrator of the SEP must furnish each participant within 30 days of the effective date of any amendment to the SEP, a copy of the amendment and a written explanation of its effects. A statement that the administrator will give written notification to each participant of any employer contributions made under the SEP to that participant's IRA by the later of January 31 of the year following the year for which a contribution is made or 30 days after the contribution is made.
Contributions made for a particular tax year must be made by the due date of your income tax return (including extensions) for that tax year.
Do not file Form 5305-SEP with the IRS. Instead, keep it with your records.
Do not use Form 5305-SEP if you currently maintain any other qualified retirement plan. This does not prevent you from maintaining another SEP. Do not use it if you have any eligible employees for whom IRAs have not been established. Do not use it if you use the services of leased employees (described in section 414(n)). Do not use it if you are a member of an affiliated service group (described in section 414(m)), a controlled group of corporations (described in section 414(b)), or trades or businesses under common control (described in sections 414(c) and 414(o)), unless all eligible employees of all the members of such groups, trades, or businesses participate in the SEP. Do not use it if you will not pay the cost of the SEP contributions. Do not use Form 5305-SEP for a SEP that provides for elective employee contributions even if the contributions are made under a salary reduction agreement. Use Form 5305A-SEP, or a nonmodel SEP. Note. SEPs permitting elective deferrals cannot be established after 1996.
[1] Form 5305-SEP (Rev. December 2004), Simplified Employee Pension-Individual Retirement Accounts Contribution Agreement, Internal Revenue Service (the Official source link on this page).