
Updated:
Get Form Now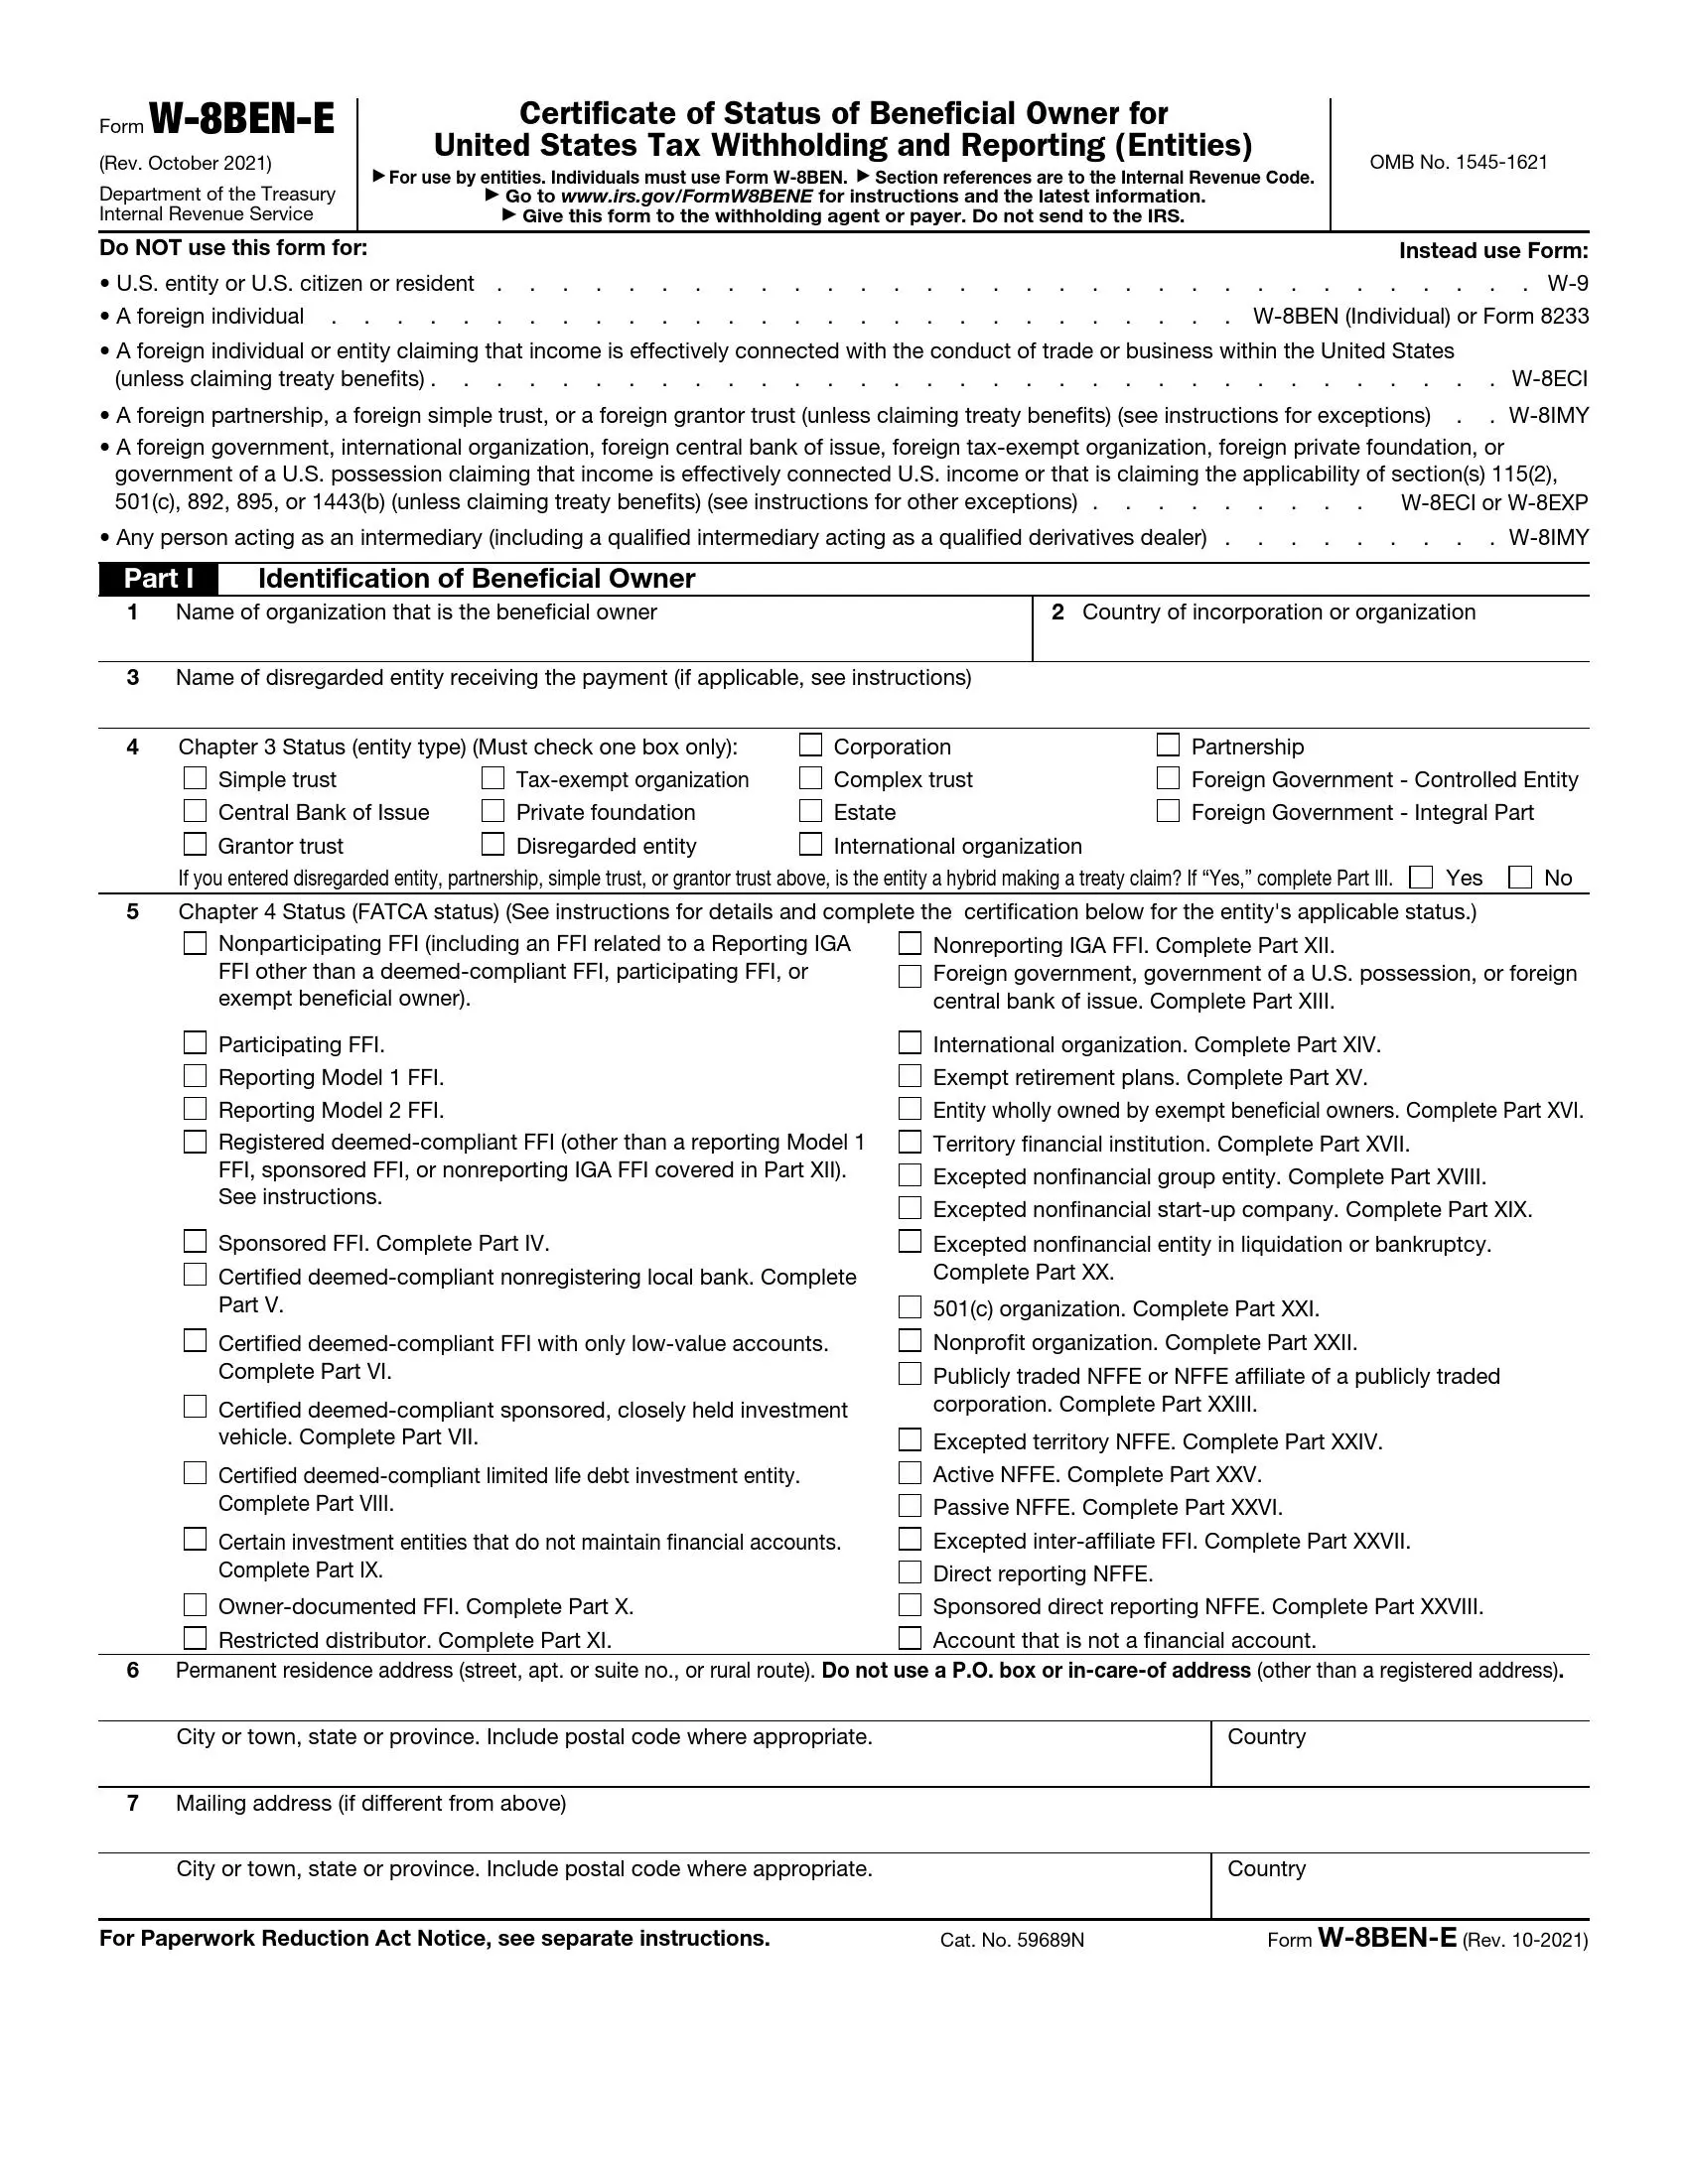
IRS Form W-8BEN-E is a tax form foreign entities use to certify their status as non-U.S. entities. This form is part of the tax compliance measures related to withholding on U.S. source income paid to foreign entities. Form W-8BEN-E documents their status for certain tax treaty benefits or claims exemption from certain U.S. information reporting and withholding.
The primary purpose of Form W-8BEN-E is to establish that a foreign entity is the beneficial owner of the income for which the form is being provided and to indicate whether a reduced rate of or exemption from U.S. withholding tax is justified under U.S. tax laws or a tax treaty between the foreign entity’s country of residence and the United States. It is essential for entities engaging in financial transactions involving U.S. source income to ensure compliance with international taxation’s complex regulations and prevent unnecessary withholding obligations
Other IRS Forms for Corporations
Foreign people in the US might need to be familiar with some other IRS forms. You can read more about them on other pages with IRS forms.
What it is: Form W-8BEN-E is the Certificate of Status of Beneficial Owner for United States Tax Withholding and Reporting (Entities).
Who signs: Signature of individual authorized to sign for beneficial owner. Certify that you have the capacity to sign for the entity identified on line 1 of this form.
For use by entities. Individuals must use Form W-8BEN. Give this form to the withholding agent or payer. Do not send to the IRS.
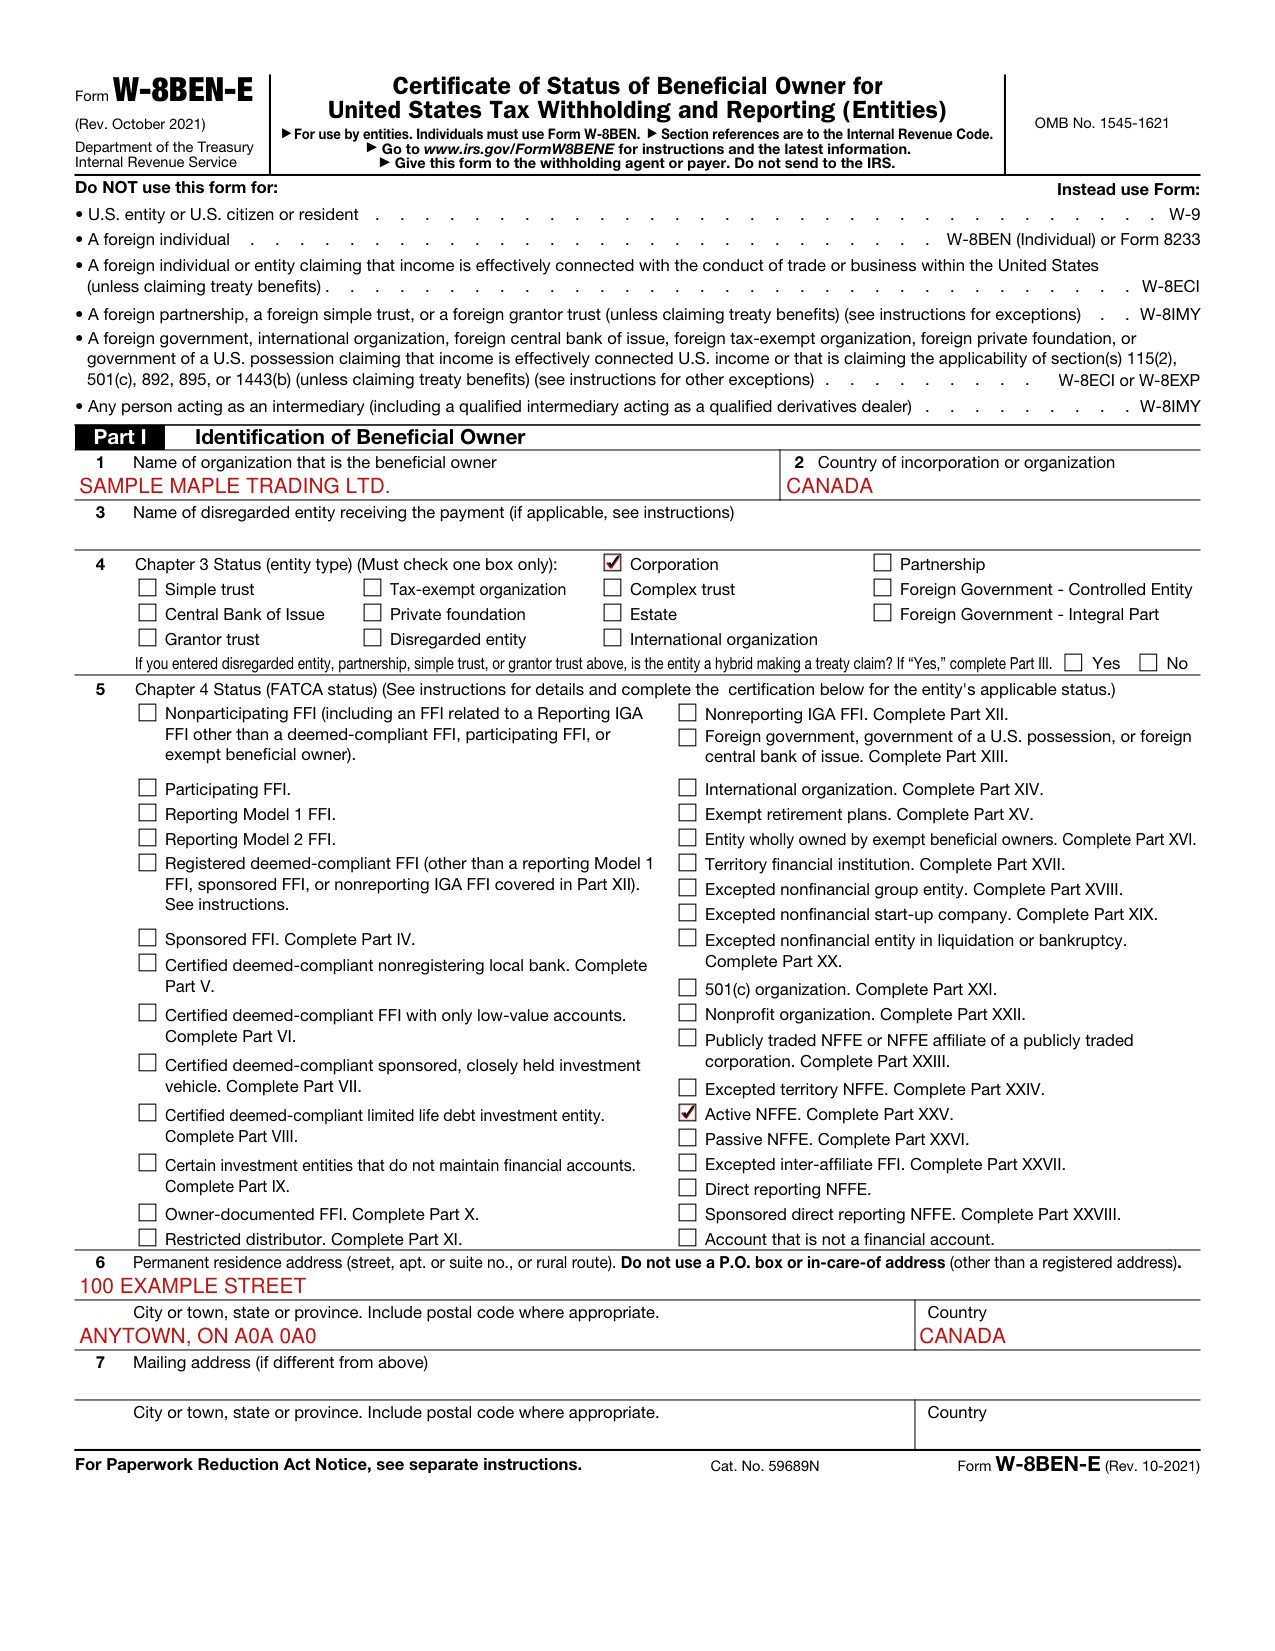
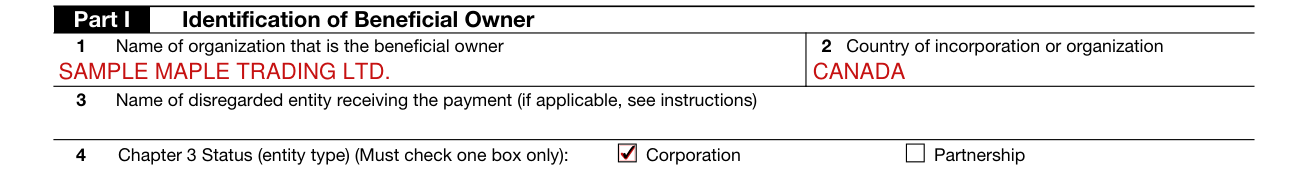
Part I Identification of Beneficial Owner: enter 1 Name of organization that is the beneficial owner, 2 Country of incorporation or organization and 3 Name of disregarded entity receiving the payment (if applicable, see instructions).
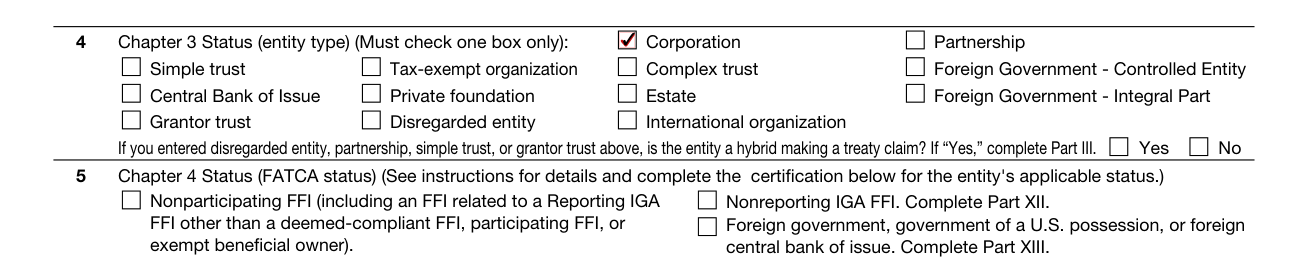
In 4 Chapter 3 Status (entity type), check one box only: Corporation, Partnership, Simple trust, Tax-exempt organization, Complex trust, Foreign Government - Controlled Entity, Central Bank of Issue, Private foundation, Estate, Foreign Government - Integral Part, Grantor trust, Disregarded entity or International organization. If you entered disregarded entity, partnership, simple trust, or grantor trust in 4 Chapter 3 Status, is the entity a hybrid making a treaty claim? If “Yes,” complete Part III. Check Yes or No.
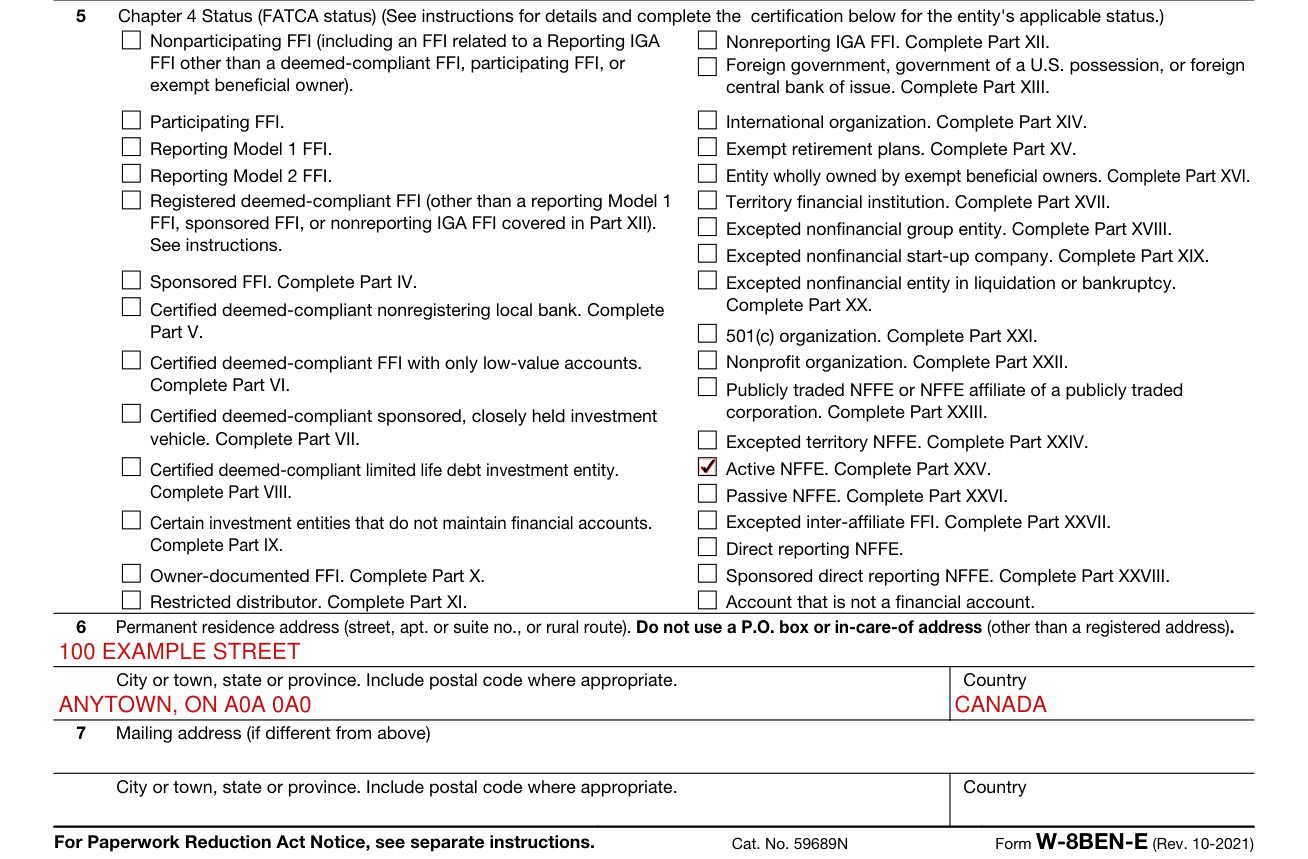
In 5 Chapter 4 Status (FATCA status), complete the certification for the entity's applicable status (see instructions for details).
Active NFFE. Complete Part XXV. Passive NFFE. Complete Part XXVI. Excepted inter-affiliate FFI. Complete Part XXVII.
Publicly traded NFFE or NFFE affiliate of a publicly traded corporation. Complete Part XXIII.
Excepted territory NFFE. Complete Part XXIV.
501(c) organization. Complete Part XXI. Nonprofit organization. Complete Part XXII.
Direct reporting NFFE. Sponsored direct reporting NFFE. Complete Part XXVIII. Account that is not a financial account. In 6 Permanent residence address (street, apt. or suite no., or rural route), do not use a P.O. box or in-care-of address (other than a registered address); enter City or town, state or province, include postal code where appropriate, and Country. In 7 Mailing address (if different from the permanent residence address), enter City or town, state or province, include postal code where appropriate, and Country.
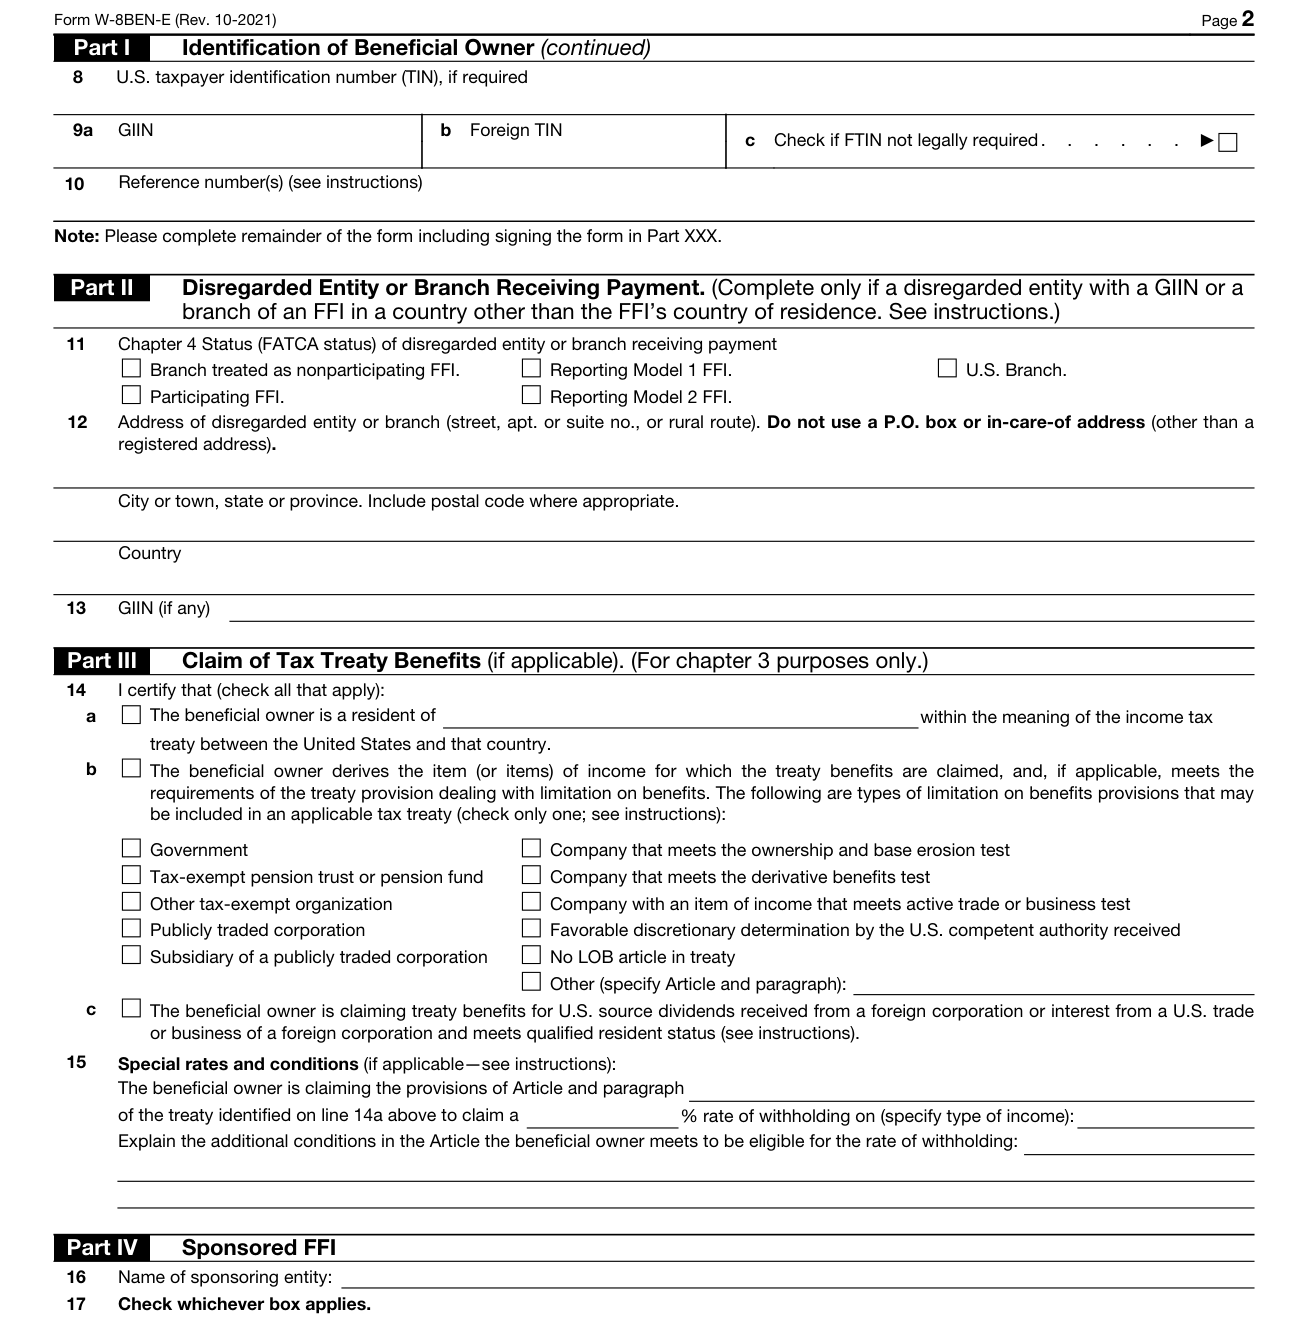
Part I Identification of Beneficial Owner (continued): 8 U.S. taxpayer identification number (TIN), if required
9a GIIN b Foreign TIN c Check if FTIN not legally required.
10 Reference number(s) (see instructions). Note: Please complete remainder of the form including signing the form in Part XXX.
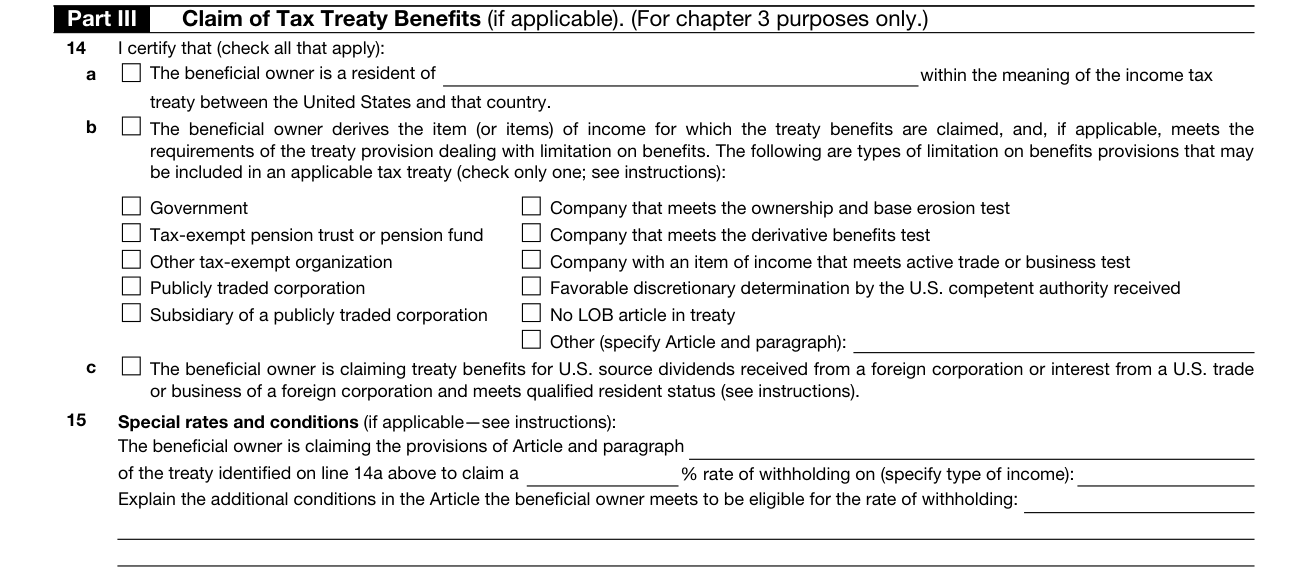
Part III Claim of Tax Treaty Benefits (if applicable). (For chapter 3 purposes only.)
14 I certify that (check all that apply): a The beneficial owner is a resident of within the meaning of the income tax treaty between the United States and that country. b The beneficial owner derives the item (or items) of income for which the treaty benefits are claimed, and, if applicable, meets the requirements of the treaty provision dealing with limitation on benefits.
The following are types of limitation on benefits provisions that may be included in an applicable tax treaty (check only one; see instructions):
Government. Company that meets the ownership and base erosion test. Tax-exempt pension trust or pension fund Other tax-exempt organization Publicly traded corporation. Company that meets the derivative benefits test Company with an item of income that meets active trade or business test Favorable discretionary determination by the U.S. competent authority received. Subsidiary of a publicly traded corporation.
No LOB article in treaty Other (specify Article and paragraph): c The beneficial owner is claiming treaty benefits for U.S. source dividends received from a foreign corporation or interest from a U.S. trade or business of a foreign corporation and meets qualified resident status (see instructions).
15 Special rates and conditions (if applicable-see instructions): The beneficial owner is claiming the provisions of Article and paragraph of the treaty identified on line 14a above to claim a % rate of withholding on (specify type of income): Explain the additional conditions in the Article the beneficial owner meets to be eligible for the rate of withholding:

Part XXV Active NFFE: 39 I certify that:
The entity identified in Part I is a foreign entity that is not a financial institution; less than 50% of such entity's gross income for the preceding calendar year is passive income; and less than 50% of the assets held by such entity are assets that produce or are held for the production of passive income (calculated as a weighted average of the percentage of passive assets measured quarterly) (see instructions for the definition of passive income).
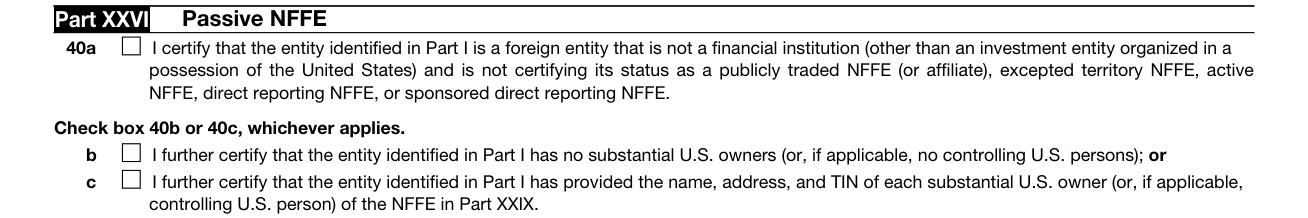
Part XXVI Passive NFFE: 40a I certify that the entity identified in Part I is a foreign entity that is not a financial institution (other than an investment entity organized in a possession of the United States) and is not certifying its status as a publicly traded NFFE (or affiliate), excepted territory NFFE, active NFFE, direct reporting NFFE, or sponsored direct reporting NFFE.
Check box 40b or 40c, whichever applies. b I further certify that the entity identified in Part I has no substantial U.S. owners (or, if applicable, no controlling U.S. persons); or c I further certify that the entity identified in Part I has provided the name, address, and TIN of each substantial U.S. owner (or, if applicable, controlling U.S. person) of the NFFE in Part XXIX.
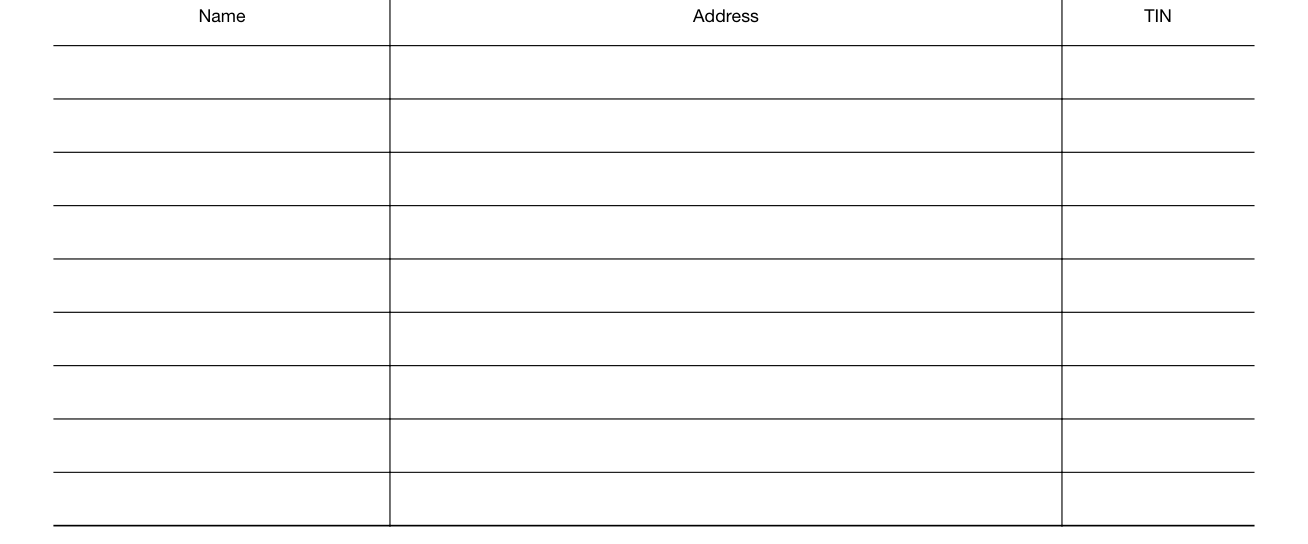
Part XXIX Substantial U.S. Owners of Passive NFFE: as required by Part XXVI, provide the name, address, and TIN of each substantial U.S. owner of the NFFE. Please see the instructions for a definition of substantial U.S. owner. Name Address TIN
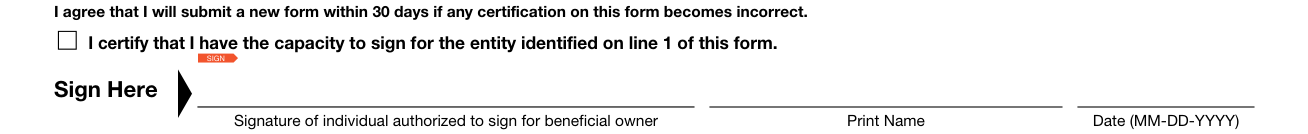
Part XXX Certification. By signing you certify that, under penalties of perjury, you have examined the information on this form and to the best of your knowledge and belief it is true, correct, and complete.
I further certify under penalties of perjury that: the entity identified on line 1 of this form is the beneficial owner of all the income or proceeds to which this form relates, is using this form to certify its status for chapter 4 purposes, or is submitting this form for purposes of section 6050W or 6050Y; the entity identified on line 1 of this form is not a U.S. person; this form relates to: (a) income not effectively connected with the conduct of a trade or business in the United States, (b) income effectively connected with the conduct of a trade or business in the United States but is not subject to tax under an income tax treaty, (c) the partner's share of a partnership's effectively connected taxable income, or (d) the partner's amount realized from the transfer of a partnership interest subject to withholding under section 1446(f); and for broker transactions or barter exchanges, the beneficial owner is an exempt foreign person as defined in the instructions.
Furthermore, I authorize this form to be provided to any withholding agent that has control, receipt, or custody of the income of which the entity on line 1 is the beneficial owner or any withholding agent that can disburse or make payments of the income of which the entity on line 1 is the beneficial owner.
I agree that I will submit a new form within 30 days if any certification on this form becomes incorrect.
By signing you certify that you have the capacity to sign for the entity identified on line 1 of this form. Sign Here: Signature of individual authorized to sign for beneficial owner, Print Name, Date (MM-DD-YYYY)
Do NOT use this form for a U.S. entity or U.S. citizen or resident (use Form W-9) or a foreign individual (use W-8BEN (Individual) or Form 8233). Do NOT use this form for a foreign individual or entity claiming that income is effectively connected with the conduct of trade or business within the United States (unless claiming treaty benefits): use Form W-8ECI. Do NOT use this form for a foreign partnership, a foreign simple trust, or a foreign grantor trust (unless claiming treaty benefits) (see instructions for exceptions): use Form W-8IMY.
[1] Form W-8BEN-E (Rev. October 2021), Certificate of Status of Beneficial Owner for United States Tax Withholding and Reporting (Entities), Department of the Treasury Internal Revenue Service (the Official source link on this page).