
Updated:
Get Form Now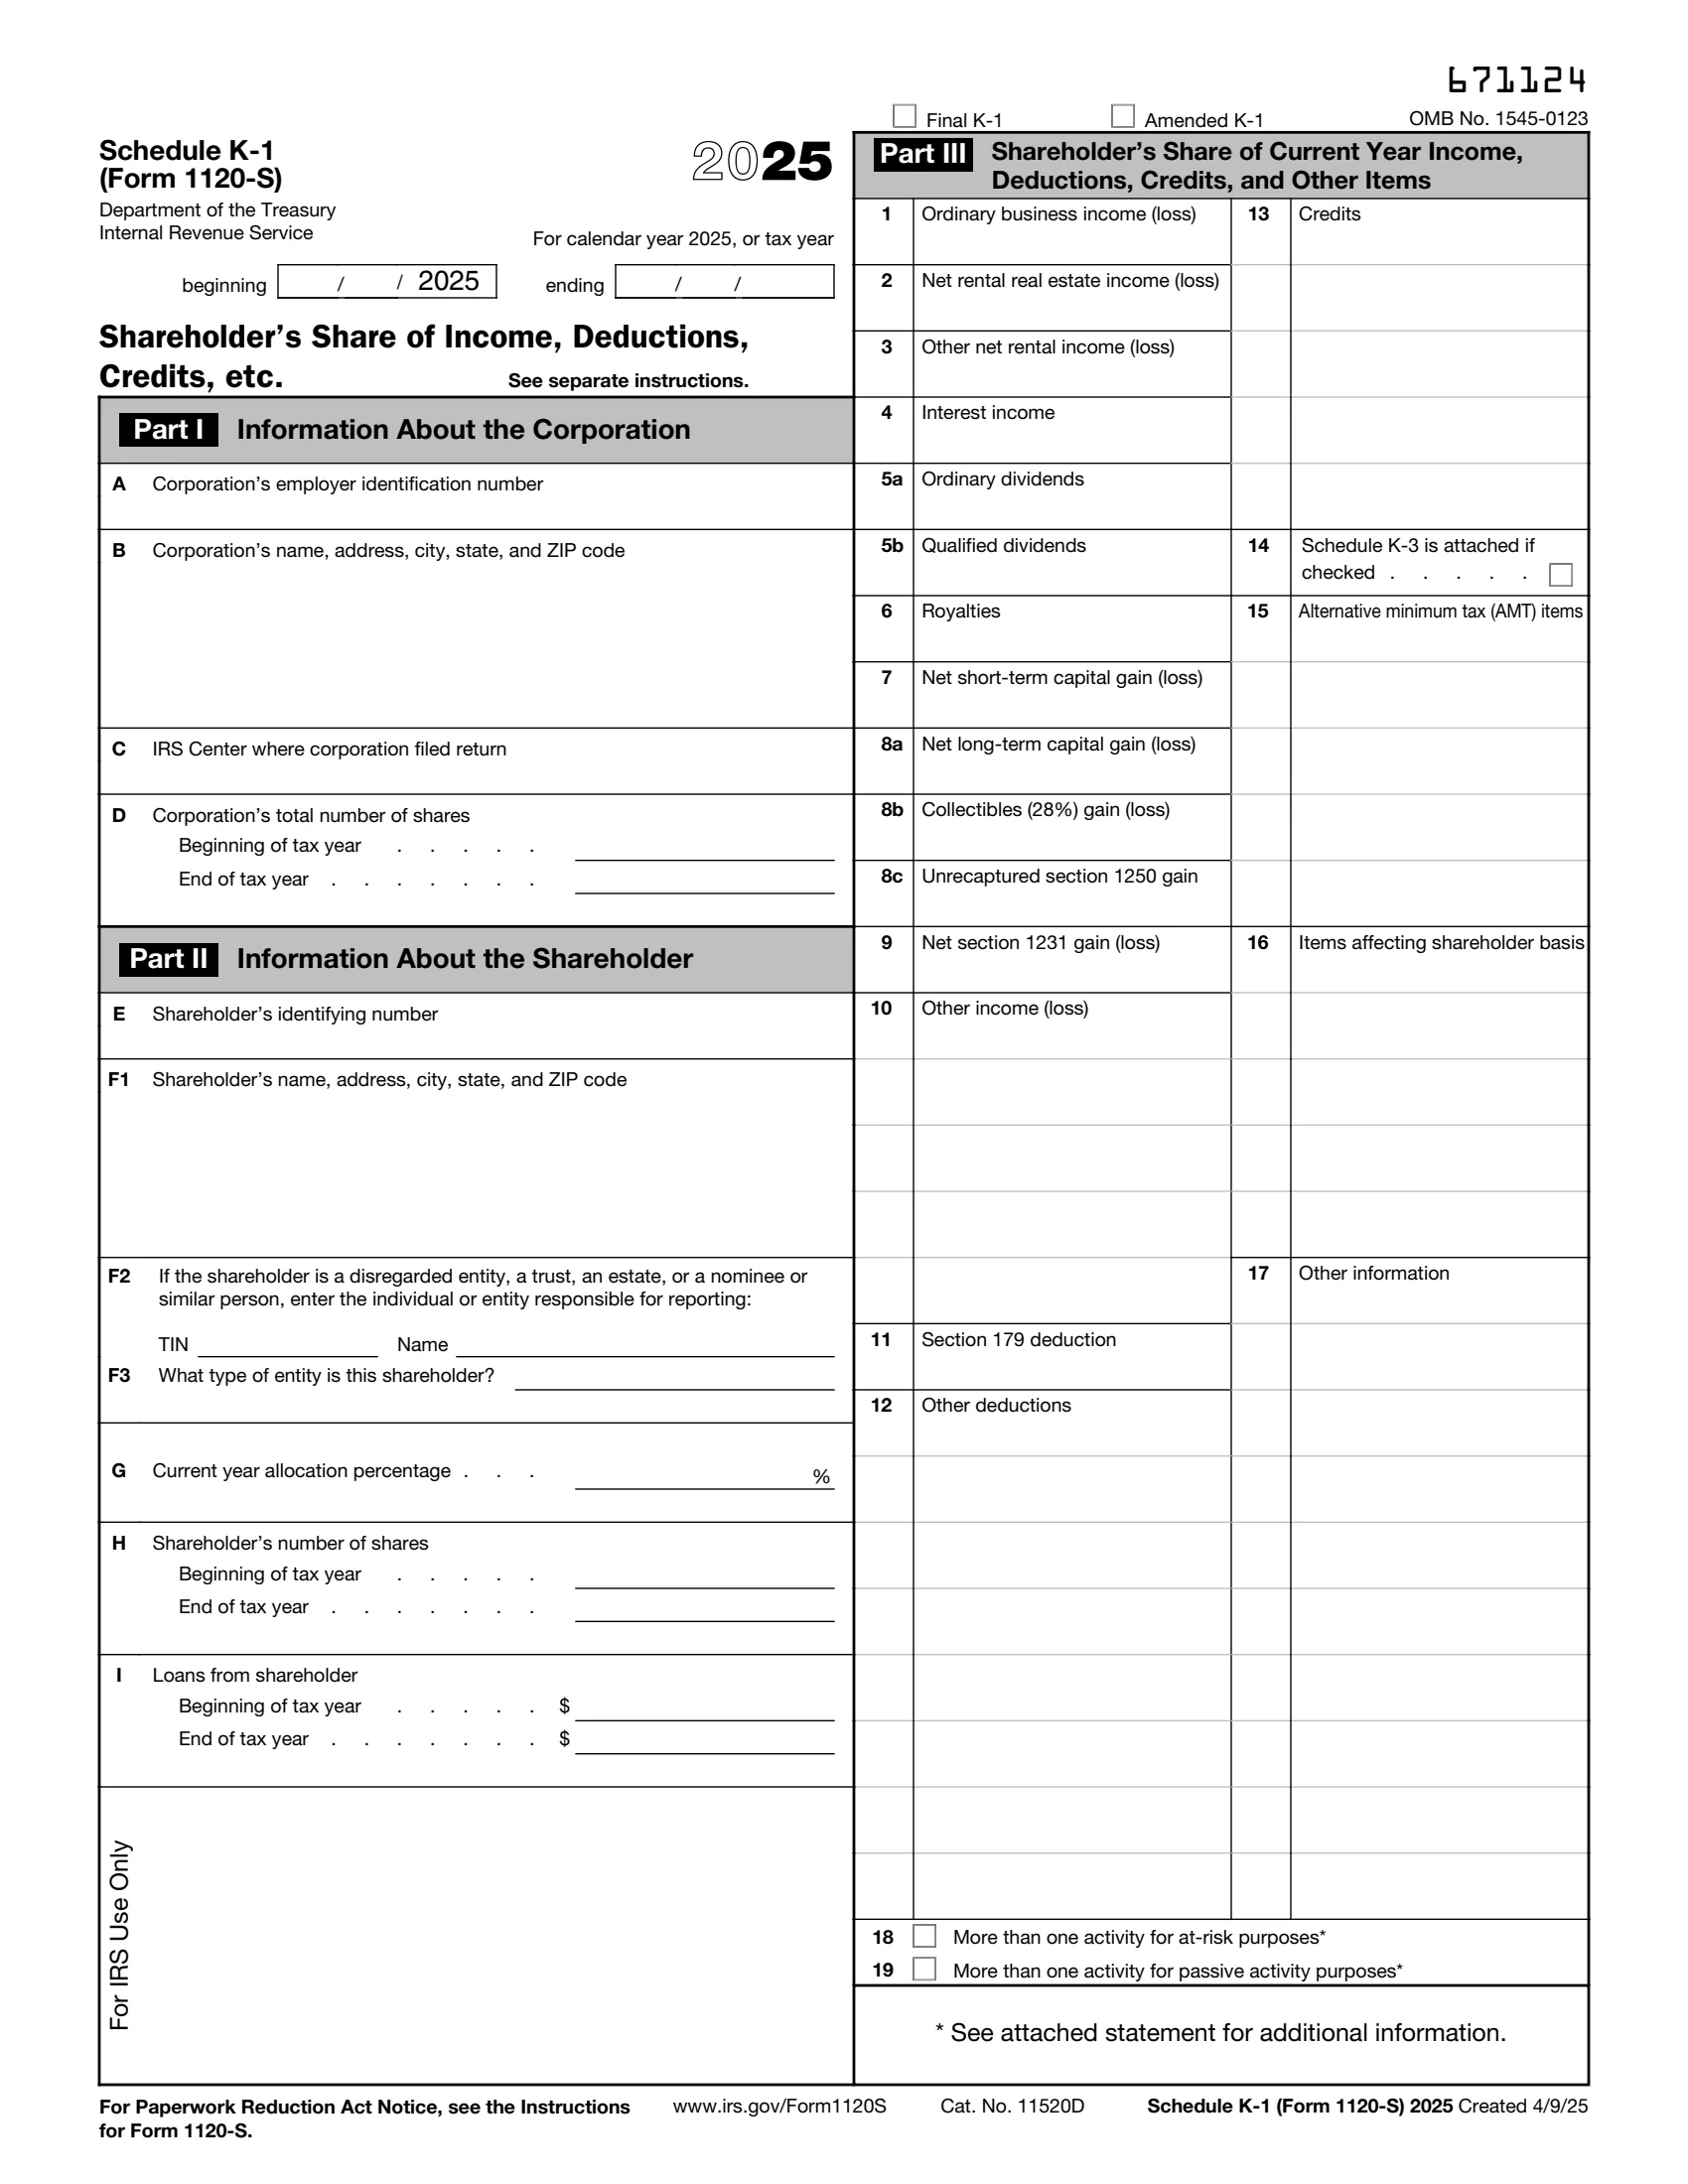
IRS Schedule K-1 (Form 1120-S) is a document used to report each shareholder’s share of income, deductions, credits, and other items from an S corporation. This form is an essential part of the S corporation’s tax filing. It provides necessary information for shareholders to correctly report their share of the corporation’s income or loss on their individual tax returns. Each shareholder’s Schedule K-1 includes this information:
The purpose of Schedule K-1 is to ensure that the income from the S corporation is reported once at the shareholder level, maintaining the S corporation’s flow-through nature. This helps avoid double taxation and allows shareholders to account for their respective shares of the corporation’s financial activities in their personal tax calculations.
Other IRS Forms for Corporations
The Schedule is devised to report vital information to the US Internal Revenue Service. Check what other essential details the IRS expects from corporations.
What it is: Schedule K-1 (Form 1120-S) 2025 is the Shareholder's Share of Current Year Income, Deductions, Credits, and Other Items.
Where and when to file: The corporation files a copy of Schedule K-1 with the IRS.[2]
The corporation uses Schedule K-1 to report your share of the corporation's income, deductions, credits, and other items.[2]
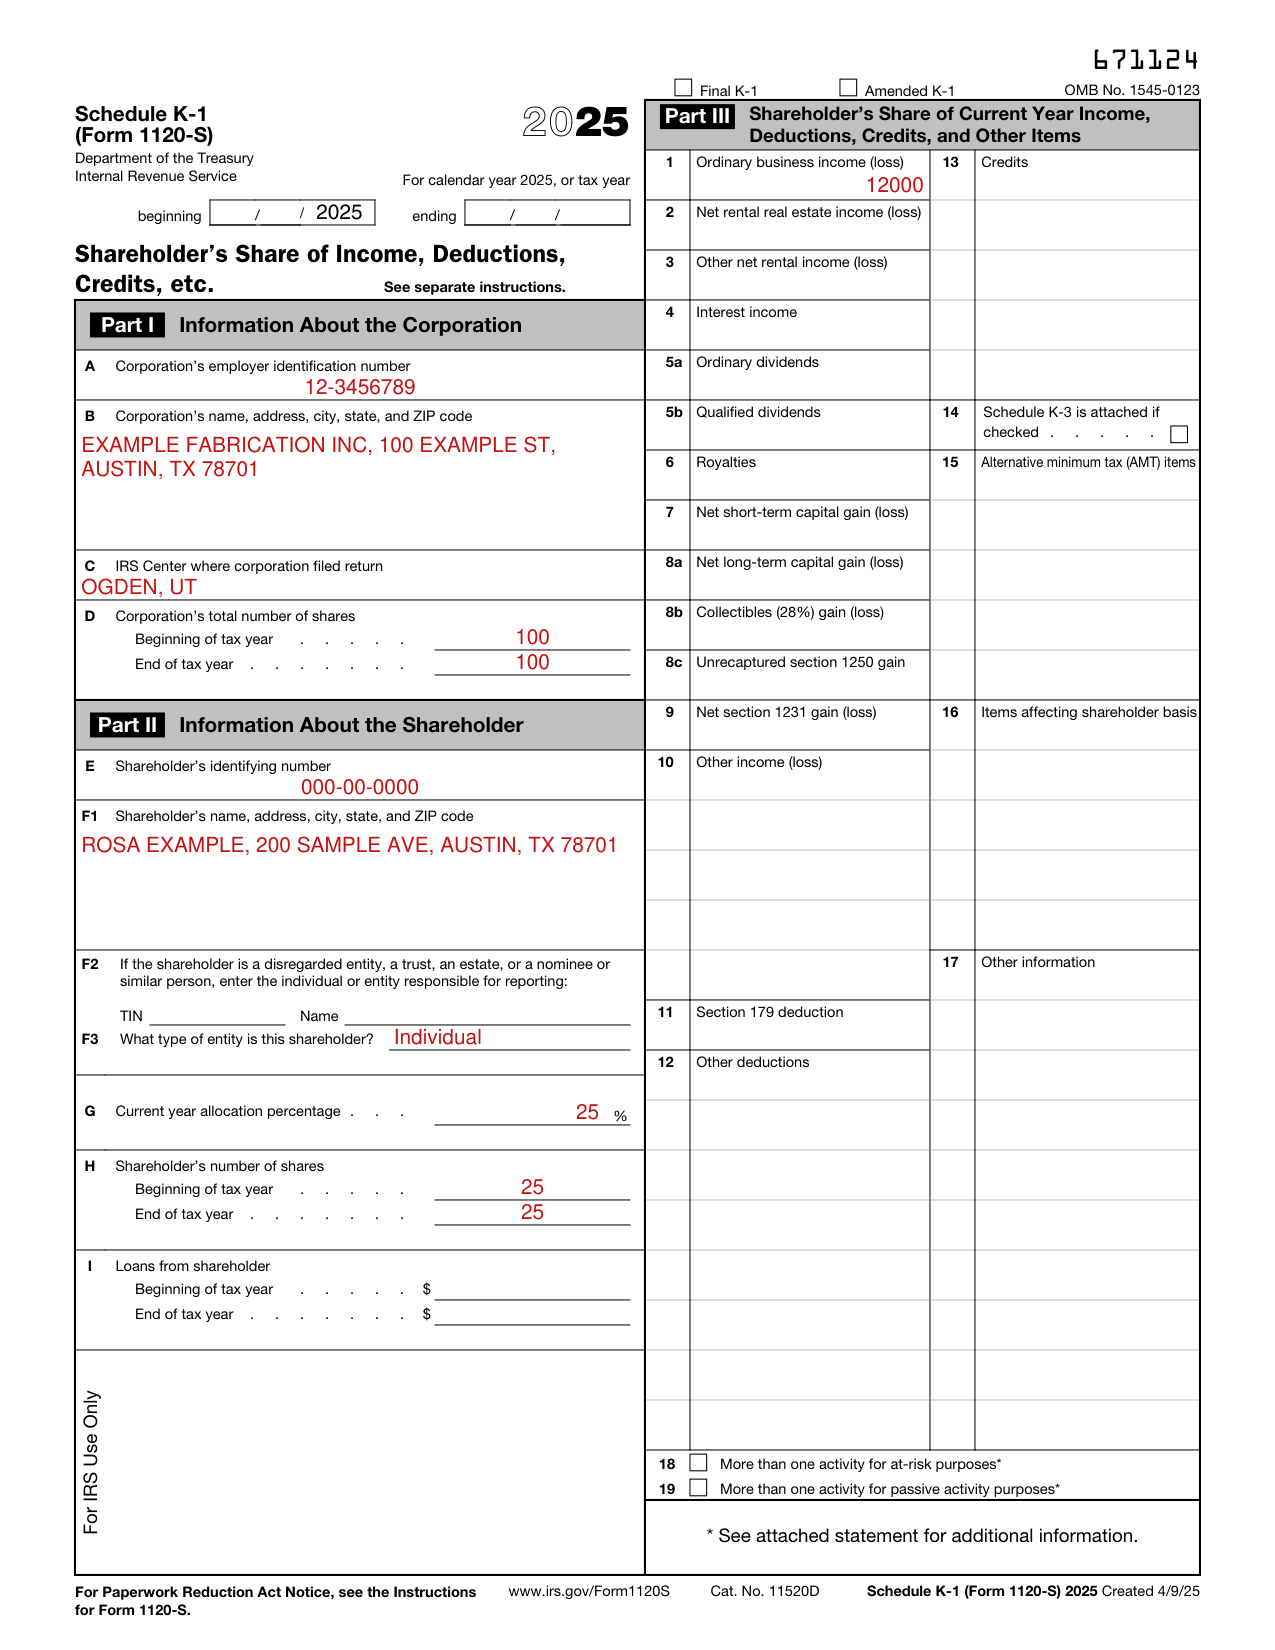
The amount reported in box 1 is your share of the ordinary income (loss) from trade or business activities of the corporation.
If you are an individual shareholder filing a 2025 Form 1040 or 1040-SR, report box 1 income (loss) from corporate trade or business activities in which you materially participated in column (i) or (k) of Schedule E (Form 1040), line 28, after applying the basis and at-risk limitations on losses.
Box 1 income (loss) from corporate trade or business activities in which you didn't materially participate: if a loss is reported in box 1, follow the Instructions for Form 8582 to figure how much of the loss can be reported in column (g) of Schedule E (Form 1040), line 28.
Box 1 income (loss) from corporate trade or business activities in which you didn't materially participate: if income is reported in box 1, report the income in column (h) of Schedule E (Form 1040), line 28.
Box 2, Net Rental Real Estate Income (Loss): generally, the income (loss) reported in box 2 is a passive activity amount for all shareholders.
If you have income from a passive activity in box 2, report the income in column (h) of Schedule E (Form 1040), line 28.
The amount in box 3 is a passive activity amount for all shareholders.
After applying the limitations on losses and deductions, report the income or loss as follows: if box 3 is a loss, follow the Instructions for Form 8582 to figure how much of the loss can be reported in column (g) of Schedule E (Form 1040), line 28.
After applying the limitations on losses and deductions, report the income or loss as follows: if income is reported in box 3, report the income in column (h) of Schedule E (Form 1040), line 28.[2]
Portfolio income or loss (shown in boxes 4 through 8b and in box 10, code A) isn't subject to the passive activity limitations.
Box 4, Interest Income: report interest income on Form 1040 or 1040-SR, line 2b.
Box 5a, Ordinary Dividends: report ordinary dividends on Form 1040 or 1040-SR, line 3b.
Box 7, Net Short-Term Capital Gain (Loss): after applying the limitations on losses and deductions, report the net short-term capital gain (loss) on Schedule D (Form 1040), Capital Gains and Losses, line 5.
Box 8a, Net Long-Term Capital Gain (Loss): after applying the limitations on losses and deductions, report the net long-term capital gain (loss) on Schedule D (Form 1040), line 12.[2]
Box 11, Section 179 Deduction: use this amount, along with the total cost of section 179 property placed in service during the year from other sources, to complete Part I of Form 4562, Depreciation and Amortization.
Box 13, Code O, Backup withholding: this is your share of the credit for backup withholding on dividends, interest income, and other types of income. Include this amount in the total you enter on Form 1040 or 1040-SR, line 25c, and attach a copy of your Schedule K-1 to your tax return.
Box 16, Code A, Tax-exempt interest income: individual shareholders include this amount on Form 1040 or 1040-SR, line 2a.
Box 17, Code A, Investment income: report this amount on Form 4952, line 4a.
Box 17, Code B, Investment expenses: report this amount on Form 4952, line 5.[2]
Box 18, More Than One Activity for At-Risk Purposes: when the corporation has more than one activity for at-risk purposes, it will check this box and attach a statement.
Box 19, More Than One Activity for Passive Activity Purposes: when the corporation has more than one activity for passive activity purposes, it will check this box and attach a statement.[2]
Your share of S corporation income isn't self-employment income and it isn't subject to self-employment tax.[2]
Schedule K-1 doesn't show actual dividend distributions the corporation made to you.[2]
Keep it for your records. Don't file it with your tax return unless backup withholding is reported in box 13 using code O.
Include your share on your tax return if a return is required.[2]
If you believe the corporation has made an error on your Schedule K-1, notify the corporation and ask for a corrected Schedule K-1.
Don't change any items on your copy of Schedule K-1.[2]
Generally, you must report corporate items shown on your Schedule K-1 (and any attached statements) the same way that the corporation treated the items on its return.
If the treatment on your original or amended return is inconsistent with the corporation's treatment, or if the corporation hasn't filed a return, file Form 8082, Notice of Inconsistent Treatment or Administrative Adjustment Request (AAR), with your original or amended return to identify and explain any inconsistency (or to note that a corporate return hasn't been filed).
If you are required to file Form 8082 but don't do so, you may be subject to the accuracy-related penalty.[2]
The amount of loss and deduction you may claim on your tax return may be less than the amount reported on Schedule K-1.[2]
You may be liable for tax on your share of the corporation's income, whether or not distributed.[2]
[1] Schedule K-1 (Form 1120-S) 2025, Internal Revenue Service (the Official source link on this page).
[2] 2025 Shareholder's Instructions for Schedule K-1 (Form 1120-S), Internal Revenue Service.