
Updated:
Get Form Now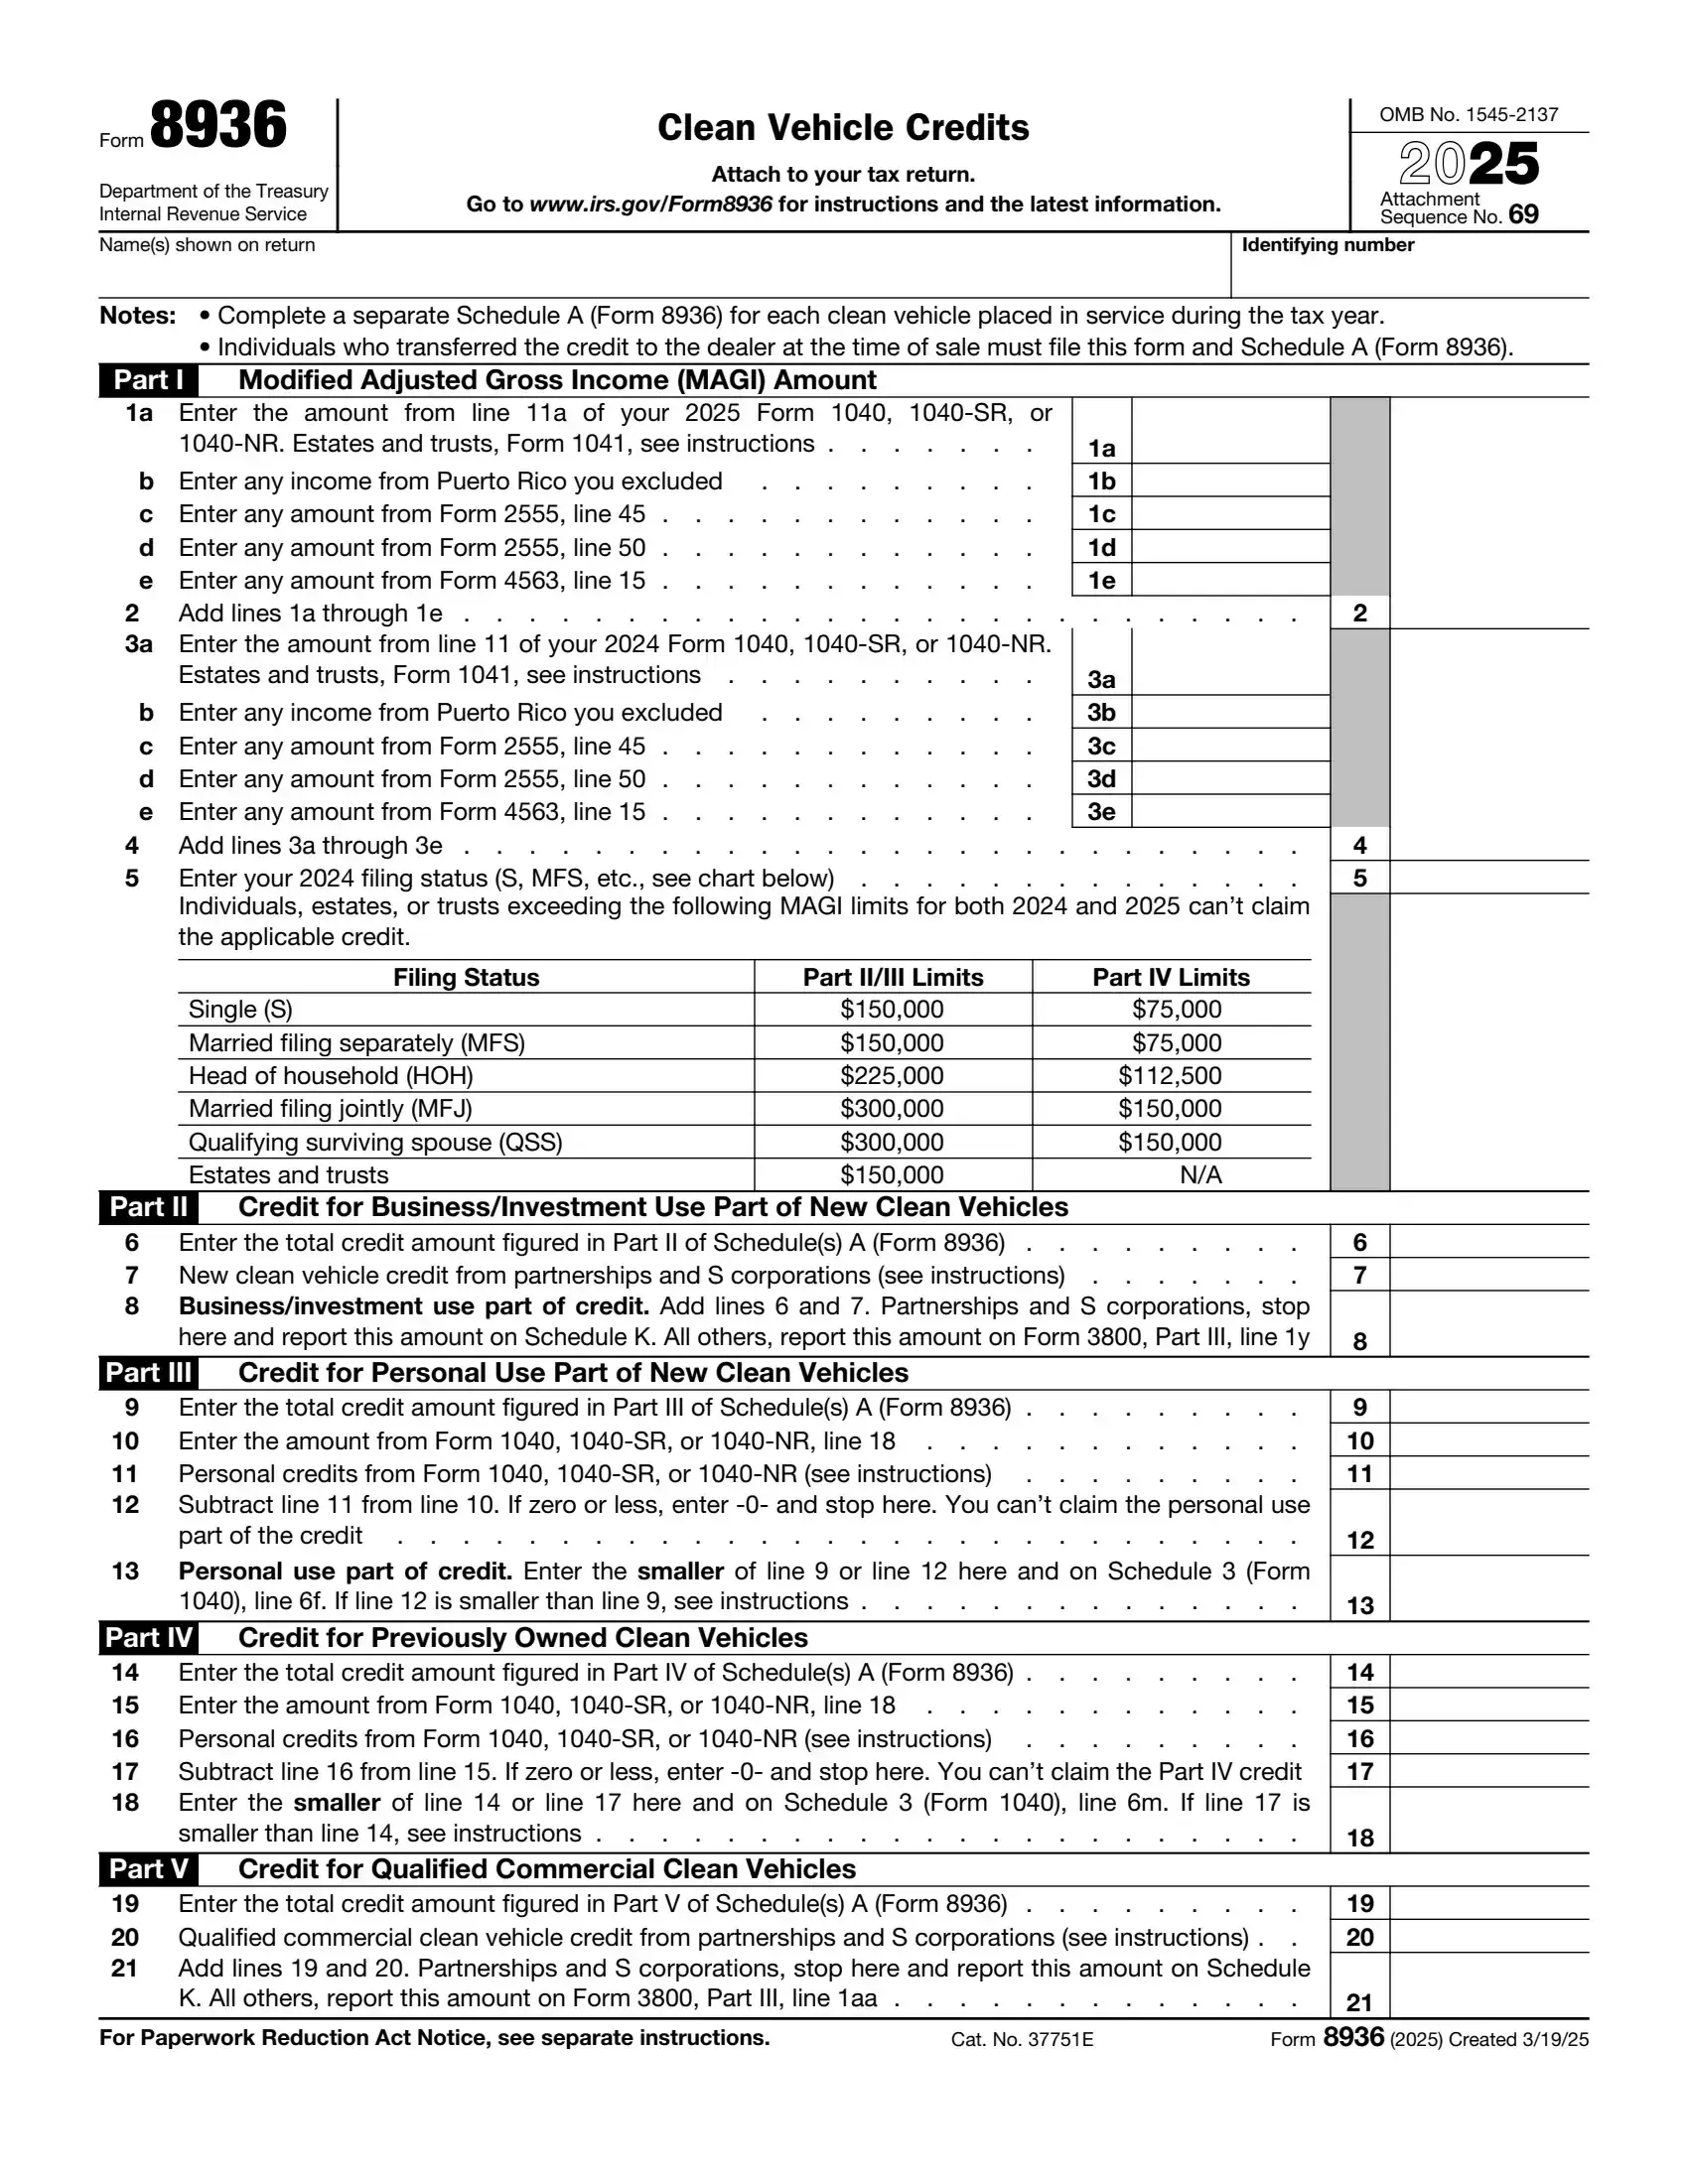
IRS Form 8936, titled “Clean Vehicle Credits,” is the form taxpayers use to claim the credit for a new clean vehicle, a previously owned clean vehicle, or a qualified commercial clean vehicle; under the 2025 tax law the credits are not available for vehicles acquired after September 30, 2025. This credit is part of an incentive program to encourage the adoption of environmentally friendly vehicles. It applies to vehicles with a battery that powers the propulsion system and has a capacity of at least 7 kilowatt hours. The form requires the following details to calculate the credit:
Taxpayers must also specify whether the vehicle is for business or personal use, as this affects the credit calculation. Form 8936 helps determine the credit amount, up to $7,500 for a new clean vehicle and up to $4,000 for a previously owned one, depending on the vehicle's sourcing requirements, its price, and the buyer's income.
Other IRS Forms for Corporations
There is a big number of official documents developed for US citizens by the IRS. Make sure to learn other forms you might need to file with the Service.
What it is: Form 8936, Clean Vehicle Credits, figures credits for clean vehicles you placed in service during your tax year.[2]
Where and when to file: Attach Form 8936 to your tax return.
Individuals who transferred the credit to the dealer at the time of sale must file this form and Schedule A (Form 8936).
Partnerships and S corporations must file this form, Form 8936, to claim the new clean vehicle credit or the qualified commercial clean vehicle credit.[2]

Enter the Name(s) shown on return and the Identifying number.
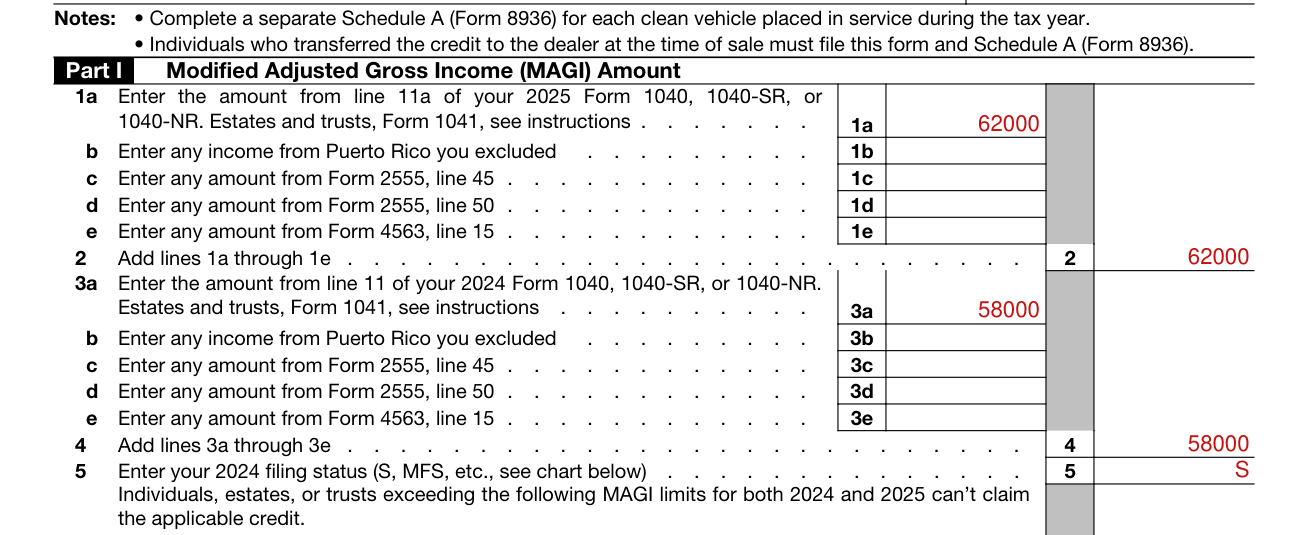
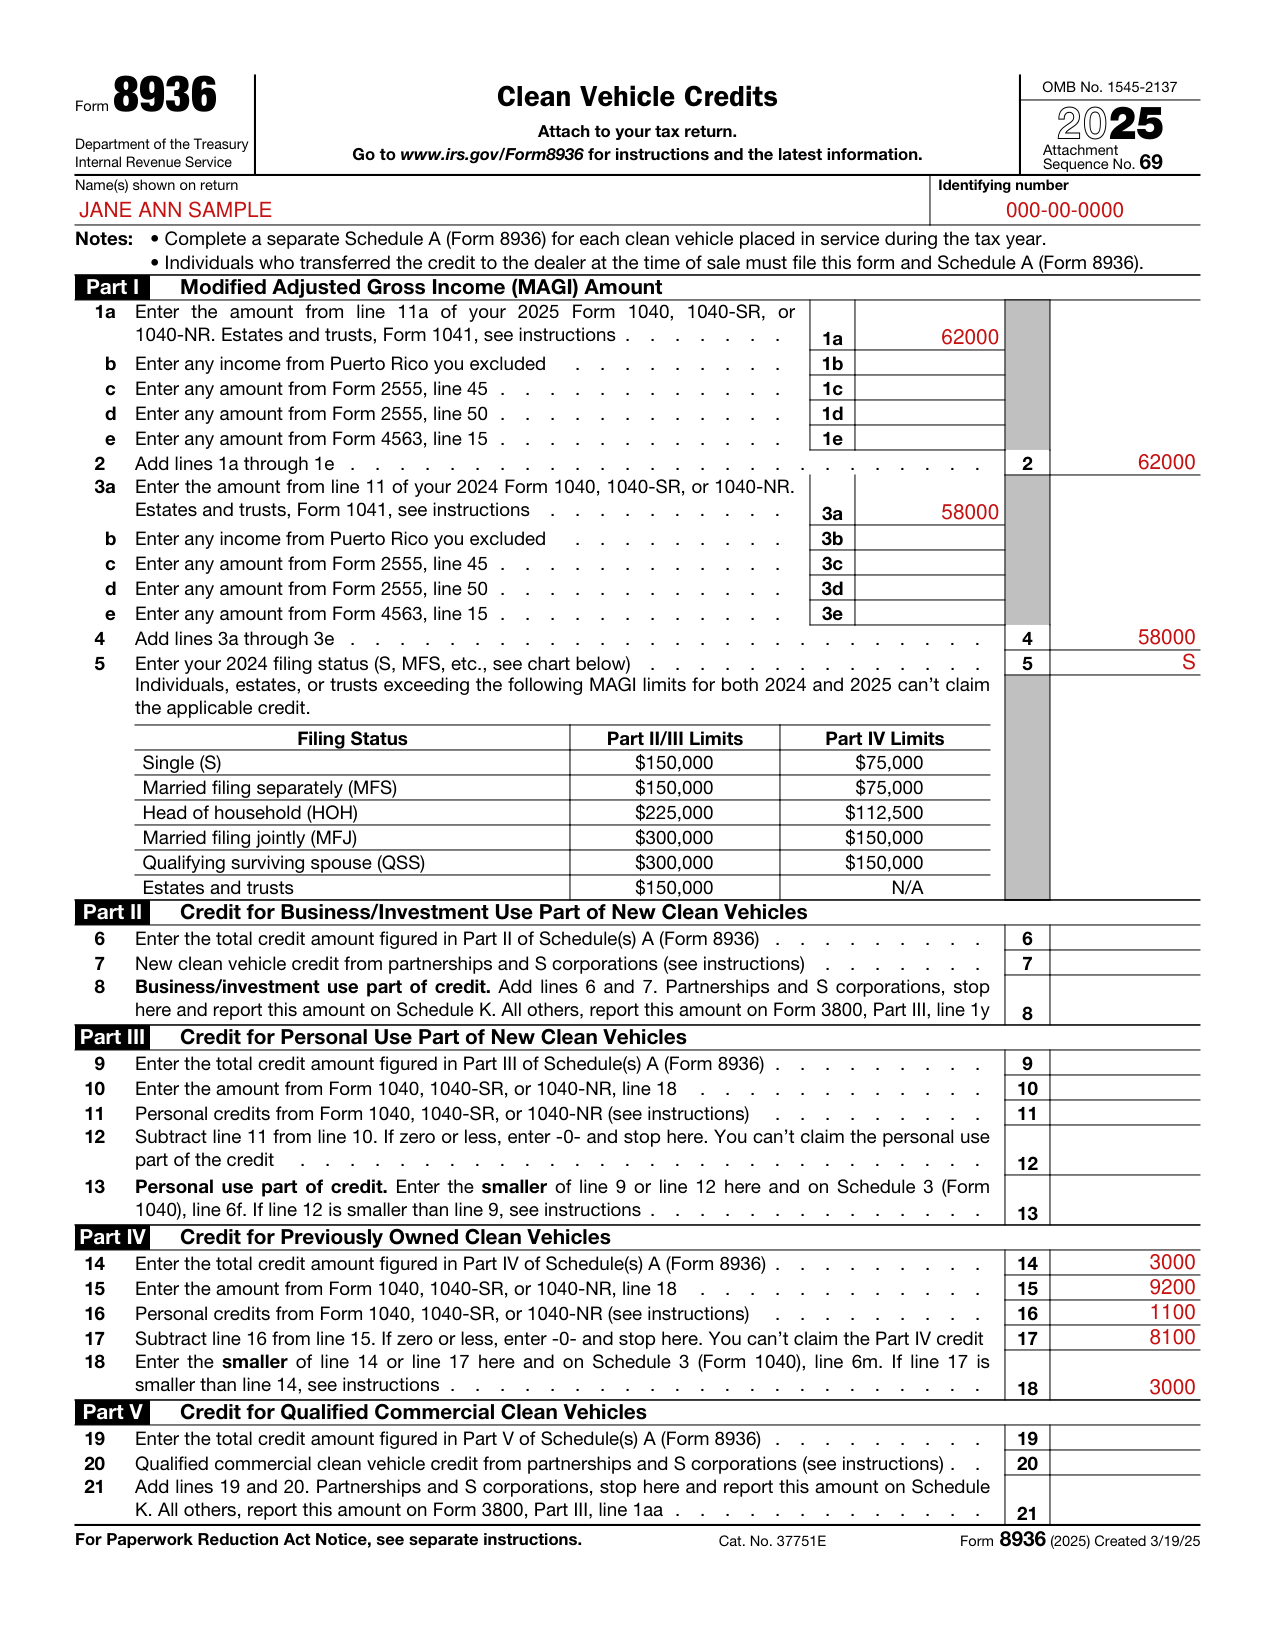
Enter your modified AGI for the current and prior tax year on lines 1a and 3a of Form 8936.
On line 1a, enter the amount from line 11a of your 2025 Form 1040, 1040-SR, or 1040-NR; on line 3a, enter the amount from line 11 of your 2024 Form 1040, 1040-SR, or 1040-NR. Estates and trusts, Form 1041, see instructions.
Enter any income from Puerto Rico you excluded on lines 1b and 3b, any amount from Form 2555, line 45 on lines 1c and 3c, any amount from Form 2555, line 50 on lines 1d and 3d, and any amount from Form 4563, line 15 on lines 1e and 3e.
Add lines 1a through 1e on line 2 and add lines 3a through 3e on line 4.
Enter your 2024 filing status (S, MFS, etc., see chart below) on line 5.[2]
Individuals, estates, or trusts exceeding the following MAGI limits for both 2024 and 2025 can't claim the applicable credit.
By filing status, the Part II/III Limits and Part IV Limits are: Single (S) $150,000 and $75,000; Married filing separately (MFS) $150,000 and $75,000; Head of household (HOH) $225,000 and $112,500; Married filing jointly (MFJ) $300,000 and $150,000; Qualifying surviving spouse (QSS) $300,000 and $150,000; Estates and trusts $150,000 and N/A (checked October 26, 2026).
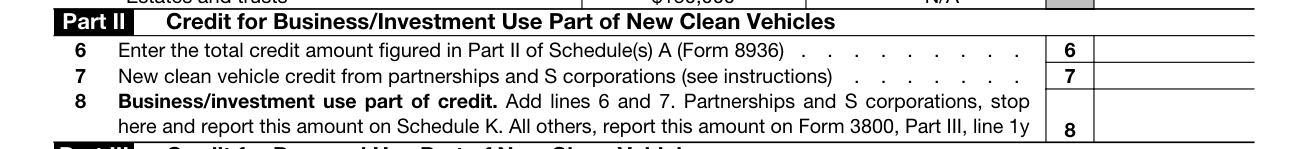
Use Parts I, II, and III of Form 8936 to claim the credit for new clean vehicles.
Enter the total credit amount figured in Part II of Schedule(s) A (Form 8936) on line 6.
On line 7, enter the total new clean vehicle credits from Schedule K-1 (Form 1065), box 15 (code AY); and Schedule K-1 (Form 1120-S), box 13 (code AY).
Add lines 6 and 7 on line 8. Partnerships and S corporations, stop here and report this amount on Schedule K. All others, report this amount on Form 3800, Part III, line 1y.[2]
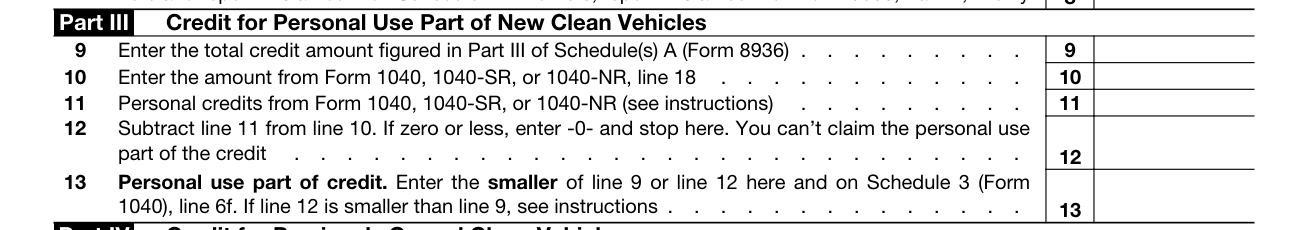
A taxpayer claiming a credit amount for the personal use part of a new clean vehicle must fill out Part II, even if they are not claiming a credit amount for business/investment use.
Enter the total credit amount figured in Part III of Schedule(s) A (Form 8936) on line 9.
Enter the amount from Form 1040, 1040-SR, or 1040-NR, line 18 on line 10.
On line 11, enter the total, if any, credits from Schedule 3 (Form 1040), lines 1 through 4, 5b, 6d, 6l, and 6m.
Subtract line 11 from line 10 on line 12. If zero or less, enter -0- and stop here. You can't claim the personal use part of the credit.
Enter the smaller of line 9 or line 12 on line 13 and on Schedule 3 (Form 1040), line 6f. If line 12 is smaller than line 9, see instructions.
On line 13, if you cannot use part of the personal portion of the credit because of the tax liability limit, the unused credit is lost. The unused personal portion of the credit cannot be carried back or forward to other tax years.[2]
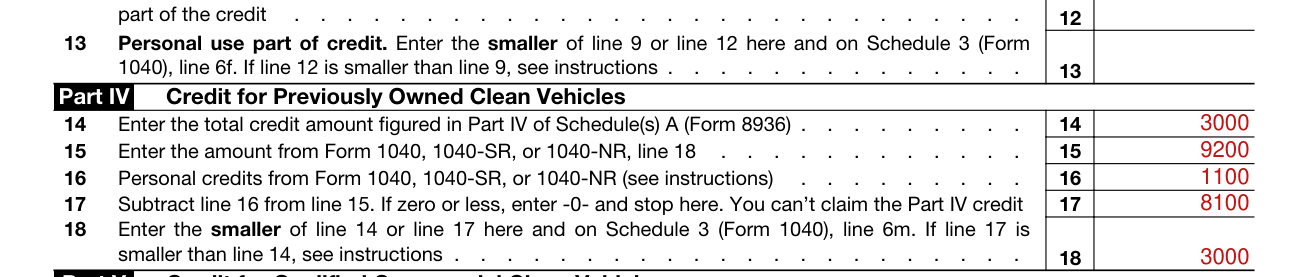
Use Parts I and IV of Form 8936 to claim the credit for previously owned clean vehicles.
The credit is equal to the lesser of $4,000 or 30% of the sales price of a previously owned clean vehicle you acquired and placed in service during your tax year (checked October 26, 2026).
In Part IV Credit for Previously Owned Clean Vehicles, enter the total credit amount figured in Part IV of Schedule(s) A (Form 8936) on line 14.
Enter the amount from Form 1040, 1040-SR, or 1040-NR, line 18 on line 15.
For Previously Owned Clean Vehicles, enter the total, if any, credits from Schedule 3 (Form 1040), lines 1 through 4, 5b, 6d, and 6l, on line 16.
Subtract line 16 from line 15 on line 17. If zero or less, enter -0- and stop here. You can't claim the Part IV credit.
Enter the smaller of line 14 or line 17 on line 18 and on Schedule 3 (Form 1040), line 6m. If line 17 is smaller than line 14, see instructions.
On line 18, if you cannot use part of the credit because of the tax liability limit, the unused credit is lost. The unused credit cannot be carried back or forward to other tax years.[2]
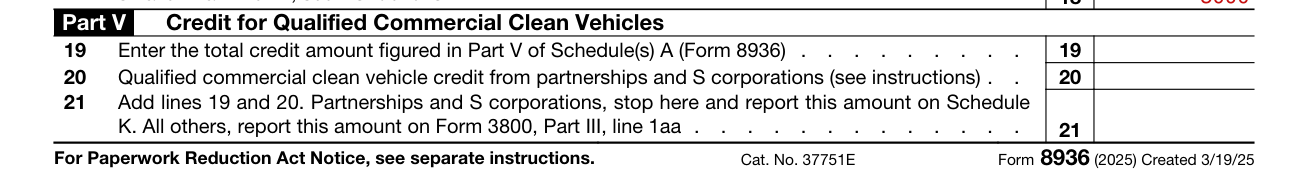
Use Part V of Form 8936 to claim the credit for qualified commercial clean vehicles.
Enter the total credit amount figured in Part V of Schedule(s) A (Form 8936) on line 19.
On line 20, enter the total qualified commercial clean vehicle credits from Schedule K-1 (Form 1065), box 15 (code AZ); and Schedule K-1 (Form 1120-S), box 13 (code AZ).
Add lines 19 and 20 on line 21. Partnerships and S corporations stop here on line 21 and report this amount on Schedule K. All others, report this amount on Form 3800, Part III, line 1aa.[2]
Complete a separate Schedule A (Form 8936) for each clean vehicle placed in service during the tax year.
Enter $150,001 for any year the estate or nongrantor trust was not in existence (checked October 26, 2026). Otherwise, enter the amount from line 17 of Form 1041.[2]
All other taxpayers are not required to complete or file this form, Form 8936, if their only source for the new clean vehicle credit or the qualified commercial clean vehicle credit is a partnership or S corporation. Instead, they can report the new clean vehicle credit directly on line 1y and the qualified commercial clean vehicle credit directly on line 1aa in Part III of Form 3800, General Business Credit.[2]
Taxpayers cannot claim clean vehicle credits for new, previously owned, or commercial clean vehicles that they acquired after September 30, 2025.
For purposes of sections 25E, 30D, and 45W, a vehicle is acquired as of the date a written binding contract is entered into and a payment has been made. A payment includes a nominal down payment or a vehicle trade-in.[2]
If you elect to transfer the credit, you must file Form 8936 and Schedule A (Form 8936) with your return for the tax year in which the vehicle was placed in service.[2]
Form 8936, Clean Vehicle Credits, figures credits for clean vehicles you placed in service during your tax year. The credits are the new clean vehicle credit, the previously owned clean vehicle credit and the qualified commercial clean vehicle credit.[2]
One requirement for the previously owned clean vehicle credit is that you have not claimed another previously owned clean vehicle credit in the 3 years before the purchase date.[2]
If you purchased a new or previously owned clean vehicle from a registered dealer and reduced the amount you paid at the time of sale by transferring the credit to the dealer and you no longer qualify for the credit when you file your tax return, you must repay the amount of the credit that you transferred to the dealer. If the vehicle no longer qualifies for the credit, you may have to recapture part or all of the credit.[2]
Attach Form 8936 to your tax return.
[1] Form 8936 (2025), Clean Vehicle Credits, Department of the Treasury Internal Revenue Service (the Official source link on this page).