
Form 730 at a glance
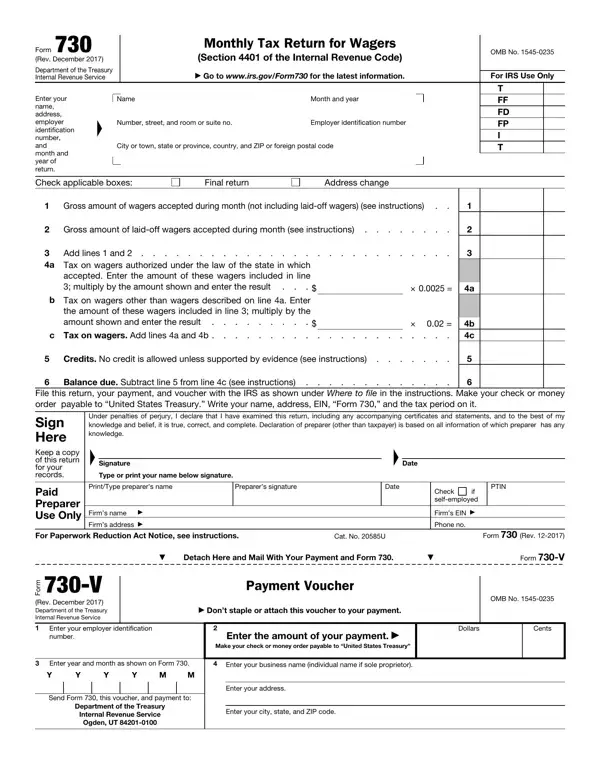
What it is: Form 730 is the Monthly Tax Return for Wagers (Section 4401 of the Internal Revenue Code). Section 4401 imposes a tax on wagering. Form 730 is used to determine the amount of the tax.
Who signs: File a return each month whether or not you have taxable wagers to report. If you have no tax to report, write “None” in the entry space for line 6 and sign and date Form 730. A paid preparer must sign Form 730 and provide the information in the Paid Preparer Use Only section at the end of the form if the preparer was paid to prepare the form and isn't an employee of the filing entity.
General Instructions. Who must file. You must file Form 730 and pay the tax on wagers under section 4401(a) if you are in the business of accepting wagers, conduct a wagering pool or lottery, or are required to be registered and you received wagers for or on behalf of another person but didn't report that person's name and address.
Use Form 11-C, Occupational Tax and Registration Return for Wagering, to register.
A filled-in Form 730 example: a sportsbook files for one month
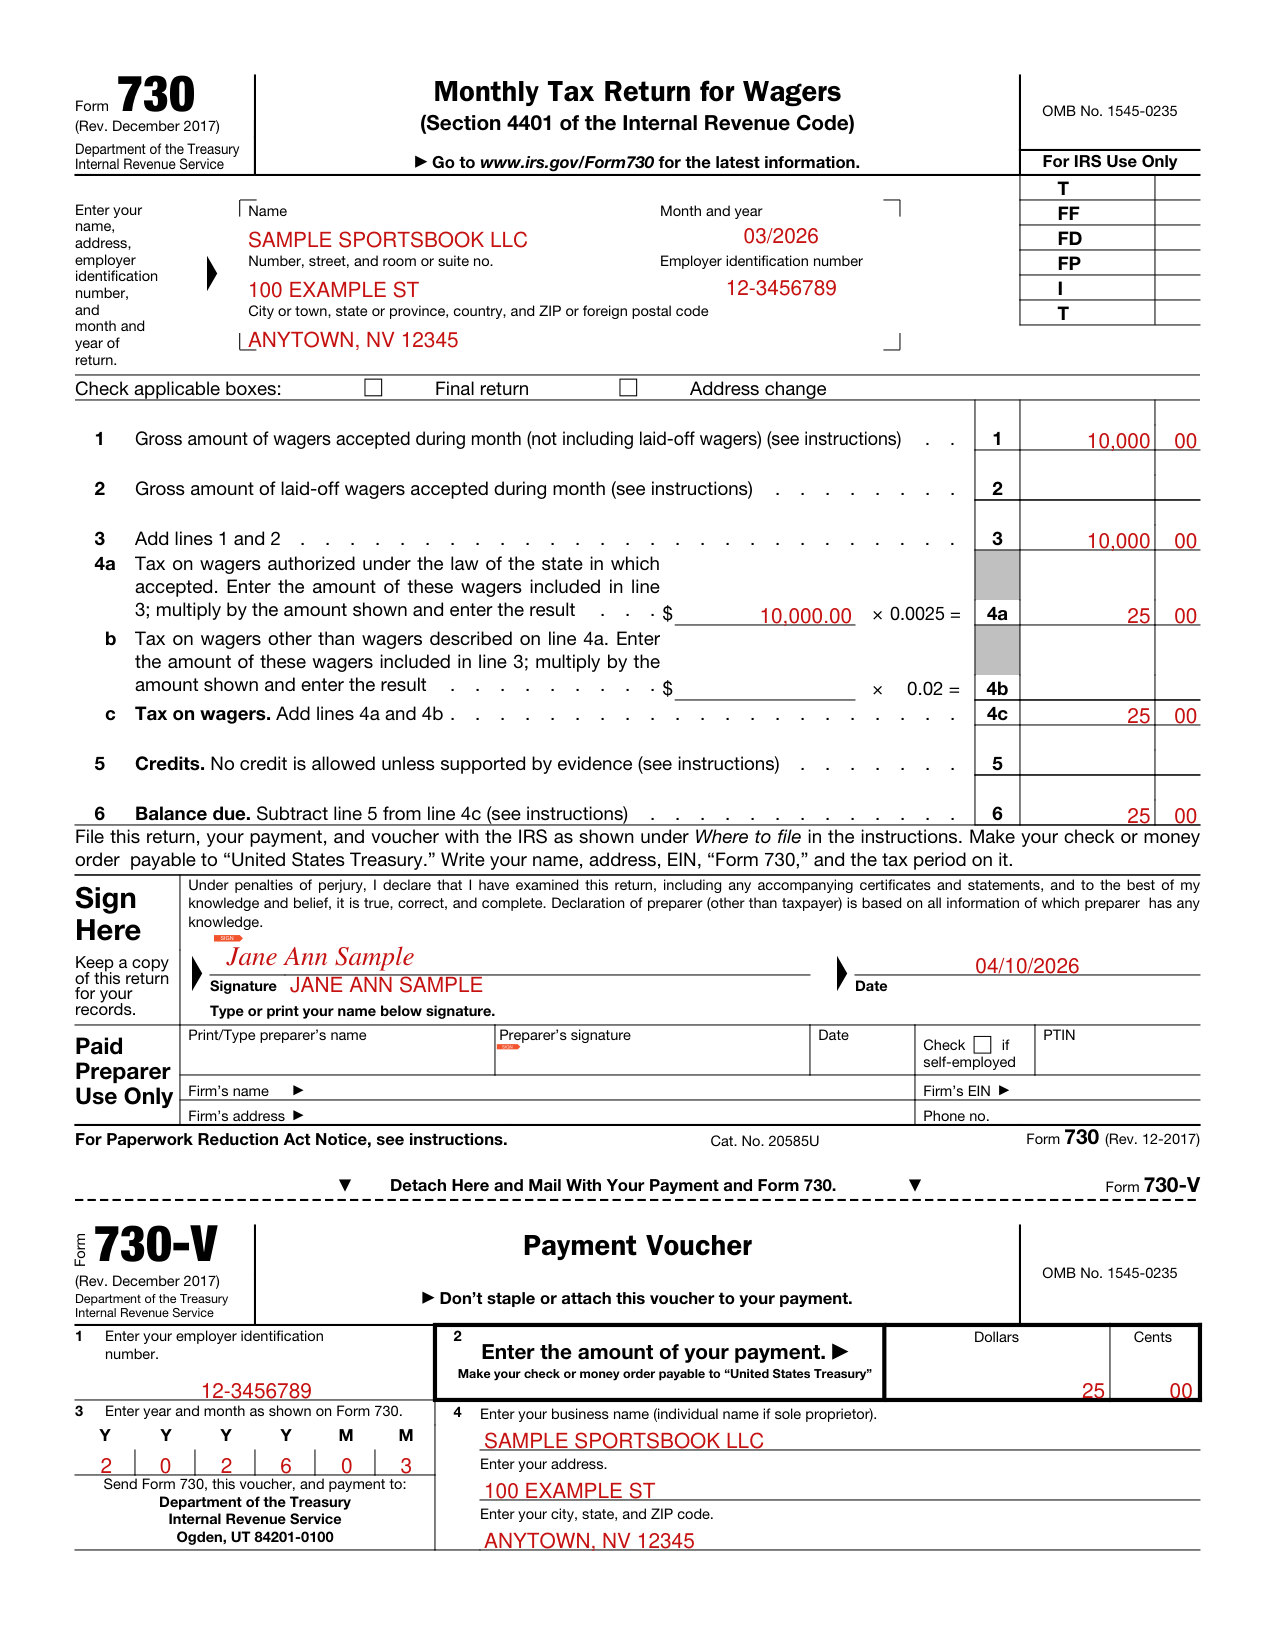
How to fill out Form 730, box by box
Enter your name, address, employer identification number, and month and year of return
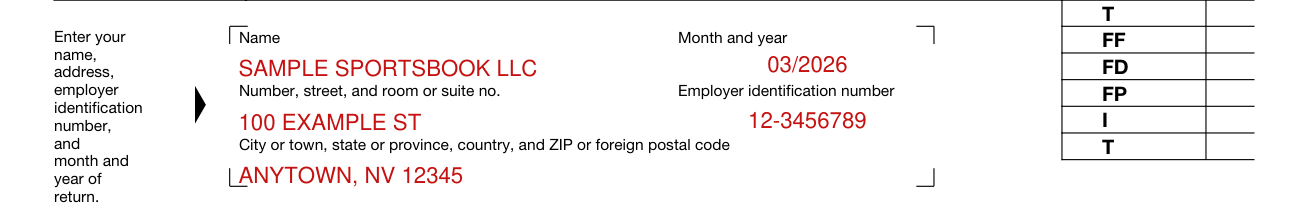
If you aren't using the preaddressed Form 730, enter your name, address, employer identification number (EIN), and the month (MM) and year (YYYY) for which this form is filed.
Enter the name shown on the eligible entity's most recently filed federal income tax return.
Include the suite, room, or other unit number after the street address. If the Post Office doesn't deliver mail to the street address and the entity has a P.O. box, show the box number instead of the street address.
Check applicable boxes

If you stop accepting wagers, check the final return box above line 1. Check applicable boxes: Final return, Address change.
Lines 1 and 2: gross amount of wagers

Line 1. Enter the gross amount of wagers accepted during the month. Gross wagers are the total of those wagers that are authorized and those wagers that aren't authorized by the state in which they are accepted.
Include all charges connected with placing the wager, including any fee or charge incident to placing the wager. If you can prove that the person placing the wager has paid a separate charge equal to the tax, don't include that amount in the amount of the wager. Don't include laid-off wagers in this amount.
Line 2. Enter the gross amount of any laid-off wagers accepted during the month. Gross laid-off wagers are the total of those laid-off wagers that are authorized and those that aren't authorized by the state in which they are accepted.
Lines 3 to 4c: tax on wagers
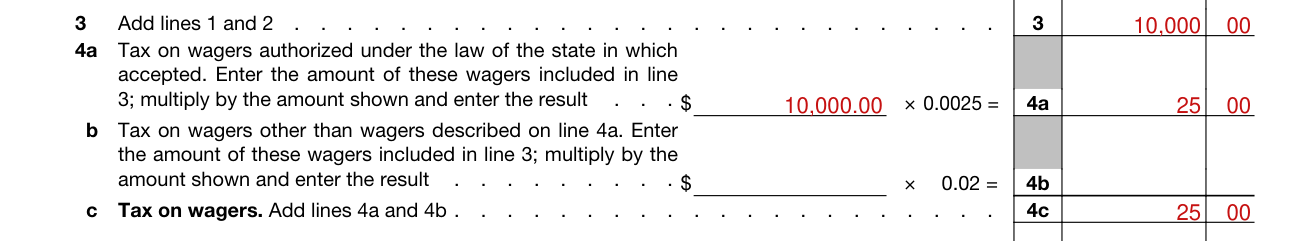
Lines 4a and 4b. Enter the applicable amount included in line 3. Multiply the amount by the rate shown and enter the result.
The rate of tax depends on whether the wager is authorized by the laws of the state in which the wager was accepted. The lower rate applies to wagers that are authorized by state law.
Line 3: Add lines 1 and 2. Line 4a: for wagers authorized under the law of the state in which accepted, enter the amount of these wagers included in line 3 and multiply by the amount shown, 0.0025, and enter the result. Line 4b: for wagers other than wagers described on line 4a, enter the amount of these wagers included in line 3 and multiply by the amount shown, 0.02, and enter the result. Line 4c: add lines 4a and 4b.
Line 5: credits
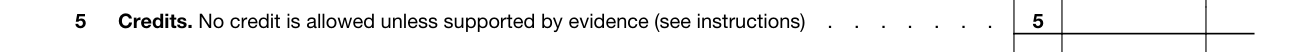
Line 5. Credits. No credit is allowed unless supported by evidence. You may be able to claim a credit for the amount of any overpayment of tax or for the amount of tax imposed with respect to a wager that you laid off.
Line 6

Line 6. Balance due. Subtract line 5 from line 4c. File this return, your payment, and voucher with the IRS. Make your check or money order payable to “United States Treasury.” Write your name, address, EIN, “Form 730,” and the tax period on it. If line 4c is more than line 5, enter the difference on line 6.
You don't have to pay if line 6 is under $1.00. (checked November 12, 2026)
You may pay the amount shown on line 6 using the Electronic Federal Tax Payment System (EFTPS) or by check or money order.
Sign Here
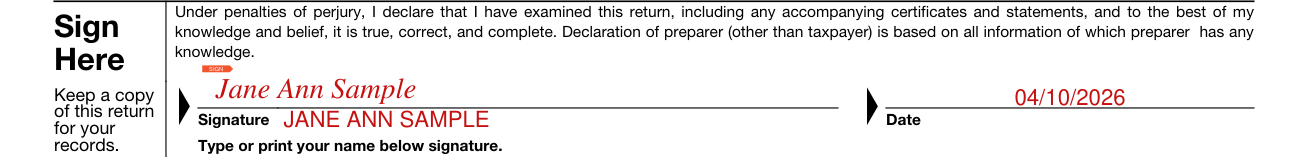
By signing, you declare under penalties of perjury that you have examined this return, including any accompanying certificates and statements, and that to the best of your knowledge and belief, it is true, correct, and complete.
Keep a copy of this return for your records.
Paid Preparer Use Only
If you're a paid preparer, enter your Preparer Tax Identification Number (PTIN) in the space provided. If you work for a tax preparation firm, you must also enter the firm's name, address, and EIN. However, you can't use the PTIN of the tax preparation firm in place of your PTIN.
Form 730-V, Payment Voucher
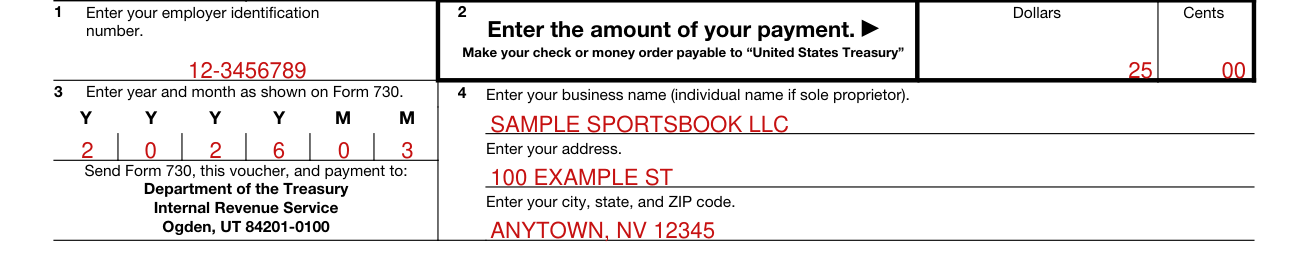
Purpose of Form 730-V, Rev. 12-2017, page 2: complete Form 730-V if you're making a payment by check or money order with Form 730.
Don't file Form 730-V if you're paying the balance due on Form 730, line 6, using the Electronic Federal Tax Payment System (EFTPS).
Box 1. Enter your employer identification number. If you don't have an EIN, you may apply for one online. Go to the IRS website at www.irs.gov/EIN.
Box 2. Enter the amount paid from line 6 of Form 730.
Box 3. Enter year and month as shown on Form 730. Enter the same date you entered on page 1 of Form 730.
Box 4. Enter your business name (individual name if sole proprietor). Enter your name and address as shown on Form 730.
Don't send cash.
Don't staple this voucher or your payment to Form 730 (or to each other).
Detach the completed voucher and send it with your payment and Form 730. Send Form 730, this voucher, and payment to: Department of the Treasury Internal Revenue Service Ogden, UT 84201-0100
More rules for Form 730
The IRS won't send you a notice that a return is due.
If your situation is different
You round amounts to whole dollars
You may round amounts to whole dollars. If you do round, leave the entry for the cents amounts blank.
If you do round, do so for all amounts.
What isn't taxed
The tax isn't imposed on the following five items.
Parimutuel wagering, including horse racing, dog racing, and jai alai, when it's licensed under state law.
Coin-operated devices, such as slot machines, pinball machines, or video games.
Sweepstakes, wagering pools, or lotteries that are conducted by an agency of a state, if the wager is placed with the state agency or its authorized agents or employees.
Games of the type in which all persons placing wagers in the game are present when wagers are placed, winners are determined, and prizes or other property are distributed.
Drawings conducted by an organization exempt from tax under sections 501 and 521, as long as the net proceeds of the drawing don't benefit a private shareholder or individual.
Common questions about Form 730
Is there a deadline?
If you're liable for the tax, file Form 730 for each month by the last day of the month following the month for which you're reporting taxable wagers.
Where do I file it?
Send your return to: Department of Treasury Internal Revenue Service Ogden, UT 84201-0100
Is there a penalty?
Avoid penalties and interest by filing returns and paying taxes when due. The law provides penalties for filing a return late, paying taxes late, failing to file a return, negligence, and fraud. These penalties are in addition to the interest charge on late payments.
Sources
[1] Form 730 (Rev. December 2017), Monthly Tax Return for Wagers, Internal Revenue Service (the Official source link on this page).