
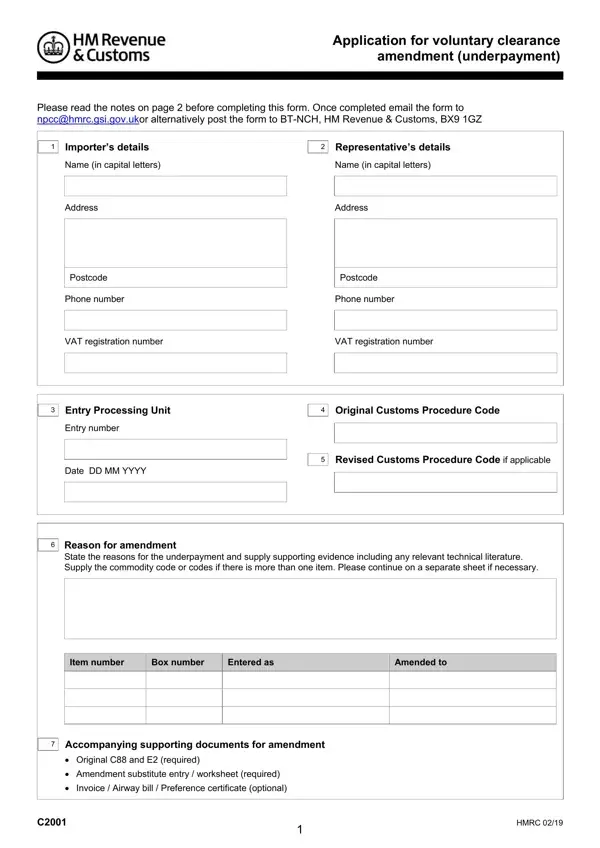

Form C2001 at a glance
What it is: Application for voluntary clearance amendment (underpayment): This form is for Customs Handling of Import and Export Freight (CHIEF) claims only.
Where and when to file: Once completed email the form to npcc@hmrc.gov.uk or alternatively post the form to BT-NCH, HM Revenue and Customs, BX9 1GZ.
What to bring and attach to Form C2001
Accompanying supporting documents for amendment: original C88 and E2 (required), amendment substitute entry/worksheet (required), invoice/Airway bill/Preference certificate (optional).
A filled-in Form C2001 example: an importer corrects an underpayment
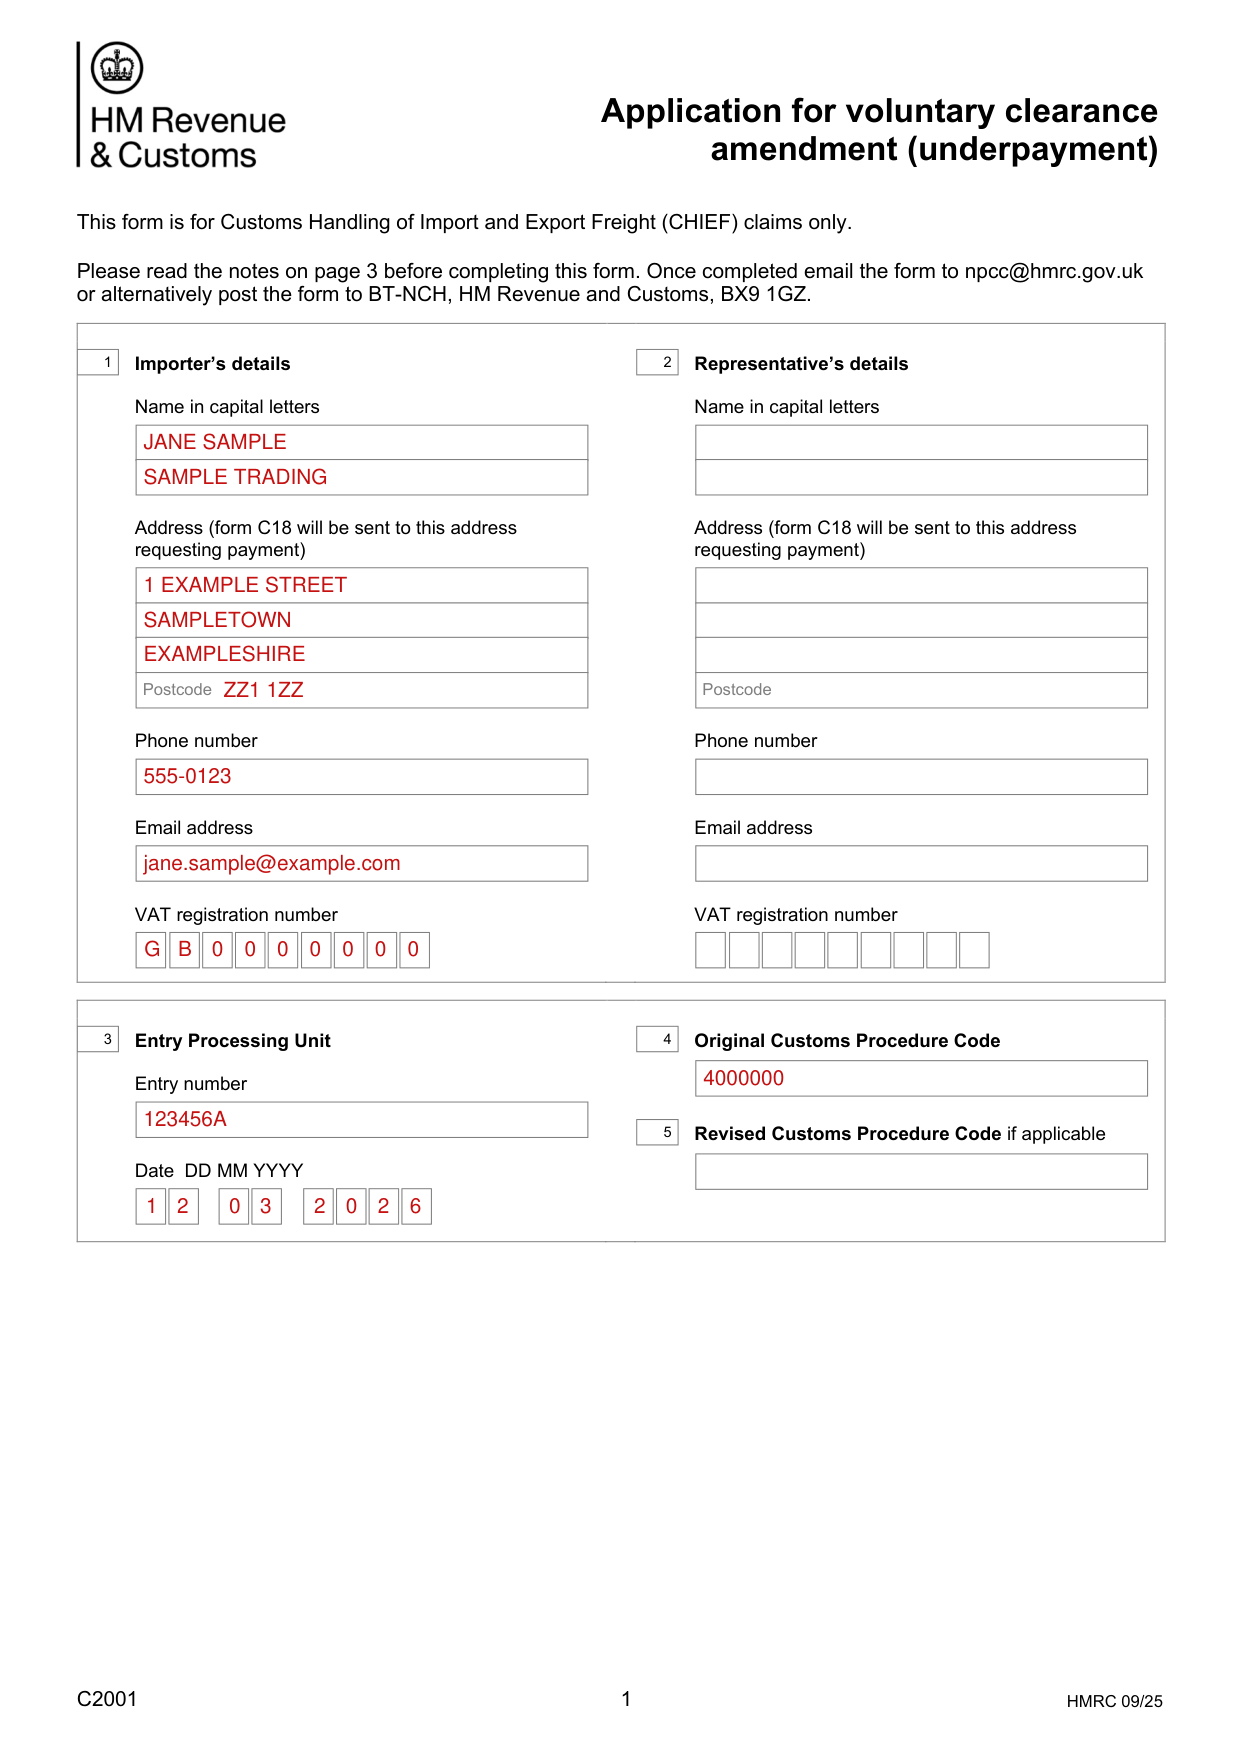
How to fill out Form C2001, box by box
Importer's details and Representative's details
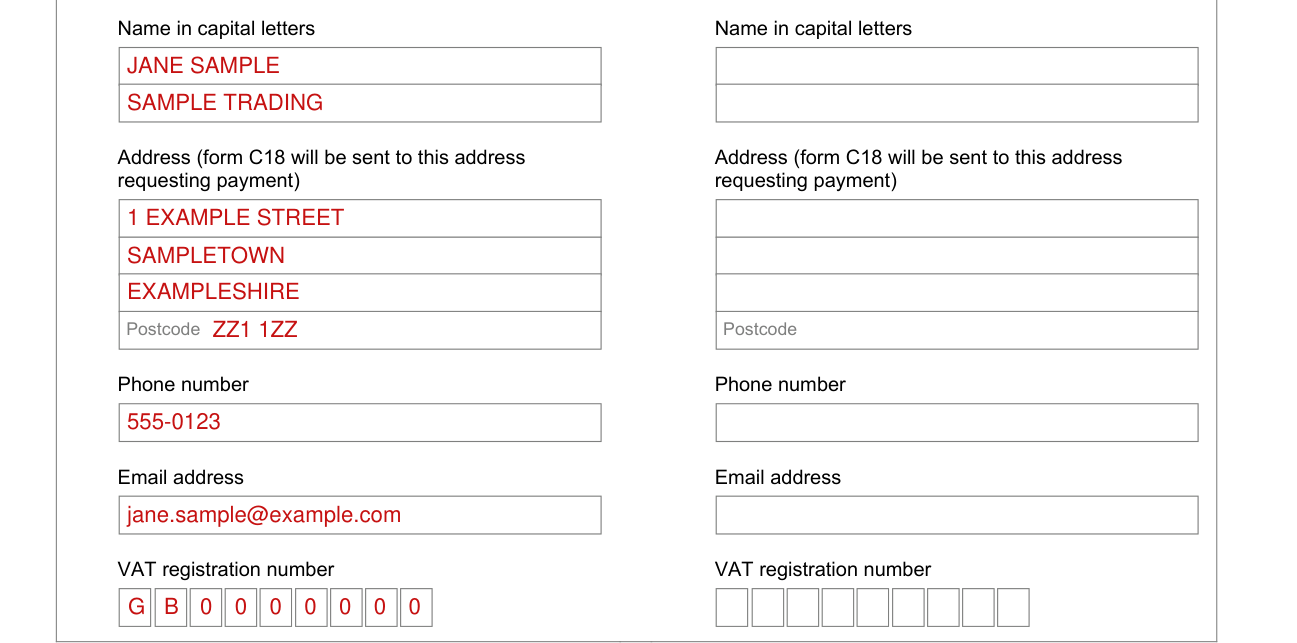
Under Importer's details, enter the Name in capital letters.
Under Importer's details, form C18 will be sent to the Address you enter, requesting payment.
Under Representative's details, enter the Name in capital letters and the Address; form C18 will be sent to the Address you enter, requesting payment.
Under Importer's details and Representative's details, enter the Postcode, Phone number, Email address and VAT registration number.
Entry Processing Unit
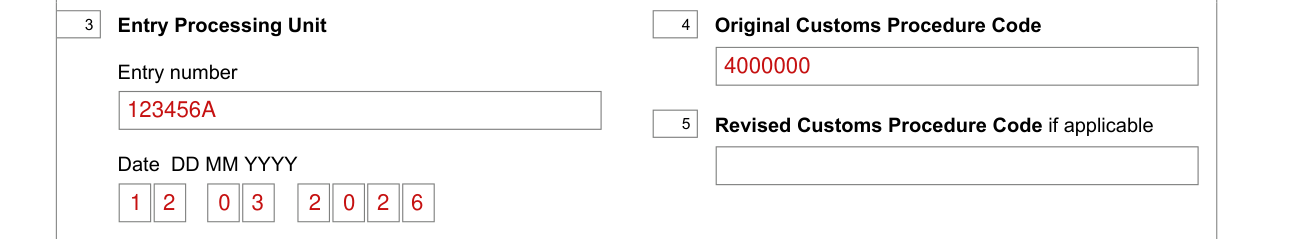
Enter the Entry number of the Entry Processing Unit.
Enter the Date as DD MM YYYY.
Enter the Original Customs Procedure Code and the Revised Customs Procedure Code if applicable.
Reason for amendment
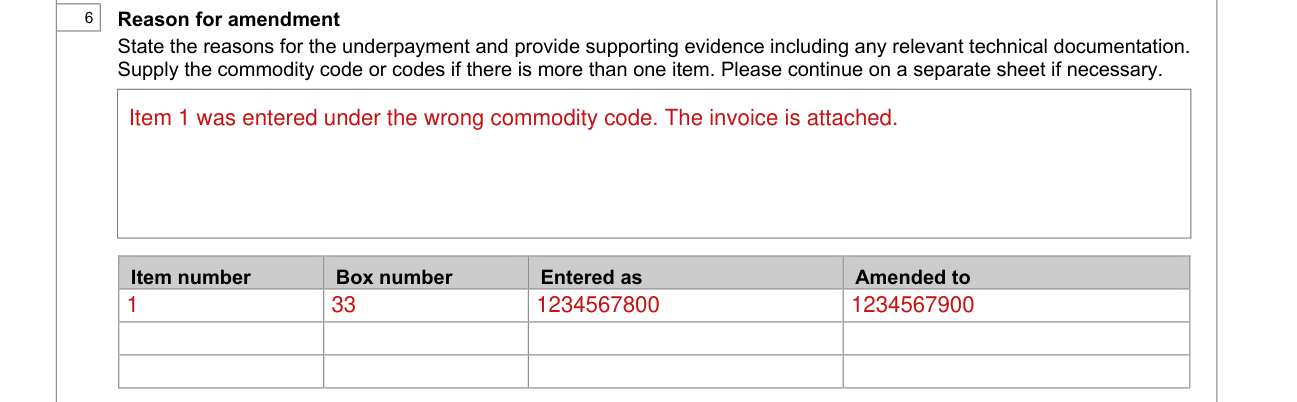
In Reason for amendment, state the reasons for the underpayment and provide supporting evidence including any relevant technical documentation.
Supply the commodity code or codes if there is more than one item.
For each item, enter the Item number, Box number, Entered as and Amended to.
Please continue on a separate sheet if necessary.
Amount of the underpayment
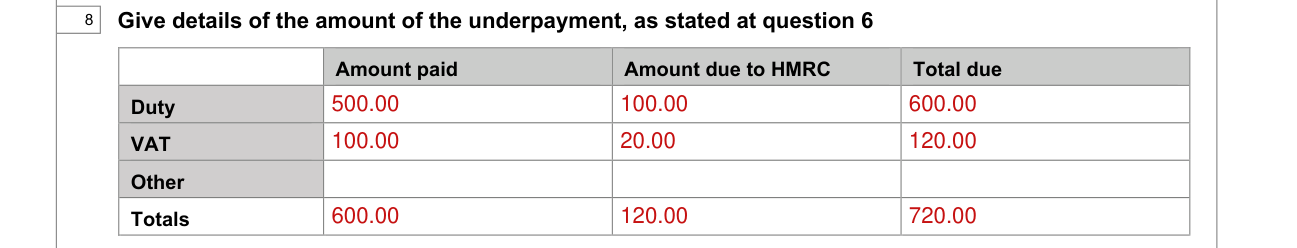
Give details of the amount of the underpayment, as stated at question 6: Amount paid, Amount due to HMRC and Total due for Duty, VAT, Other and Totals.
Deferment payment
Deferment payment: If you're making a payment by deferment, please supply full details.
However, if you wish to make the payment by deferment, please provide specific authority from the consignee relating to this amendment.
Please note that HM Revenue and Customs will not accept deferment authority provided for the original entry.
If you fail to provide the authority a C18 remittance advice will be issued for payment.
Declaration
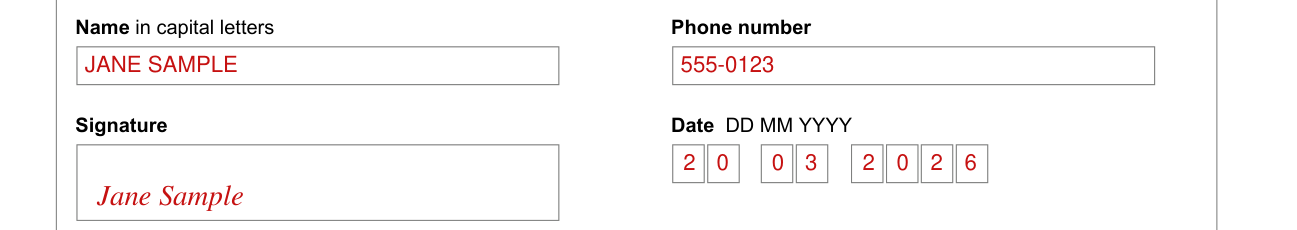
Declaration: "I declare that the information contained in this form and supporting documents is true and complete."
Enter the Name in capital letters, Phone number, Signature and Date DD MM YYYY.
More rules for Form C2001
Please read the notes on page 3 before completing this form.
If you complete the form by hand please use a black pen and make sure that it is legible. It should not contain any erasures or overwritten words.
If you make any mistakes please cross them out and add the correct details as required. All corrections must be initialled.
To avoid duplicating the issue of a C18, please submit only one declaration.
The processing of your amendment may be delayed if the basis of your claim is unclear.
HM Revenue and Customs standards: HM Revenue and Customs aim to process your voluntary declaration within 10 working days of receiving a valid declaration.
Please note: interest may be due and payable on debts unpaid after 10 days of date of issue of the C18.
If there is an element of duty repayment the C18 team will first process the underpayment aspect and then pass the paperwork to the National Duty Repayment Centre (NDRC) to process the refund.
Overpayment of VAT can be reclaimed via the consignee's next VAT return.
Common questions about Form C2001
Where do I file it?
Once completed email the form to npcc@hmrc.gov.uk or alternatively post the form to BT-NCH, HM Revenue and Customs, BX9 1GZ.
When is this form not the right one?
Application for voluntary clearance amendment (underpayment): This form is for Customs Handling of Import and Export Freight (CHIEF) claims only.
Sources
[1] Form C2001 (HMRC 09/25), Application for voluntary clearance amendment (underpayment), HM Revenue and Customs (the Official source link on this page).