
Form 590-P at a glance
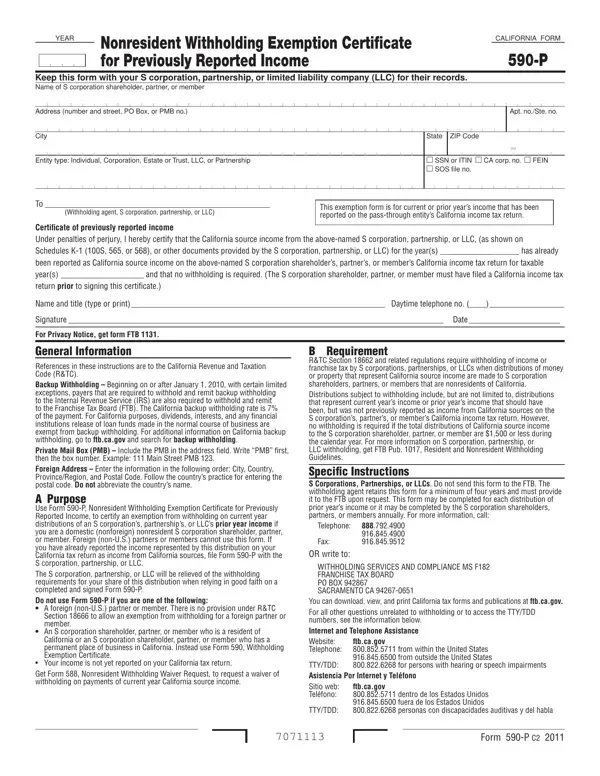
What it is: Nonresident Withholding Exemption Certificate for Previously Reported Income.
Where and when to file: The payee completes this form and submits it to the withholding agent.
Use Form 590-P, Nonresident Withholding Exemption Certificate for Previously Reported Income, if you are a nonresident S corporation shareholder, partner in a partnership, or member of an LLC to certify an exemption from withholding on current year distributions of an S corporation's, partnership's, or LLC's prior year California source income.
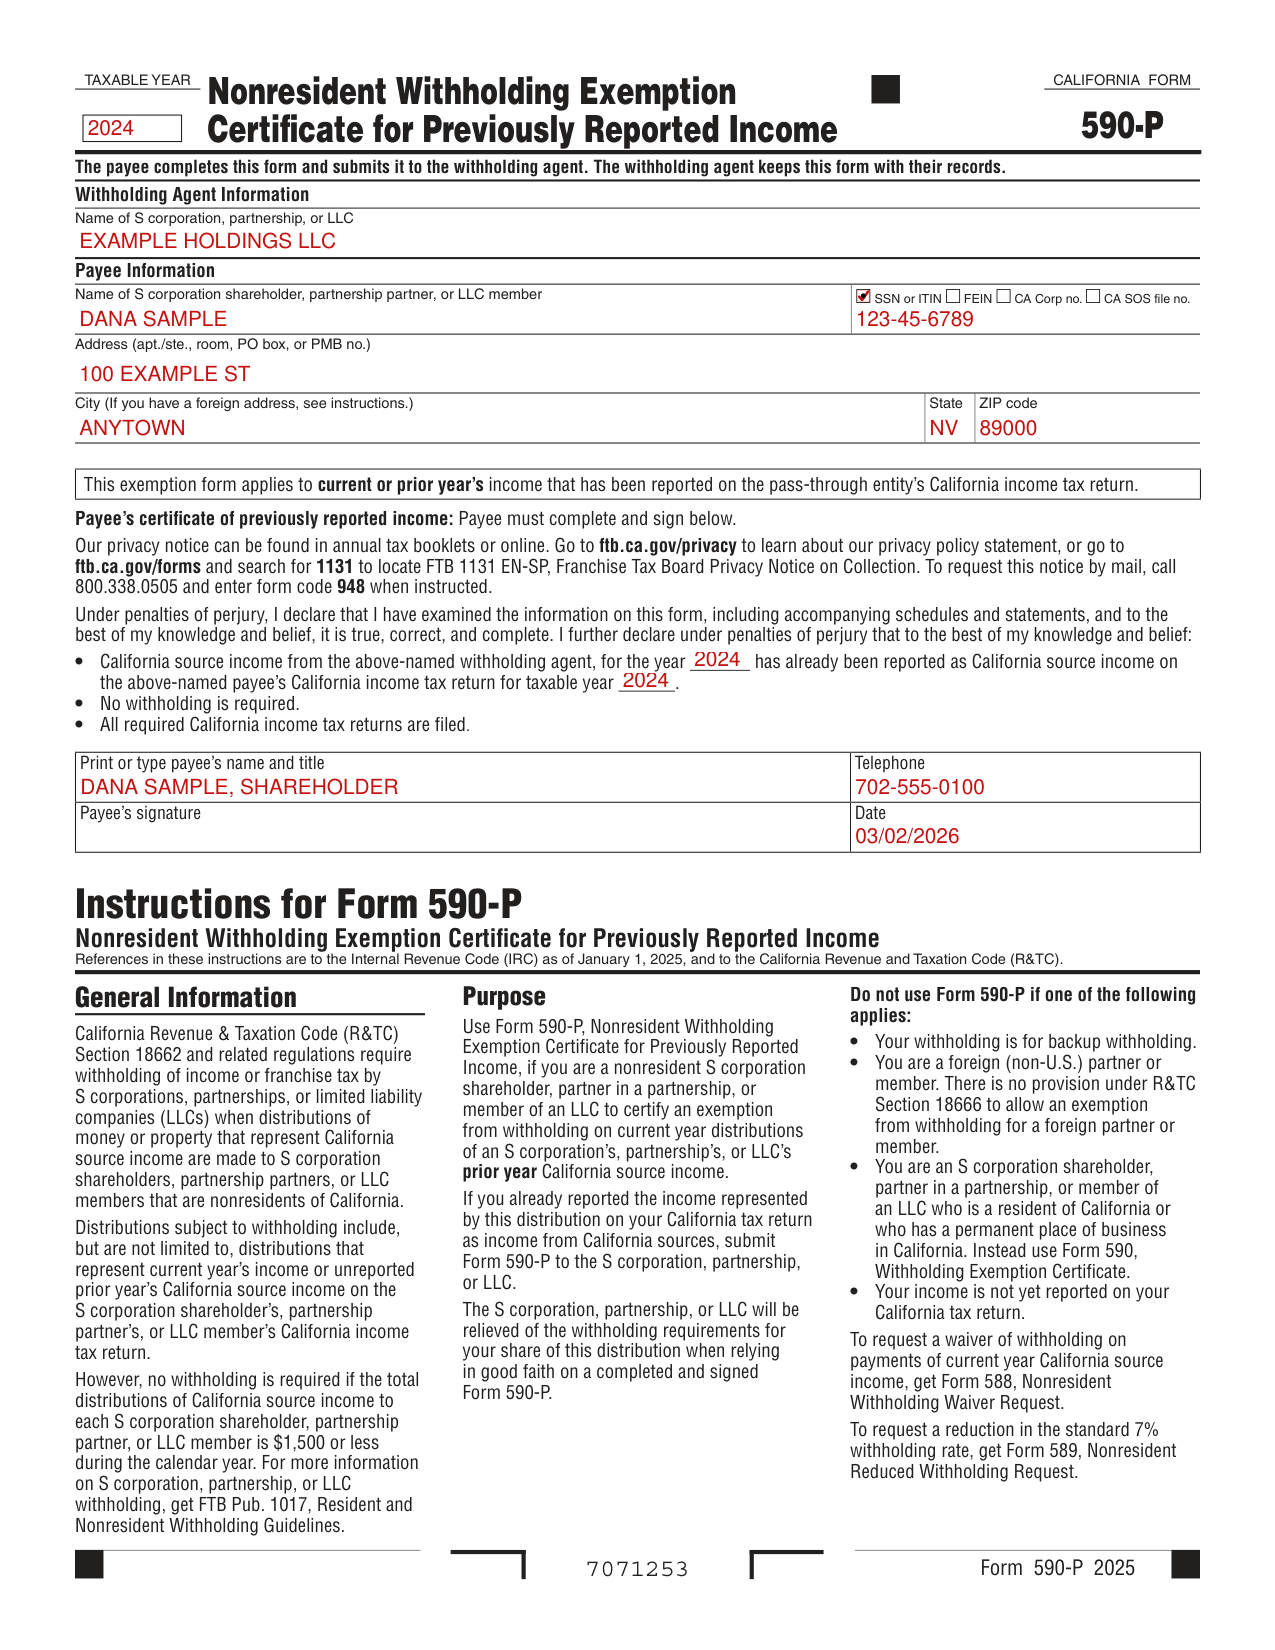
A filled-in Form 590-P example: a shareholder certifies 2024 income
How to fill out Form 590-P, box by box
Tax year

Page 2 of the Form 590-P Instructions 2025 has the Specific Instructions and the Payee Instructions.
Enter the tax year of the previously reported income in the box at the top of Form 590-P.
Withholding agent
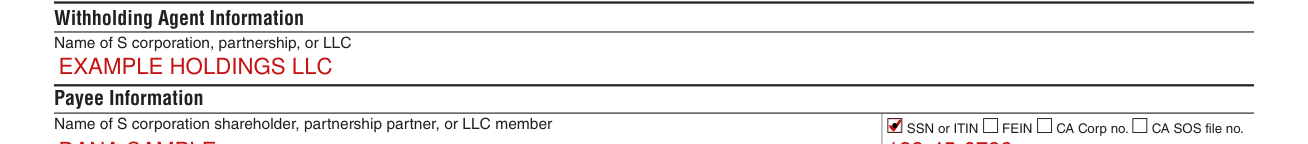
The payee completes this form and submits it to the withholding agent.
The withholding agent keeps this form with their records.
Withholding Agent Instructions: do not send this form to the Franchise Tax Board (FTB).
The withholding agent retains this form for a minimum of five years and must provide it to the FTB upon request.
This form may be completed for each distribution of prior year's income or it may be completed by the S corporation shareholder, partnership partner, or LLC member annually.
Taxpayer identification number and address
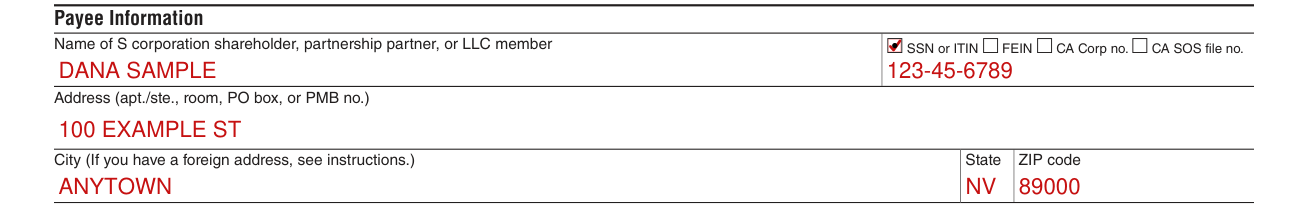
Enter the withholding agent's name and the S corporation shareholder's, partnership partner's, or LLC member's information, including the taxpayer identification number (TIN), and check the appropriate box.
You must provide a valid TIN as requested on this form. The following are acceptable TINs: social security number (SSN); individual taxpayer identification number (ITIN); federal employer identification number (FEIN); California corporation number (CA Corp no.); or California Secretary of State (CA SOS) file number.
Private MailBox (PMB) - Include the PMB in the address field. Write “PMB” first, then the box number. Example: 111 Main Street PMB 123.
Foreign Address - Follow the country's practice for entering the city, county, province, state, country, and postal code, as applicable, in the appropriate boxes. Do not abbreviate the country name.
Payee's certificate of previously reported income

Under penalties of perjury, I declare that I have examined the information on this form, including accompanying schedules and statements, and to the best of my knowledge and belief, it is true, correct, and complete.
I further declare under penalties of perjury that to the best of my knowledge and belief: California source income from the named withholding agent, for the year has already been reported as California source income on the named payee's California income tax return for taxable year .
No withholding is required.
All required California income tax returns are filed.
You must file all required California income tax returns prior to signing the certificate.
When not to use Form 590-P

Do not use Form 590-P if one of the following applies: your withholding is for backup withholding.
Do not use Form 590-P if you are a foreign (non-U.S.) partner or member. There is no provision under R&TC Section 18666 to allow an exemption from withholding for a foreign partner or member.
Do not use Form 590-P if you are an S corporation shareholder, partner in a partnership, or member of an LLC who is a resident of California or who has a permanent place of business in California. Instead use Form 590, Withholding Exemption Certificate.
Do not use Form 590-P if your income is not yet reported on your California tax return.
To request a waiver of withholding on payments of current year California source income, get Form 588, Nonresident Withholding Waiver Request.
To request a reduction in the standard 7% withholding rate, get Form 589, Nonresident Reduced Withholding Request.
Payee's signature

Payee's certificate of previously reported income: Payee must complete and sign the certificate.
More rules for Form 590-P
If you already reported the income represented by this distribution on your California tax return as income from California sources, submit Form 590-P to the S corporation, partnership, or LLC.
The S corporation, partnership, or LLC will be relieved of the withholding requirements for your share of this distribution when relying in good faith on a completed and signed Form 590-P.
This exemption form applies to current or prior year's income that has been reported on the pass-through entity's California income tax return.
California Revenue & Taxation Code (R&TC) Section 18662 and related regulations require withholding of income or franchise tax by S corporations, partnerships, or limited liability companies (LLCs) when distributions of money or property that represent California source income are made to S corporation shareholders, partnership partners, or LLC members that are nonresidents of California.
Distributions subject to withholding include, but are not limited to, distributions that represent current year's income or unreported prior year's California source income on the S corporation shareholder's, partnership partner's, or LLC member's California income tax return.
However, no withholding is required if the total distributions of California source income to each S corporation shareholder, partnership partner, or LLC member is $1,500 or less during the calendar year. (checked November 12, 2026)
For more information on S corporation, partnership, or LLC withholding, get FTB Pub. 1017, Resident and Nonresident Withholding Guidelines.
The privacy notice can be found in annual tax booklets or online.
Go to ftb.ca.gov/privacy to learn about the privacy policy statement, or go to ftb.ca.gov/forms and search for 1131 to locate FTB 1131 EN-SP, Franchise Tax Board Privacy Notice on Collection.
To request the privacy notice by mail, call 800.338.0505 and enter form code 948 when instructed.
Sources
[1] Form 590-P (2025), Nonresident Withholding Exemption Certificate for Previously Reported Income, Franchise Tax Board (the Official source link on this page).