

Form CDTFA-531 at a glance
What it is: CDTFA-531 is Schedule B, Detailed Allocation by County of Sales and Use Tax Transactions, of the California Department of Tax and Fee Administration.
Instructions for completing CDTFA-531, Schedule B, REV. 9 (5-18): if your business activities come within one or more of the categories in the instructions, part or all of your state and local sales and use tax should be allocated among the counties listed on CDTFA-531, Schedule B.
A filled-in Form CDTFA-531 example: a vending machine operator
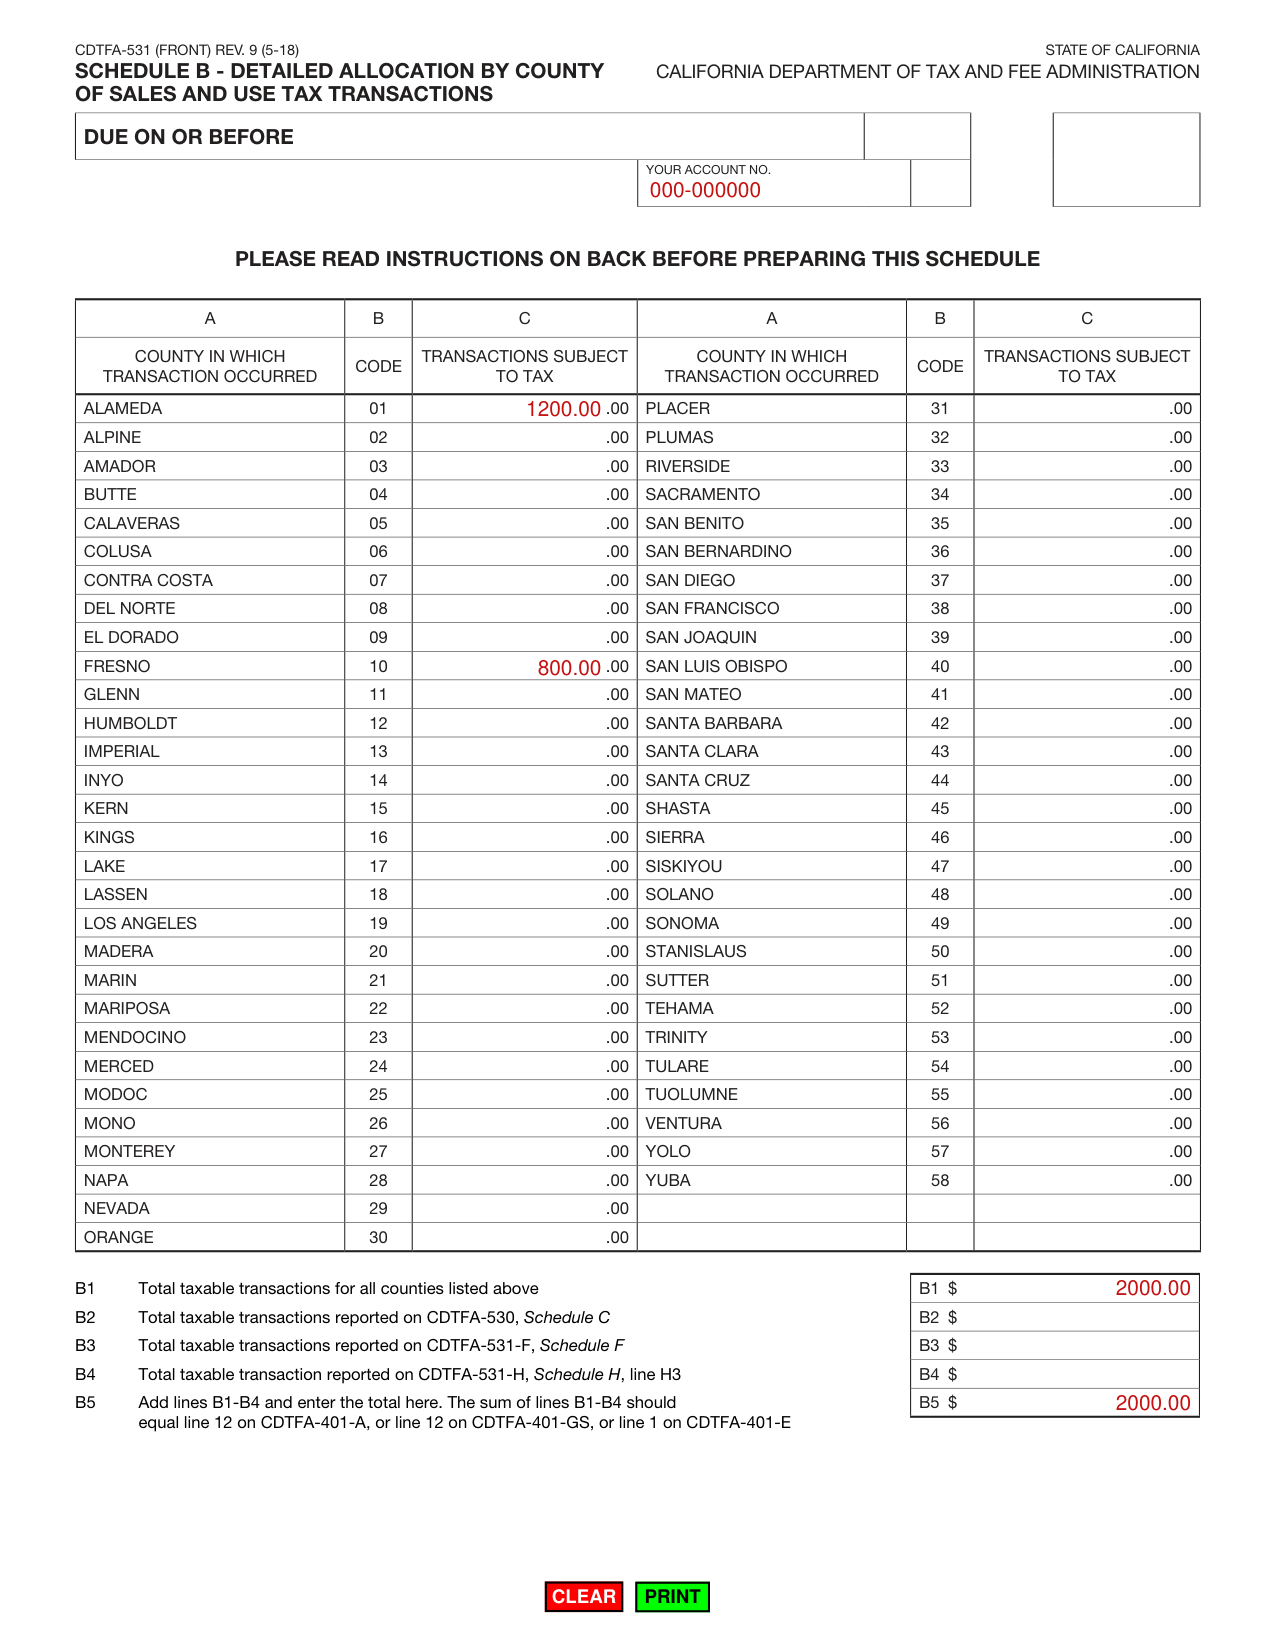
How to fill out Form CDTFA-531, box by box
Your account number

Enter your account number.
County in which transaction occurred
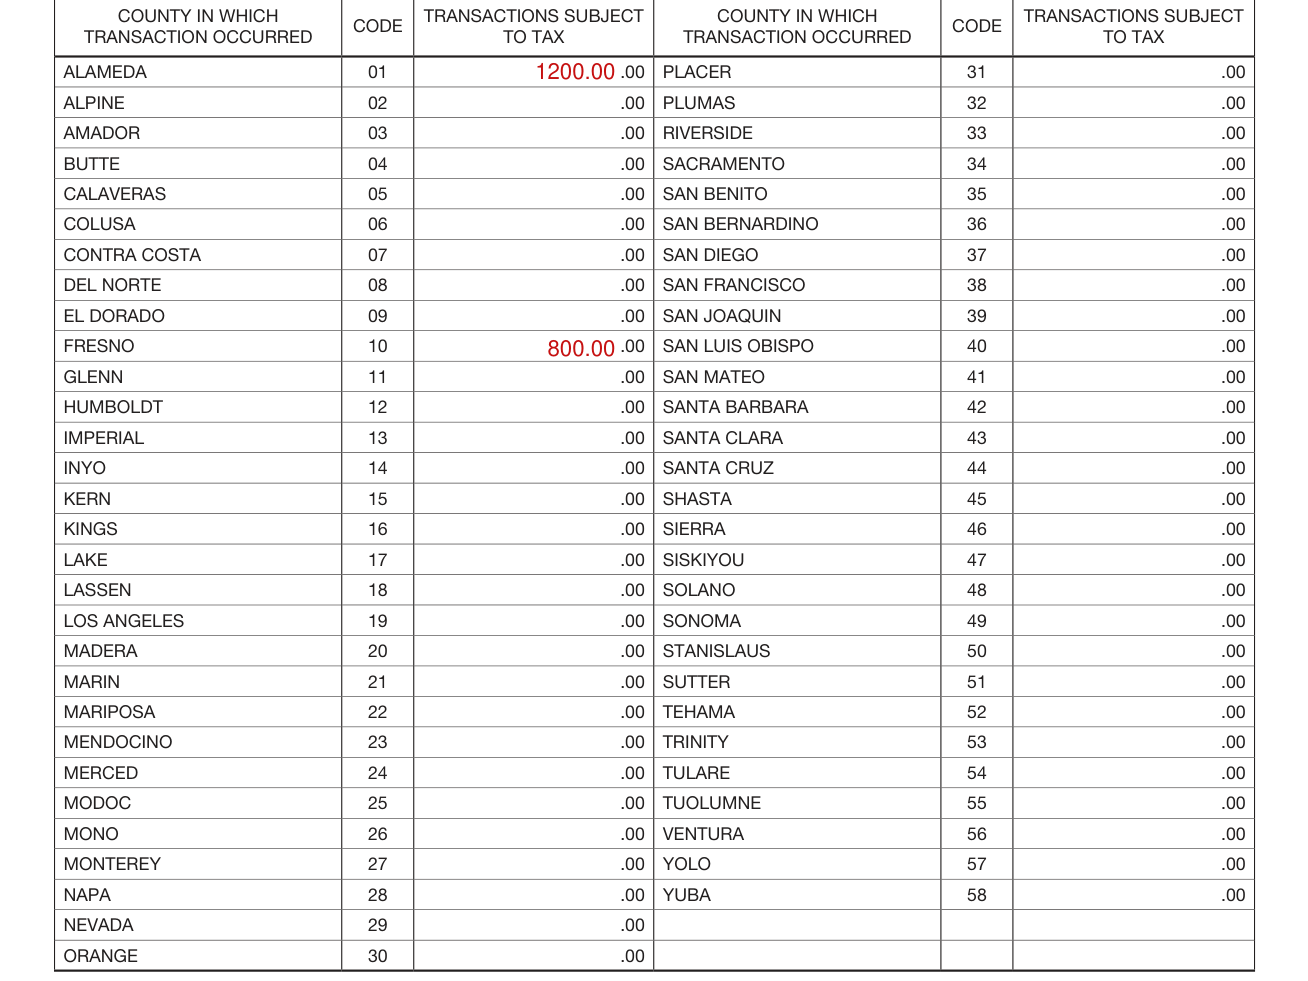
For each county in which a transaction occurred, enter in column C, after the name of the appropriate county, the amount of the taxable transaction subject to tax according to the instructions that are applicable to your business.
Totals B1 to B5
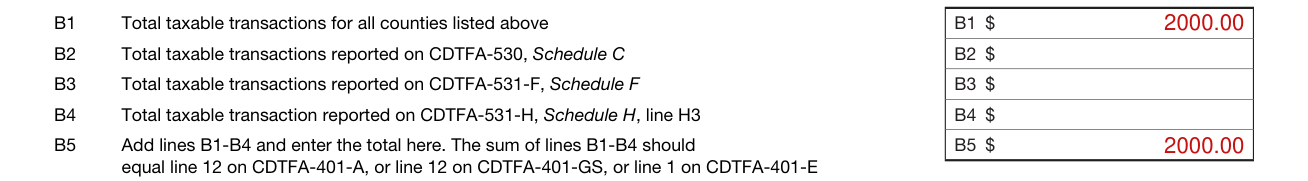
B1: Total taxable transactions for all counties.
B2: Total taxable transactions reported on CDTFA-530, Schedule C.
B3: Total taxable transactions reported on CDTFA-531-F, Schedule F.
B4: Total taxable transaction reported on CDTFA-531-H, Schedule H, line H3.
B5: Add lines B1-B4 and enter the total here. The sum of lines B1-B4 should equal line 12 on CDTFA-401-A, or line 12 on CDTFA-401-GS, or line 1 on CDTFA-401-E.
Which transactions go in column C
If you are an auctioneer
For auction events at temporary sales locations where taxable gross sales are $500,000 or more, taxable transactions should be reported on CDTFA 531-H, Schedule H. (checked November 3, 2026)
For all other auction events at temporary sales locations, the amount of taxable transactions made away from your permanent place of business should be entered in column C, opposite the name of each county in which auctions were held.
If you operate vending machines
Vending machine operators (Regulations 1574 and 1802): enter in column C the taxable transactions on sales made from vending machines located in each county.
The taxable transactions on sales of equipment or other transactions at your permanent place of business should be reported on CDTFA-530, Schedule C.
If you are an out-of-state seller engaged in business in California
Out-of-state sellers engaged in business in California (Regulations 1802 and 1803): sales negotiated out of state by sellers who are engaged in business in California, delivered from locations out of state with title passing to a California purchaser at a point outside of California, are subject to tax and should be entered in column C opposite the county of destination.
For transactions of $500,000 or more by sellers engaged in business in California, the taxable transaction should be reported on CDTFA-531-H, Schedule H. (checked November 3, 2026)
Sales of goods negotiated out of state and delivered from a stock of goods in state should be reported on CDTFA 530, Schedule C.
If you are an out-of-state seller not engaged in business in California
Sellers not engaged in business in California, but who voluntarily collect and report use tax, may report transactions of $500,000 or more on CDTFA-531-H, Schedule H, or continue to report on CDTFA 531, Schedule B. (checked November 3, 2026)
If you are a construction contractor
Construction contractors (Regulation 1806): a contractor must report the taxable transactions with respect to materials and fixtures involved in construction contracts according to the county location of the jobsite where use occurred.
Enter amount in column C opposite the appropriate county.
For transactions applicable to retail store sales or regular retail sales at your permanent place of business which do not involve a construction contract, the taxable amount should be reported on CDTFA-530, Schedule C.
If you are a person making ex-tax purchases for use at locations where a seller's permit is not required
Persons making ex-tax purchases for use at locations where a seller's permit is not required (Regulation 1803): a person who purchases tangible personal property without payment of tax is liable for use tax on such purchases.
If the property is used at a location which a seller's permit is not required, or at a location where a use tax permit is not issued, and is a purchase of less than $500,000, enter the amount in column C of this form opposite the county where the property is used. (checked November 3, 2026)
If property is used at a location for which a seller's permit is not required, or at a location where a use tax permit is not issued, and is a purchase of $500,000 or more, the taxable transaction should be reported on CDTFA 531-H, Schedule H. (checked November 3, 2026)
If you are a lessor of motor vehicles
If you are a lessor of motor vehicles who is not required to use CDTFA-531-F, Schedule F, you should report the taxable transaction on this Schedule in the county where the vehicle is registered.
If you are a mobile truck vendor or itinerant vendor
If you do not maintain a permanent place of business, but carry your merchandise with you or solicit door to door, you are considered an itinerant vendor.
Enter the amount of your taxable sales opposite the county in which the sales transaction occurred in column C.
If you are furnished with CDTFA-530, Schedule C, Detailed Allocation by Suboutlet of Sales and Use Tax Transactions, the amount entered on line B2 must agree with the total amount shown on CDTFA-530, Schedule C.
Before you go
Read the instructions on the back before preparing this schedule.
Sources
[1] Form CDTFA-531 (5-18), Schedule B, Detailed Allocation by County of Sales and Use Tax Transactions, California Department of Tax and Fee Administration (the Official source link on this page).